
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
What BBVA Doubters Overlooked
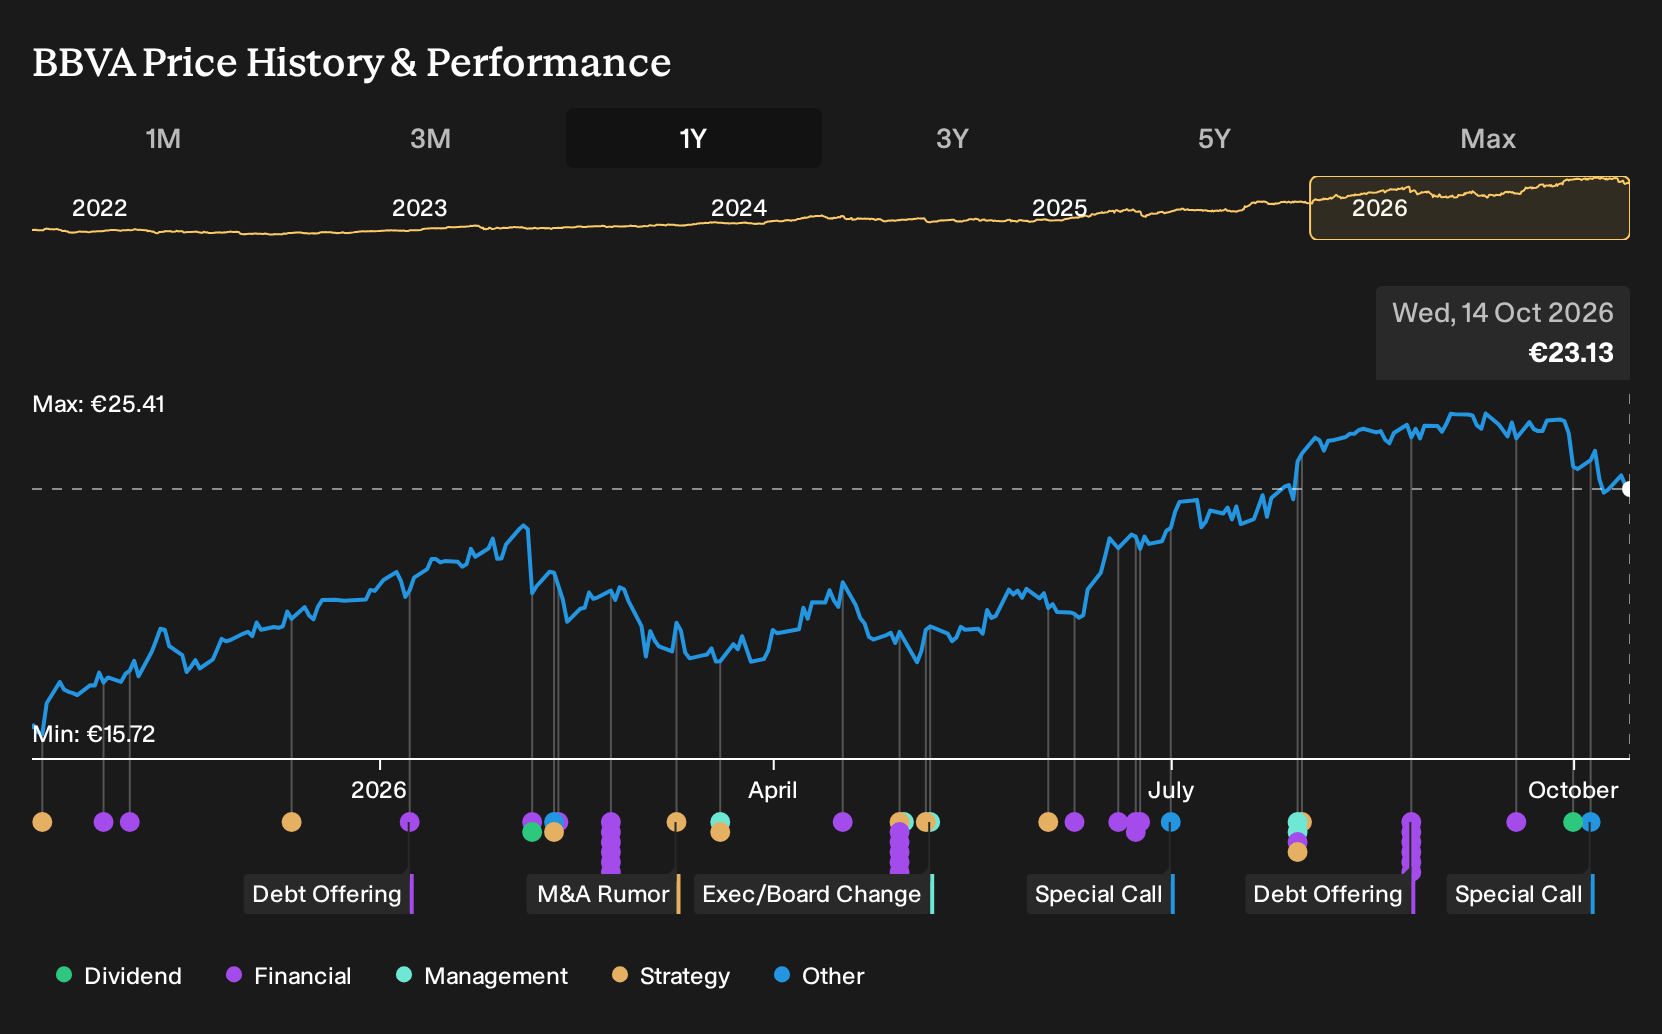
If you had bought Banco Bilbao Vizcaya Argentaria on 14 October 2025 and simply sat tight, the outcome was striking. Investors who held Banco Bilbao Vizcaya Argentaria over the past year are up 54.6%, including dividends. That move now sits alongside fresh headlines about strong Q1 2026 profits, share buybacks, and a high profile court case. If you were making that call back then, which mattered more: Latin American digital growth, or emerging market and legal risk?
The useful thing about a Narrative is that the reasoning is checkable: the assumptions sit beside the argument, and together they imply an estimated Fair Value you can disagree with.
If the move has made Banco Bilbao Vizcaya Argentaria harder to judge, start where the gap is still open and scan 192 high quality undervalued stocks.
The Two Stories Investors Had To Choose Between On Banco Bilbao Vizcaya Argentaria
The shares cost €15.98 at the start of the period, and investors in Banco Bilbao Vizcaya Argentaria were pulled between two clear storylines about what might come next.
The bullish narrative pointed to a fair value of €18.50, framed around Latin American middle class banking and digital channels. Supporters leaned on assumptions of revenue growth at 10.4% a year and profit margins at 30.5%, with the bank eventually trading on a future P/E of 10.9x.
The bearish view argued for a fair value of €12.38 and focused on digital disruption and emerging market risk. That camp assumed revenue growth of 7.0%, profit margins narrowing to 25.1%, and a lower future P/E of 9.7x if fintech rivals and regulatory costs bit harder than hoped.
What The Results Changed For The Banco Bilbao Vizcaya Argentaria Story
BBVA’s Q2 2026 figures gave the bullish case fresh support. Revenue moved from €7,549m to €9,073m and net income from €2,749m to €3,062m, while the net margin slipped from 36.4% to 33.7%. That mix of higher sales and profit, but softer profitability, meant the evidence cut both ways for the original growth versus risk debate.
The lesson is clear. When a bank like Banco Bilbao Vizcaya Argentaria is presented as a margin-resilient story, it is important to track both net income and net margin, not just whether revenue climbs.
What BBVA’s One Year Run Already Prices In
After a 54.6% gain over the past year, Banco Bilbao Vizcaya Argentaria now trades at €23.13. The selected Narrative argues that its Fair Value sits above the current price, anchored in capital return plans and a push to widen its lead in digital and emerging market banking.
On this view, a buyer today must judge whether BBVA can convert that capital flexibility and technology investment into persistently stronger earnings quality than peers expect.
"BBVA is positioned for profit outperformance through market share gains in lending, strong capital flexibility, and rapid digital transformation that could support operational efficiencies. Its leadership in emerging markets and innovation in sustainable finance are seen as potential drivers of long-term revenue and earnings quality."
The price and this Narrative do not agree. → Uncover what this Narrative says Banco Bilbao Vizcaya Argentaria is actually worth
Looking Past BBVA’s Headline Story
Once you have weighed Banco Bilbao Vizcaya Argentaria’s digital push, another question appears. Who helps big corporate clients move, store, and manage that money?
Large institutions still need a bank that connects payments, trading, and advice in one place. One global player leans heavily on that integrated franchise.
It arranges financing for major projects, supports cross border transactions, and processes large payment flows.
That mix can matter when corporate demand centers on technology, security, and infrastructure spending. If BBVA defines one way to play digital banking, this other business frames another angle. The interesting part is how its scale might shape future fee and interest income patterns.
The case is on the record, with the assumptions it rests on. → See the Narrative that values this company 25% above its price
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com