
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Bending Spoons (NASDAQ:BSP) Lands $330 Million Private Placement For 10 Million Shares
- Bending Spoons (NasdaqGS:BSP) agreed a $330 million private placement with Berkshire Hathaway through 10 million new ordinary shares.
- The deal is structured as a binding agreement, bringing Berkshire Hathaway in as a major long term institutional investor.
- The $330 million capital injection increases Bending Spoons' equity base through newly issued shares rather than secondary stock sales.
- This Berkshire Hathaway private placement reshapes Bending Spoons' funding profile and deserves to be weighed against the rest of our view. Our analysis turns up 3 warning signs (2 major) for Bending Spoons as well.
For a broader view on where investor capital may find stronger value than a single software player, explore: 32 high quality undervalued stocks.
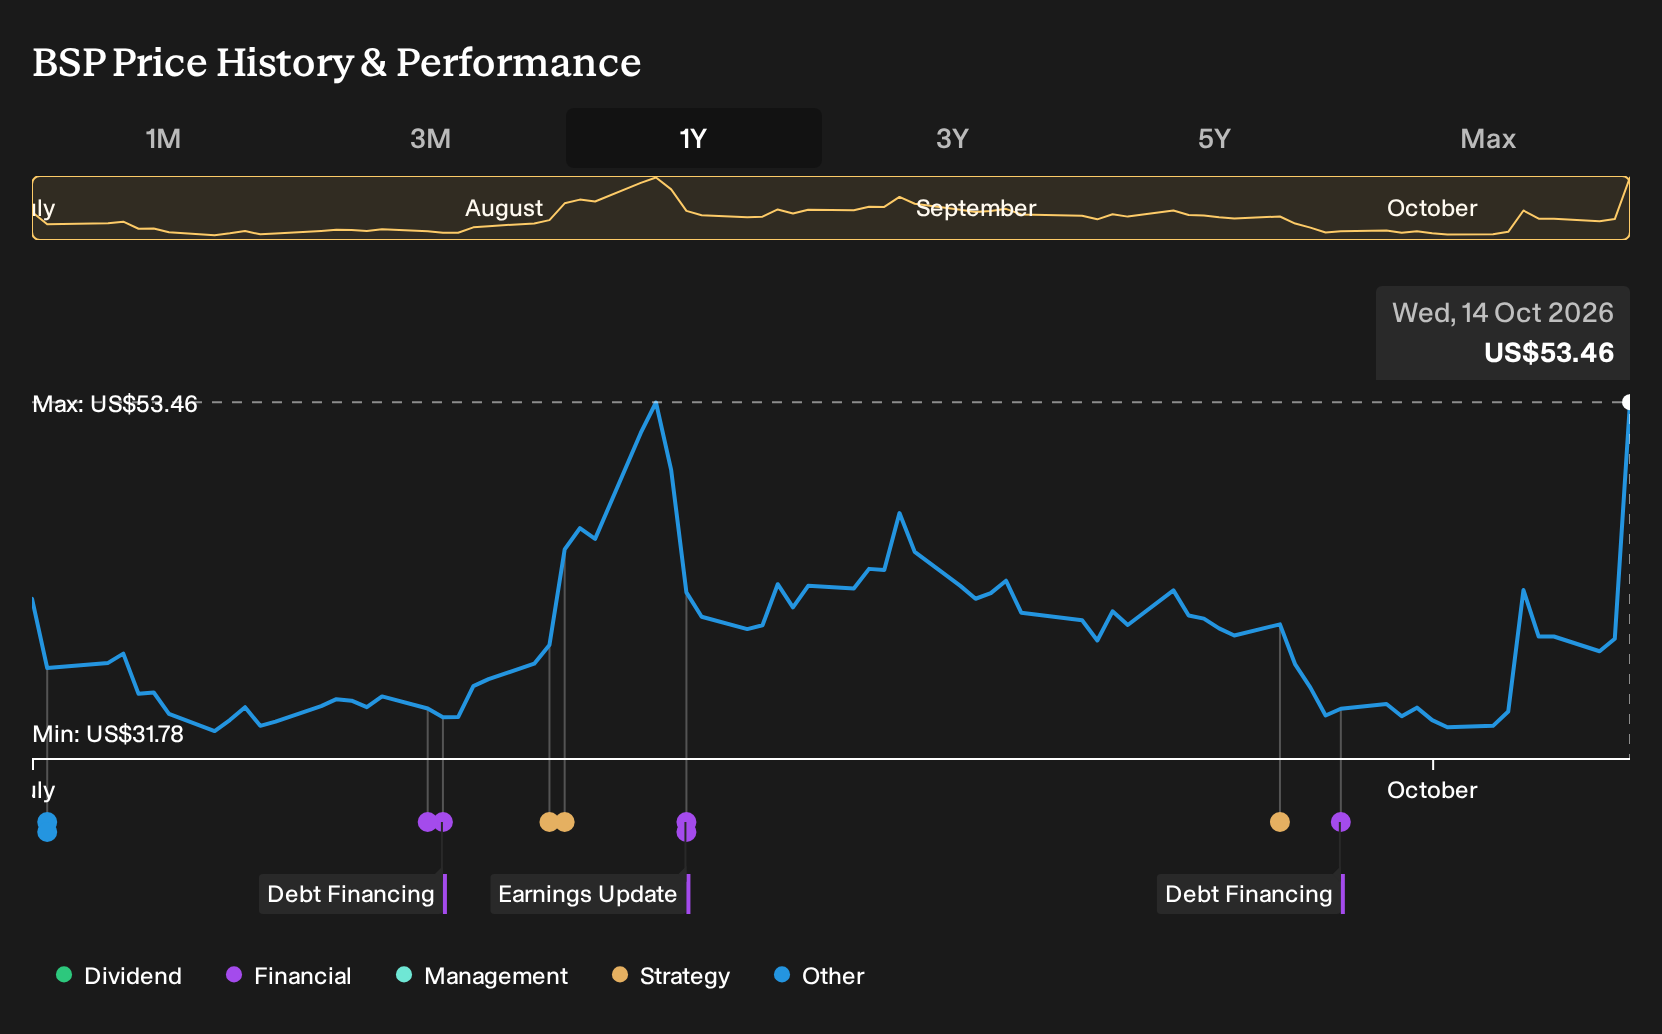
Bending Spoons runs a portfolio model, acquiring and reshaping digital businesses across markets from the US and UK to Japan and Brazil, so a large outside investor is effectively backing its ability to keep finding and integrating new software assets around the world.
See which insiders are buying and selling Bending Spoons following this latest news.
How Berkshire's $330 million move reframes the Bending Spoons Narrative
The Narrative around Bending Spoons is that this is a roll up machine that buys digital assets, reshapes them, then uses the resulting cash flows to fund the next wave of deals. Berkshire Hathaway stepping in with a $330 million private placement plugs directly into that acquisition engine.
"The availability of a large pool of digital businesses that Bending Spoons views as potential targets, combined with expanded access to term loans, revolving credit facilities and IPO proceeds, supports ongoing M&A capacity..."
See how the full story points towards a $48.27 fair value for Bending Spoons.
This Berkshire investment leans into that M&A capacity catalyst. It reinforces the idea that heavyweight capital providers are still prepared to write equity checks into Bending Spoons' acquisition model, not just provide debt. For a software consolidator rubbing shoulders with players like Salesforce or Adobe in certain workflows, that kind of backing can be a useful signal about market confidence in the playbook.
The flip side is dilution and the existing risk around leverage and interest coverage. New shares increase the equity base while previous funding already left analysts flagging that interest payments are not well covered by earnings. If the new capital feeds more deals before existing assets like WeTransfer or Vimeo are fully sweating, that pressure point in the Narrative only grows louder.
The same Berkshire check can read like a vote of confidence or a fresh source of balance sheet strain depending on which side of the Bending Spoons story you believe most.
The next Bending Spoons check before you act on the story
Before you lean too hard on any headline narrative around Bending Spoons, it is worth looking at what our checks suggest about how sturdy the underlying profit figures really are. See what our checks flag about the quality of Bending Spoons's earnings.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com