
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Liquidia (LQDA) Stock Looks Fairly Valued After A Big Run
Liquidia has been on a long winning streak for holders, yet the real question today is whether its current share price is properly supported by the earnings the business can generate. After a volatile stretch in 2026 and a series of legal headlines, the focus has shifted squarely to what the recent moves mean for the stock’s earnings based valuation.
- Over the past 5 years, Liquidia has delivered a very large share price gain, which puts significant pressure on the earnings profile to justify where the stock trades now.
- The recent US$380.7 million settlement with United Therapeutics removes a major legal overhang but also sets a clear cash outflow timetable, which can influence how investors weigh future earnings power against upcoming payments.
- Your read on Liquidia is one view; the desks covering it have another. See what analysts think Liquidia's shares could be worth.
The issue now is whether Liquidia's current market price is supported by its earnings when set against the Fair Ratio benchmark.
If this kind of high stakes legal reset has you rethinking concentration in a single biotech, consider balancing it by scanning for 32 resilient stocks with low risk scores.
Where Does Liquidia Sit on Earnings?
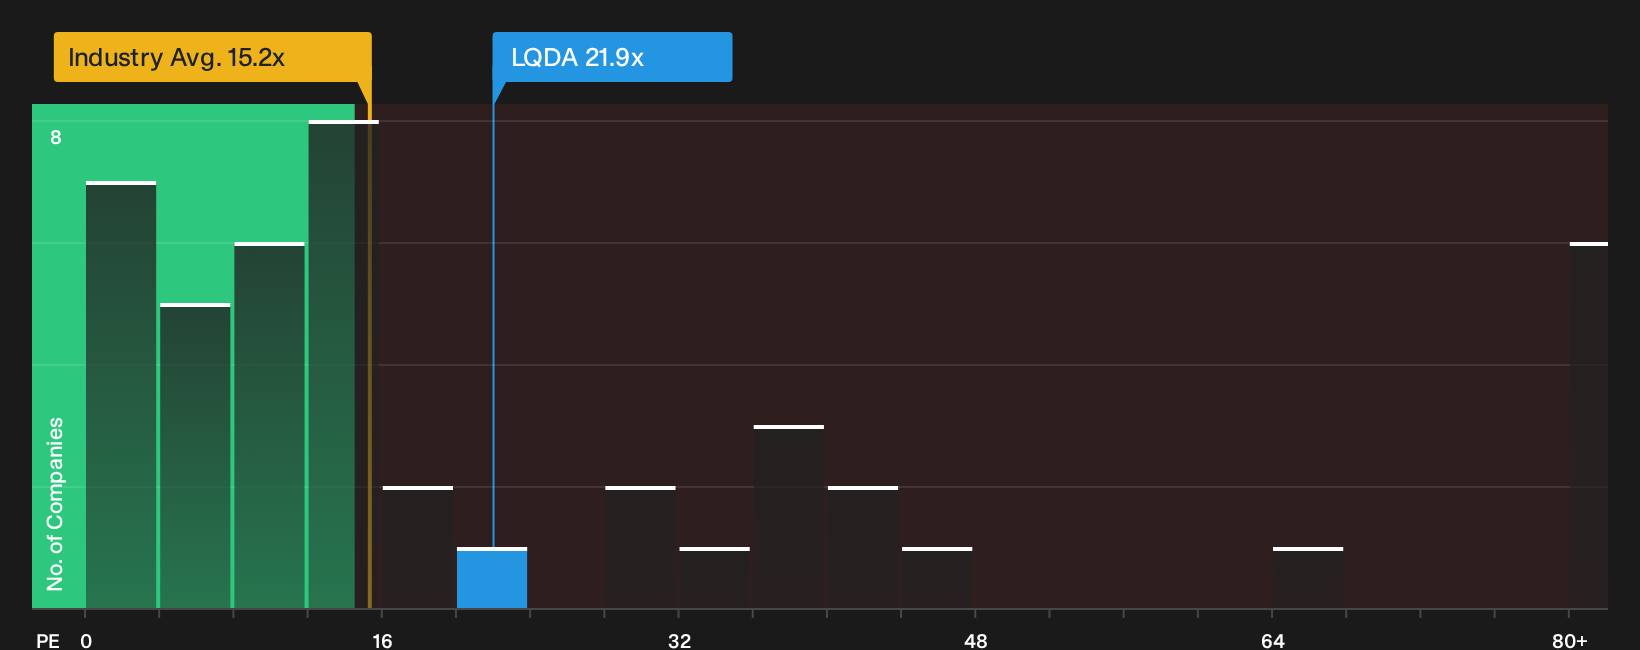
The P/E ratio works well for Liquidia because earnings already play a central role in how the share price is framed. On this lens, the stock trades on a P/E of 21.9x, which sits above the broader Pharmaceuticals sector on 15.2x but below the peer group on 36.1x. That leaves the shares priced richer than the average drug maker, yet not at the very high end of specialist biotech valuations.
The Fair Ratio, which reflects what investors might typically pay for a business with Liquidia's growth profile, margins, size and risk mix, points to a level only slightly above where the shares trade today. This means the current P/E screens about right rather than flashing a clear bargain or bubble. Because the recent US$380.7m settlement cleared a major legal hurdle, the current multiple also suggests investors are already assigning some value to a cleaner path for Yutrepia and the wider pipeline, but without stretching the valuation far beyond the modelled benchmark. Explore the numbers behind Liquidia's P/E valuation.
The Liquidia Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the P/E and Fair Ratio work above leaves off by describing what growth, margin and earnings paths would need to occur for Liquidia to trade materially higher or lower than today’s level. These Narratives appear on the stock’s Community page for anyone who wants to follow that story over time. Rather than providing a single output from a model or ratio, they outline the future scenarios those numbers depend on so you can see whether reality is tracking the assumptions you are using.
One of the top community narratives on Liquidia: 53% undervalued
"Bullish analysts continue to describe Yutrepia as a long term value driver for Liquidia, with prior work referencing a peak sales potential…"
Discover why this Narrative puts Liquidia at 53% undervalued.
One more Liquidia check that belongs beside the earnings math
Price and legal clarity tell only part of the Liquidia story, because the people directing capital allocation and the way they are rewarded can pull outcomes in very different directions. See who runs Liquidia and how they are paid.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com