
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
The Call Entegris Bulls Got Right
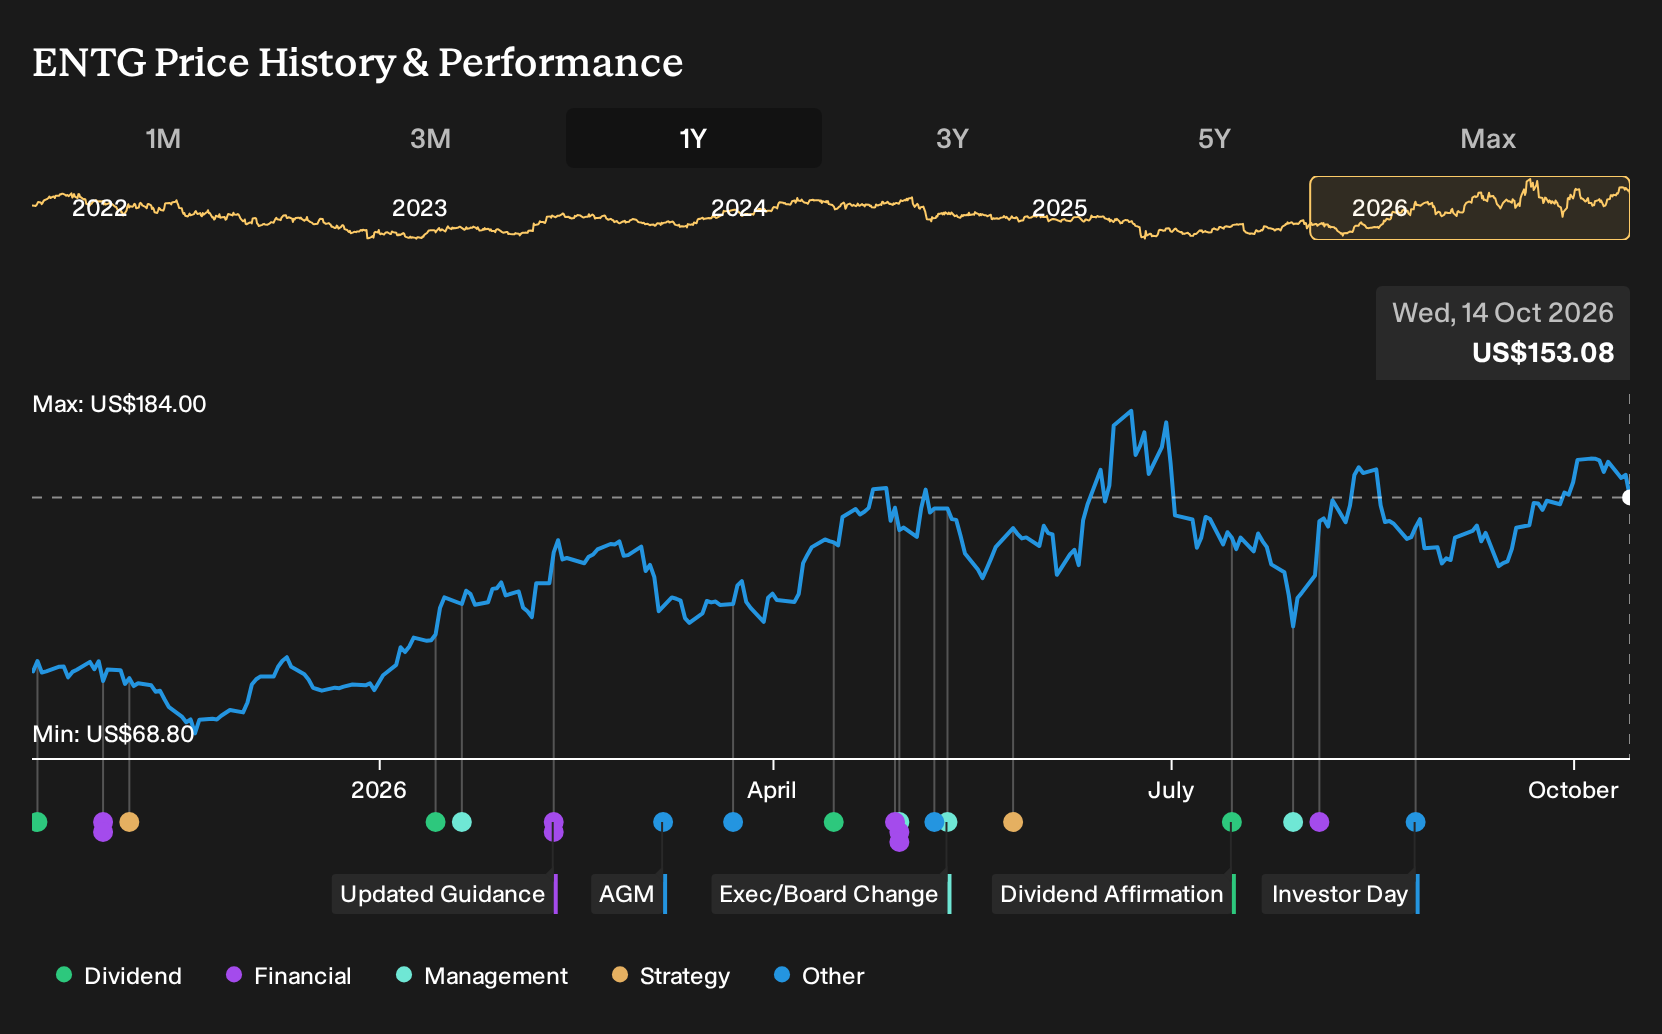
If you had bought Entegris on 14 October 2025, you spent the next year riding a story that swung between AI optimism, tariff anxiety, insider sales, and repeated debates about whether the valuation had run too far. For Entegris shareholders, the return over the past year was 69.7%, including dividends. If that kind of payoff rested on information already on the table back then, what exactly were early buyers weighing up at the start?
This theme extends beyond Entegris. See which of 92 AI infrastructure stocks may still merit a closer look.
The Two Entegris Stories Investors Had To Weigh
The shares cost US$90.94 at the start. Anyone looking at Entegris then had to decide which of two very different stories felt more convincing.
On the upbeat side, the bullish view put Fair Value at US$115, essentially the price implied if its assumptions played out. This view was built on AI and 5G driving multi year demand for Entegris materials, and on expected margin expansion as content per wafer increased.
The cautious camp saw Fair Value at US$85. This view was anchored in worries that tariffs and stricter regulation could lift compliance costs and permanently reduce access to the Chinese market.
What The Results Changed For The Entegris Debate
Entegris then reported Q2 2026 revenue of US$883.2 million versus US$792.4 million a year earlier, and net income rising from US$52.8 million to US$93.6 million as net margin moved from 6.7% to 10.6%. That combination of higher sales and fatter profitability supported the optimistic case about content per wafer and margin potential, although valuation concerns from overvaluation commentary still kept the cautious story alive.
The key assumption tested was not AI hype but whether richer materials content would show up in both top line and profitability. When you look at another chip supplier, check that rising demand claims line up with revenue, and that margin metrics move in the same direction rather than relying only on commentary.
What Entegris’ Run Leaves You Paying For Today
Entegris now trades at US$153, with this selected Narrative arguing that its Fair Value sits above the current price. The focus has shifted from broad AI enthusiasm to questions about whether filtration demand, CMP mix, and manufacturing changes can carry more of the load.
For a buyer today, the key question is whether the market fully credits Entegris with filling its extra capacity while lifting margins and free cash flow.
"Record liquid filtration demand over four consecutive quarters, alongside strong CMP, advanced deposition, and selective etch chemistries, points to Entegris steadily winning higher materials content on advanced logic and memory wafers. This can support faster revenue growth than wafer starts alone."
That disagreement has a full argument behind it. → Uncover the higher Fair Value this Narrative argues for
Where Could You Get There Earlier?
By the time a rally makes headlines, you are reading about returns someone else has already earned. Why not go straight to the source and look for your own contrarian opportunity? These three companies trade below our estimated value.
- Company 1 - 49% below our estimate - targets long-duration e-infrastructure projects backed by contracted recurring work pipelines.
- Company 2 - 33% below our estimate - supplies specialized cloud capacity through large-scale superclusters for intensive AI workloads.
- Company 3 - 48% below our estimate - integrates a regional bank acquisition to broaden deposits, lending activities and fee services.
Three companies from the same screener. Open all 32 potentially undervalued companies →
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com