
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Pinterest (PINS) Could Be 25% Undervalued Following Bearish Options Signals
Bearish options signal meets Pinterest CFO transition
Options activity around Pinterest (PINS) has flashed a bearish signal, with the 10 day call put volume ratio sitting in the top percentile of past readings and raising questions about near term sentiment.
The timing is awkward. Investors are already weighing a 25% year to date decline alongside Pinterest stock’s recent gains as the group prepares for a finance handover and a new Chief Financial Officer steps in.
Short term momentum has picked up for Pinterest, with a 7 day share price return of 7.14% and a 30 day gain of 10.51%. However, the stock is still down 18.07% on a year to date share price basis, and the 1 year total shareholder return has declined 34.71%. This suggests that recent optimism and the incoming CFO are being weighed against a longer period of weaker engagement from investors.
Spot fresh setups by comparing Pinterest with a curated list of social and media platforms inside the 32 high quality undervalued stocks.Recent gains and a new CFO from Amazon have put Pinterest back on radars, yet options traders are leaning negative. Do the current valuation metrics still leave enough upside to justify that risk?
Most Popular Narrative: 25% Undervalued
Pinterest closed at $21.76, while the leading narrative anchors fair value at $29.05 using a 9.0% discount rate and a long term view of earnings power and cash generation.
Ongoing advancements in AI-driven visual search and personalized content curation, supported by proprietary multimodal and generative retrieval models, are deepening user engagement and increasing session times. These developments may contribute to higher average revenue per user and support revenue and margin outcomes over time.
See why 112 investors see Pinterest as 25% undervalued.
Result: Fair Value of $29.05 (UNDERVALUED)
Still, the Pinterest story hinges on closing the international monetization gap and holding advertiser budgets against new rivals like ChatGPT Ads that pursue the same performance dollars.
Find out about the key risks to this Pinterest narrative.
Another View on Pinterest’s Valuation
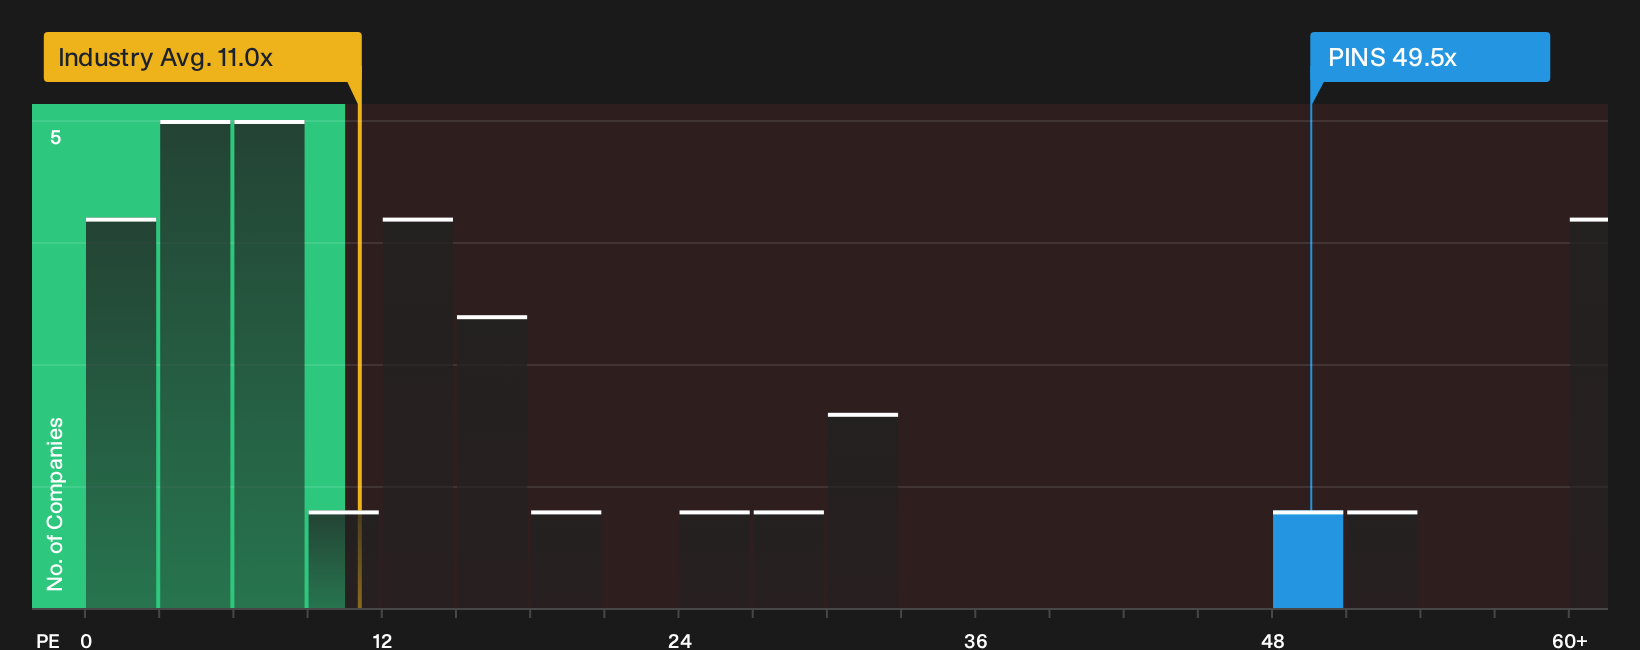
That fair value of $29.05 comes from a narrative tied to future earnings power. The market today is sending a different signal. Pinterest trades on a P/E of 49.5x, compared with 11x for the US Interactive Media and Services group and a fair ratio estimate of 29.1x.
This gap means the stock carries a far richer earnings tag than both peers and the fair ratio that the market could move towards over time. For an investor, that raises a simple question: Is the story strong enough to justify paying well ahead of both the sector and that fair ratio?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages on Pinterest can pull you in both directions, so review the full data set to move quickly and form your own stance with 2 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Pinterest?
Do not stop with Pinterest. Broaden your watchlist now with a few focused idea sets that can surface opportunities you might otherwise miss.
- Target resilient balance sheets by scanning companies on the list of solid balance sheet and fundamentals (25 results).
- Hunt for mispriced opportunities by reviewing the 32 high quality undervalued stocks.
- Prioritize steady income potential by checking out the 7 dividend fortresses.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com