
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Bath & Body Works Stock Gets A New Fragrance Test With Hype Lab
- Bath & Body Works has rolled out Hype Lab, a program that creates small batch, limited edition fragrances based on cultural trends as part of its Consumer First Formula turnaround plan.
- The Hype Lab focus on rapid testing and consumer feedback gives Bath & Body Works a real world lab for refining product development, marketing spend and inventory decisions.
- The next area of focus is how Bath & Body Works’ investment narrative could shift as Hype Lab reframes product creation around real time demand.
Scan beyond Bath & Body Works and size up other consumer-focused stocks testing fresh concepts with our hand-picked 20 high quality undiscovered gems.
Bath & Body Works Investment Narrative Recap
To own Bath & Body Works, you need to believe the Consumer First Formula can turn softer body care and pressured stores into steadier, higher quality demand across channels. Hype Lab and trend driven fragrance drops speak directly to that bet, although the program is small and does not yet change the near term reliance on key franchises and loyalty spend.
The most important near term swing factor is whether weak U.S. and Canada store traffic stabilizes without eroding margins further as mix tilts toward digital and marketplaces. The biggest risk remains soft category performance combined with fixed store and supply chain costs, where lower volume can still pressure the gross profit rate.
Among the recent developments, Hype Lab matters most for that story because it plugs into the Bath & Body Works product engine. Rapid, small batch fragrance testing can help the retailer refine which concepts deserve full scale launches, where to place marketing dollars, and how much inventory to commit before locking in large orders.
That kind of live testing may support the Consumer First Formula by sharpening hero launches while the business leans on Fuel for Growth savings and marketing investment. The risk is that trends caught in Hype Lab fail to offset ongoing declines in body care or underperforming stores, which would leave sales and margin pressures broadly unchanged.
What The Current Bath & Body Works Forecasts Assume
Bath & Body Works now carries an explicit analyst script in the background of the Hype Lab story. Consensus models are built on revenue growing at 1.6% a year over the next three years, profit margins easing from 10.8% today to 9.8% by around 2029, and earnings moving from US$781.0 million now to US$740.2 million in that forecast window, with some estimates as low as US$594.9 million. On those numbers, the stock would trade on an 8.7x P/E in 2029 versus about 4.1x today, a multiple that still sits below the current 16.0x P/E for the wider US specialty retail peer group.
Bath & Body Works' narrative projects US$7.6b revenue and US$740.2 million earnings by 2029. This is built on 1.6% yearly revenue growth and a US$40.8 million earnings decline from US$781.0 million today.
Those assumptions matter for how you think about Hype Lab and the broader Consumer First Formula. Forecasts already bake in some pressure on profitability, with margin compression and lower profit dollars, even as analysts model modest top line expansion and some reduction in share count of roughly 1.5% a year. Hype Lab then effectively becomes a test of whether small batch, trend led product cycles, faster digital experimentation and more disciplined capital allocation can work within, or potentially improve on, that earnings path investors are currently using as a reference point.
On valuation, the gap between market pricing and analyst targets is clear. With a consensus target of US$24.06 against a current share price of US$16.06 as of October 2026, the implied upside on those models is 33.3%, bracketed by a wide spread of individual views that range from US$17.0 to US$54.0. To line up with that framework, you would need to be comfortable with the idea that by 2029 Bath & Body Works can reach the projected US$7.6b in sales, convert that into US$740.2 million of earnings and command an 8.7x P/E using a discount rate around 11.5%.
Hype Lab does not directly change those headline numbers yet, but it can influence how investors judge the credibility of those inputs. If limited run drops help management decide which concepts to scale, which to kill quickly and where to lean in with marketing dollars, then capital tied up in inventory and underperforming categories could become more flexible. For shareholders, the point is less about each individual fragrance and more about whether this testing ground helps the retailer protect margins while it chases that modeled revenue base in a softer store environment.
Uncover why Bath & Body Works' fair value indicates a 27% potential upside to its current price that could narrow quickly.
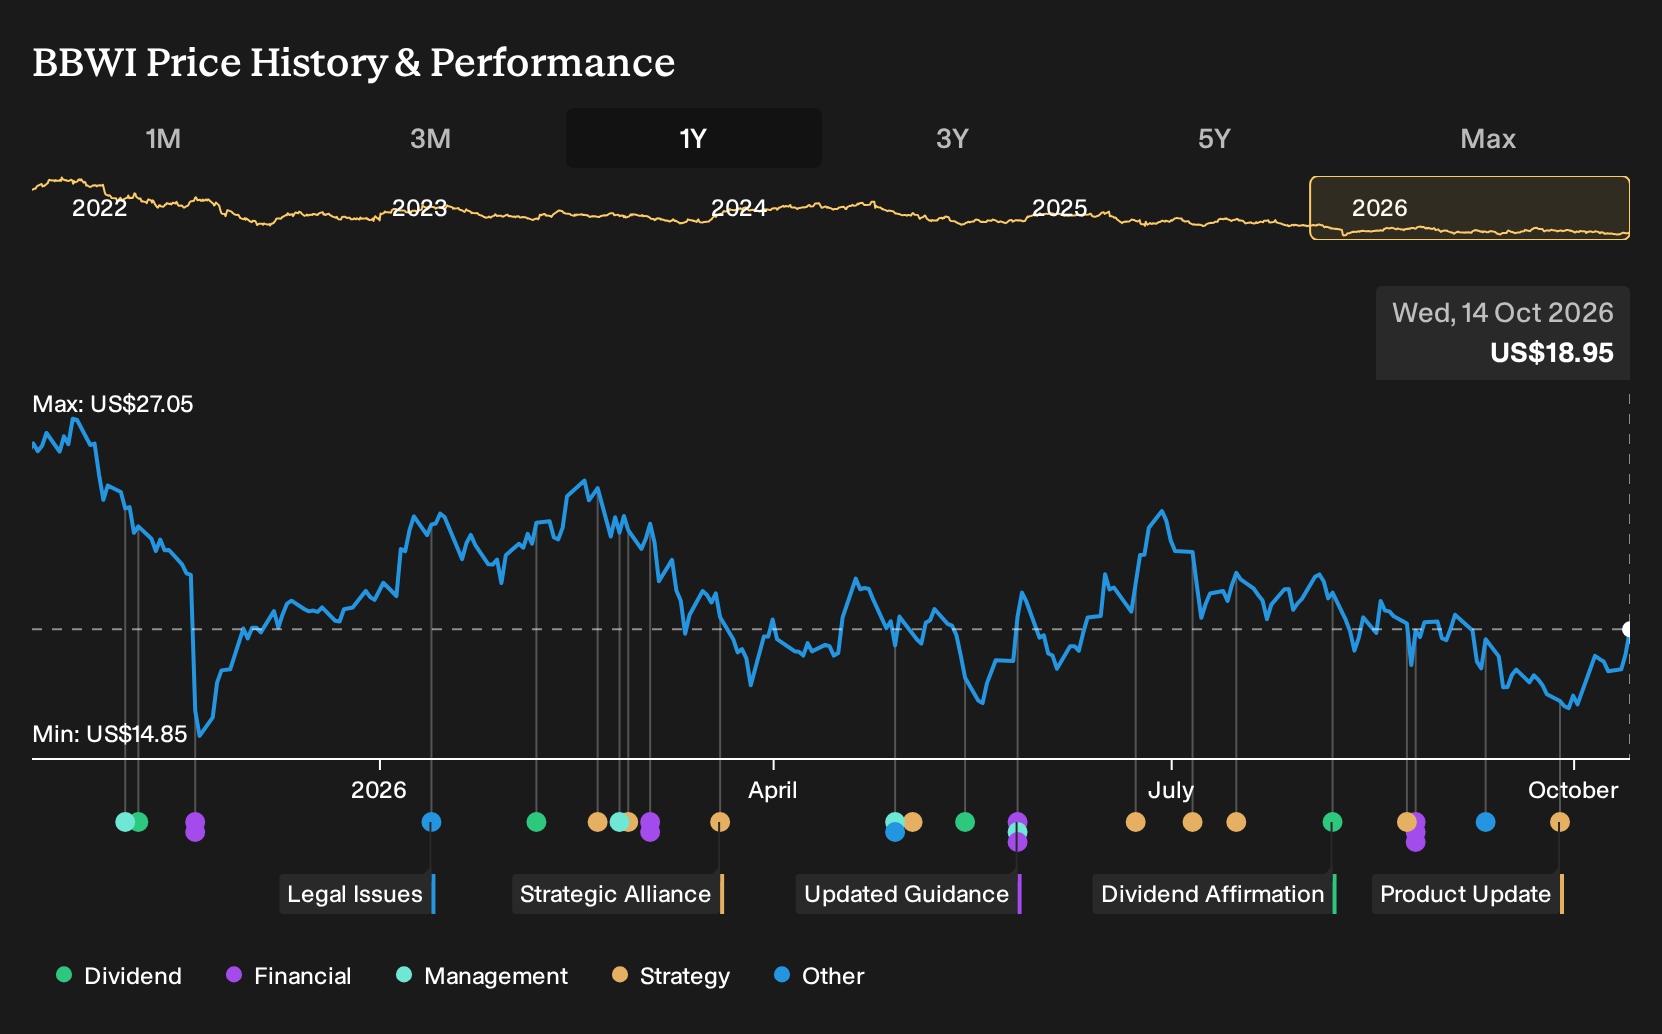
Exploring Other Perspectives
Some bullish analysts frame Hype Lab as a potential accelerator for Bath & Body Works on top of what they already expected. Before this news, the most optimistic projections still pointed to earnings of about US$747.6 million on roughly US$7.6b revenue by 2029, with a much higher P/E. Those estimates reflect a far more upbeat story than consensus, and you can use that spread in views to test your own thesis as fresh data from Hype Lab arrives.
Explore 5 other Bath & Body Works fair value estimates, including one that suggests potential upside of as much as 96% from the current price!
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider relying on your own analysis.
- A great starting point for your Bath & Body Works research is our analysis highlighting 2 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Bath & Body Works. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Bath & Body Works' overall financial health at a glance.
Looking For More Investment Ideas Beyond Bath & Body Works?
Once you have a view on Bath & Body Works, it can help to compare that thesis with other listed businesses that share some of the qualities you care about, whether that is value, resilience or income.
- If you want potential mispricing on your side, start with companies that combine quality fundamentals with attractive prices using our 32 high quality undervalued stocks.
- If capital preservation and steadier profiles matter more to you, filter for companies with stronger balance sheets and healthier fundamentals through the list of solid balance sheet and fundamentals (25 results).
- If income is a key part of your plan, scan for higher yielding payers with more robust profiles by using the 7 dividend fortresses.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com