
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Is Aviva (LSE:AV.) Undervalued On Its Pensions Governance Move?
Aviva (LSE:AV.) has put governance under the microscope after appointing veteran pensions executive Mark Thompson to chair its UK Life and Pensions Independent Governance Committee, placing workplace pension oversight and customer value for money firmly in focus.
Recent trading has been quietly constructive for Aviva. The share price is at £6.96 after a 7 day share price return of 2.78% and a 90 day share price return of 5.58%. The 1 year total shareholder return of 9.69% and very large 5 year total shareholder return of 149.54% point to momentum that has built over time rather than faded.
Surf 4 resilient stocks with low risk scores that echo Aviva's focus on governance and resilient pension economics, so you can compare this insurer's profile with peers that also prioritise robust oversight and balance-sheet strength.Aviva now appears to be a solid pensions and insurance platform delivering strong long term returns. However, the share price at £6.96 after a strong multi year run raises a sharper question: are buyers today paying up or still paying less than the business is worth?
Most Popular Narrative: 1% Overvalued
The most followed narrative values Aviva at £6.93 per share, slightly below the latest £6.96 close. The implied valuation gap is tight but still leans cautious on upside.
Aviva's exposure to the UK's ageing population, persistent demand for retirement solutions, and growing assets in workplace pensions and wealth is presented as a structural benefit. This is associated with increasing premium inflows and long term growth in Assets Under Management and fee income, which in turn is linked to future revenues and operating profit. The shift from public to private responsibility for pensions and health coverage in Aviva's core markets is described as expanding the company's addressable market in wealth, workplace, protection, and health insurance. This is viewed as directly underpinning sustained double digit net flows and supporting long term topline revenue growth.
See why 182 investors see Aviva as 1% overvalued.
Result: Fair Value of £6.93 (OVERVALUED)
Still, Aviva’s heavy tilt toward the UK market and the execution risk around integrating Direct Line could easily upset the current fair value story.
Find out about the key risks to this Aviva narrative.
Another View: SWS DCF Flags Aviva As Undervalued
While the consensus fair value for Aviva sits close to the current £6.96 share price, the SWS DCF model tells a very different story. It places future cash flow value at £13.23 per share, which is 47.4% above where the stock trades today and is labelled as good value.
That kind of gap implies either the cash flow assumptions are too generous or the market is still pricing in heavier risks around UK exposure, integration and capital. The question for you is simple: which side of that valuation divide looks more realistic based on your own expectations?
Look into how the SWS DCF model arrives at its fair value.
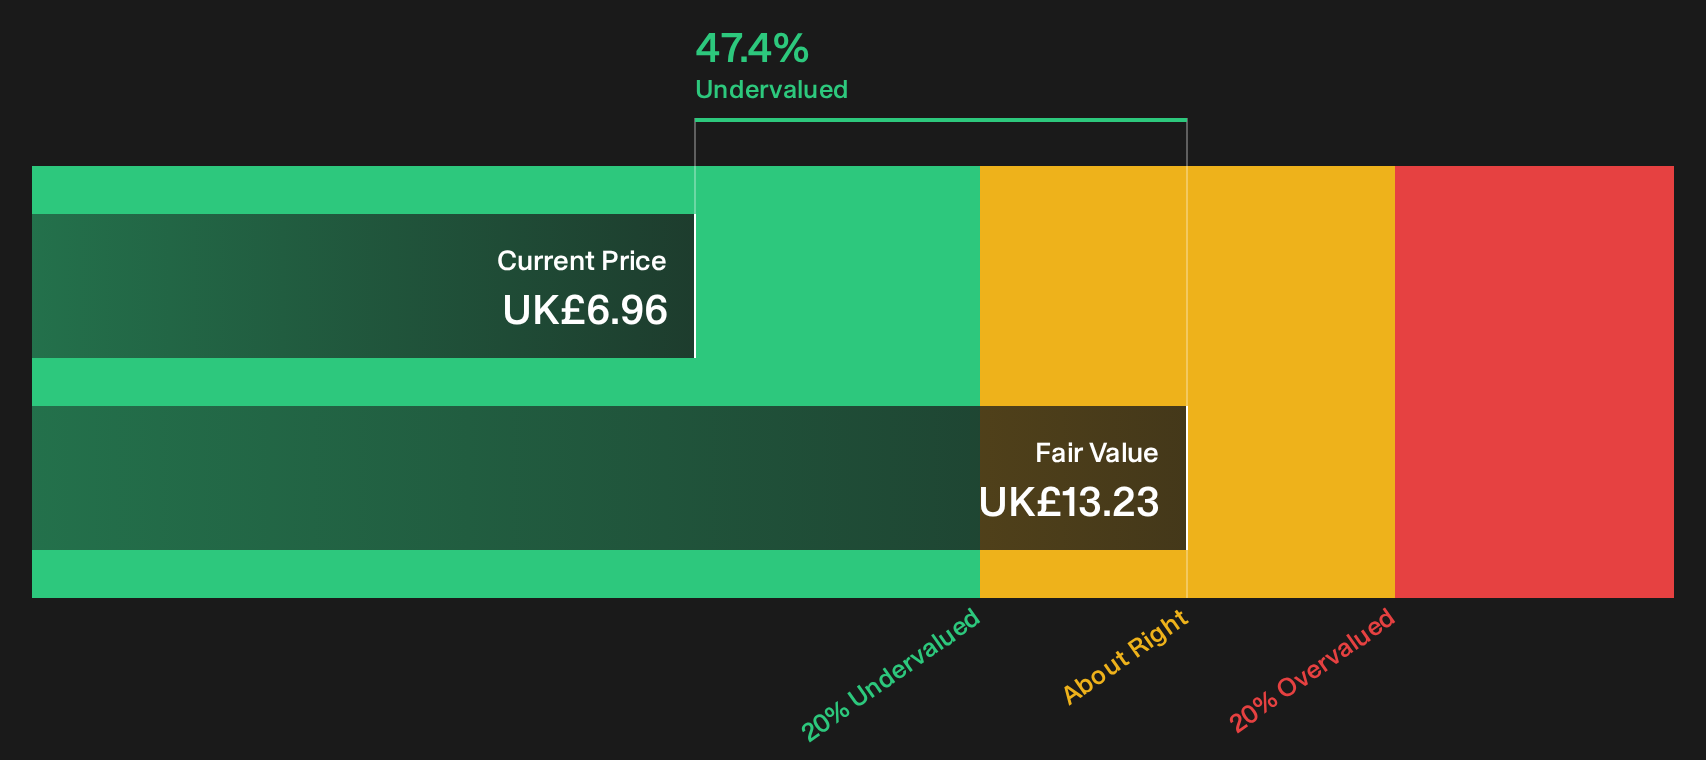
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Aviva for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 8 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals on Aviva's valuation and outlook can be confusing at first glance. Move quickly from headline impressions to your own evidence based view by weighing up the 2 key rewards and 1 important warning sign
Looking for more investment ideas beyond Aviva?
If Aviva has sharpened your appetite for quality, do not stop here. Broaden your watchlist with a few focused stock ideas built from hard numbers, not hype.
- Target resilient income by reviewing 3 dividend fortresses that combine higher yields with balance sheets built to support regular payouts.
- Hunt for mispriced quality using the 5 high quality undiscovered gems that pair strong fundamentals with relatively low market attention.
- Protect your downside first and then your upside by filtering through the list of solid balance sheet and fundamentals (9 results) to stress test the strength behind each ticker.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com