
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
EQT (OM:EQT) Buys Stockbridge, Is The Stock Cheap Or Fully Valued?
EQT (OM:EQT) is back in the headlines after agreeing to acquire Stockbridge, a U.S. real estate investment manager overseeing about US$16.5b in fee-generating assets under management.
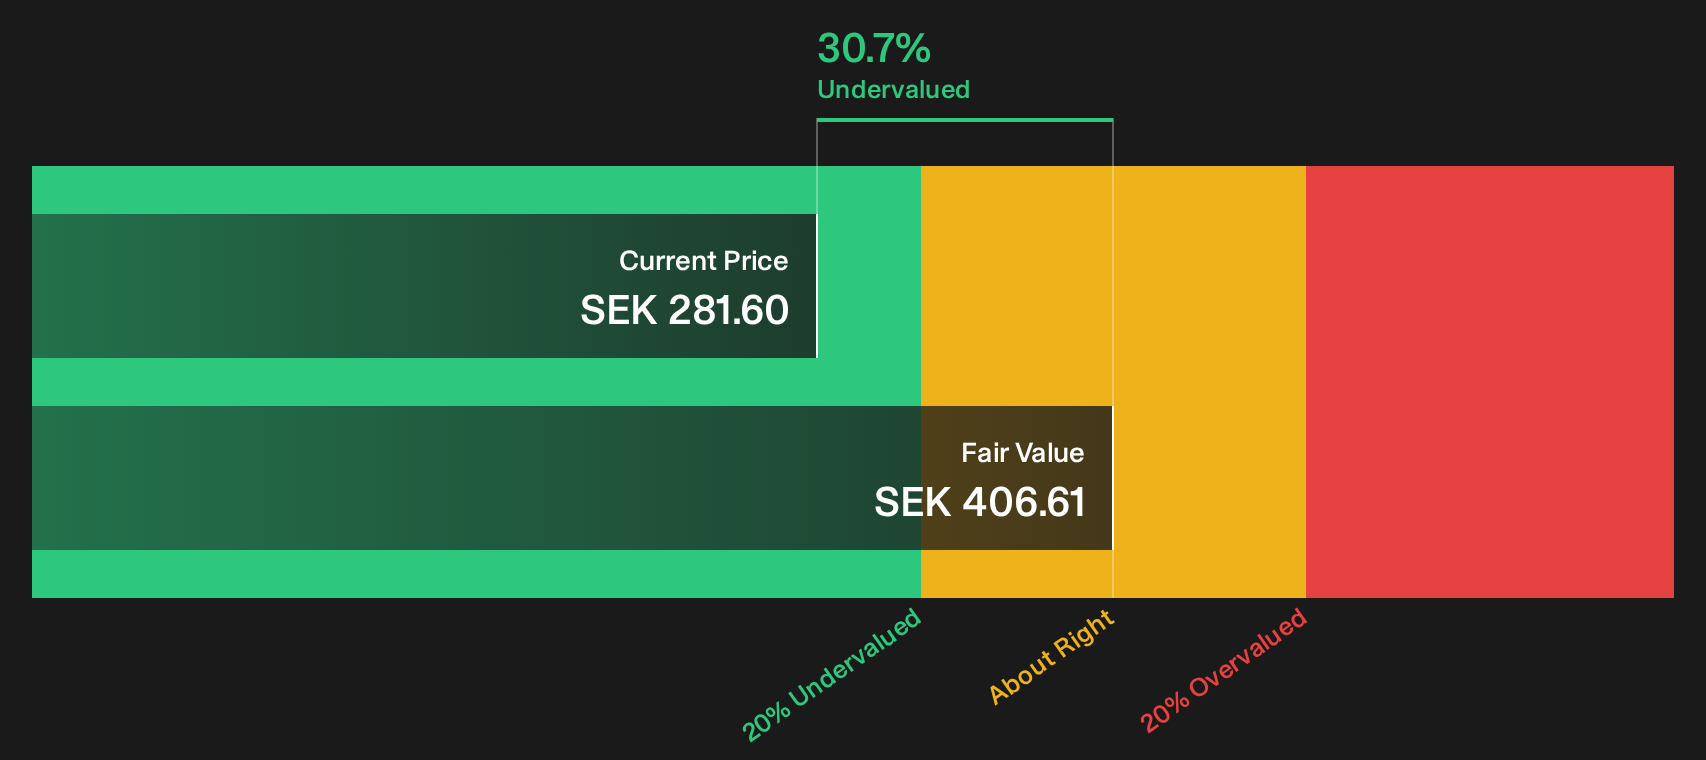
The EQT share price closed at SEK281.6 after slipping 2.73% over the last trading day, capping a tough run that includes an 8.57% decline over 30 days and a 21.38% fall in the year to date. However, the 3 year total shareholder return of 43.27% shows the longer record has been stronger than the recent trend.
Scan how EQT’s latest move fits into the wider hunt for quality alternative asset managers by reviewing the curated 615 high quality undiscovered gems that share similar fundamentals and scale ambitions.
Bulls see EQT using Stockbridge to reinforce a growing real asset platform, while bears focus on sliding recent returns and deal risk. Which story fits the current valuation better?
Most Popular Narrative: 26% Undervalued
Against EQT’s last close at SEK281.6, the most followed narrative points to a fair value of SEK378.68, framing the Stockbridge deal inside a wider platform growth story that analysts think the market is underpricing.
The firm's global diversification, especially its push into fast-growing Asian markets (e.g., India, Japan) and the U.S., positions it to benefit as more capital is funneled into private assets in these regions, supporting sustained AUM growth and higher future earnings.
The development and scaling of evergreen vehicles and private wealth offerings, including potential access to U.S. 401(k) retirement plan flows, create new, high-momentum revenue streams and enhance visibility for long-term fee income growth.
See why 28 investors see EQT as 26% undervalued.
Result: Fair Value of SEK378.68 (UNDERVALUED)
Still, if fundraising momentum stalls or execution on integrations wobbles, the upbeat EQT valuation story could quickly lose credibility.
Find out about the key risks to this EQT narrative.
Another View: What EQT’s Current P/E Is Telling You
The SWS DCF model points to EQT trading below an estimated future cash flow value of SEK406.61, yet the market is pricing the shares on a P/E of 28.2x compared with 16.9x for the Swedish Capital Markets industry and a fair ratio of 24.7x. Is that gap a margin of safety or a sign that expectations already look stretched?
To see how this cash flow view is built step by step, and how sensitive it is to the assumptions used, Look into how the SWS DCF model arrives at its fair value.
Next Steps
With sentiment on EQT split between upside potential and real execution risks, it is important to move quickly, review the underlying data, and weigh both sides using the 4 key rewards and 1 important warning sign.
Looking for more EQT-sized investment ideas?
If EQT has your attention, do not stop at one ticker. Put the same scrutiny to work across fresh ideas so you are not relying on a single bet.
- Target resilient balance sheets and steady fundamentals by reviewing a list of solid balance sheet and fundamentals (203 results) that can help anchor your portfolio when conditions get choppy.
- Hunt for pricing gaps by scanning a 188 high quality undervalued stocks where quality businesses trade at levels that may not fully reflect their fundamentals.
- Dial down potential volatility by focusing on a 223 resilient stocks with low risk scores that filters for companies with more stable risk profiles.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com