
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
3 Developed Asia Dividend Stocks Worth A Closer Look Now
Asia’s markets are caught between slowing IMF growth projections, war driven energy shocks and choppy bond yields, which is exactly when reliable dividend payers start to matter more. Income focused stocks can sometimes soften the hit when earnings expectations wobble and price swings pick up. This article walks through three high quality dividend stocks exposed to these cross currents and explains why each might deserve a closer look now.
The three dividend stocks covered next are just a sample, since the full screen surfaced 29 more developed Asia companies with similar yield, balance sheet and risk profiles that are not covered in this article. If you want to go straight to the source and identify your own high conviction ideas, head into the High-Quality Dividend Stocks in Developed Asia screener.
Sunlight Real Estate Investment Trust (SEHK:435)
Sunlight Real Estate Investment Trust gives you Hong Kong income exposure that fits the High-Quality Dividend Stocks in Developed Asia theme, with a HK$3.6b market cap and a diversified REIT structure. It earns about HK$358 million from office properties and HK$411 million from retail space.
Sunlight Real Estate Investment Trust offers access to Hong Kong offices and malls with a REIT structure built for regular distributions. This fits a screen focused on established, dividend paying assets in developed Asia. Investors get that income angle but are still exposed to what happens when funding costs and rental demand pull in different directions.
When funding costs and rents start to decouple, the 2 key rewards and 1 important warning sign shows where Sunlight Real Estate Investment Trust’s yield story could either stall or accelerate.

First Pacific (SEHK:142)
First Pacific gives this dividend screen exposure to a Hong Kong based holding group that owns everyday essentials in Southeast Asia, from packaged foods to power and telecoms, backed by sizeable operations that can help smooth income when regional growth becomes less predictable.
First Pacific is an investment holding group headquartered in Hong Kong with a market value of about HK$21 billion, drawing about US$7.6 billion from consumer food products and US$2.9 billion from infrastructure, which together anchor its role in this high quality dividend basket.
"Ongoing digital transformation in Asia is fueling strong performance from PLDT's Maya digital banking arm and data centers, with Maya seeing explosive growth in users and loans, positioning PLDT and First Pacific to capitalize on long-term digital adoption trends, supporting higher future EBITDA and cash flows in their telecom segment."
What happens to First Pacific’s dividend profile if one quiet pressure on group cash generation and funding costs starts to move in the wrong direction?
If that pressure point matters to you, read the full narrative for First Pacific to see how First Pacific’s cash engines, risks and dividend capacity could be pulling in different directions.

Nippon Gas (TSE:8174)
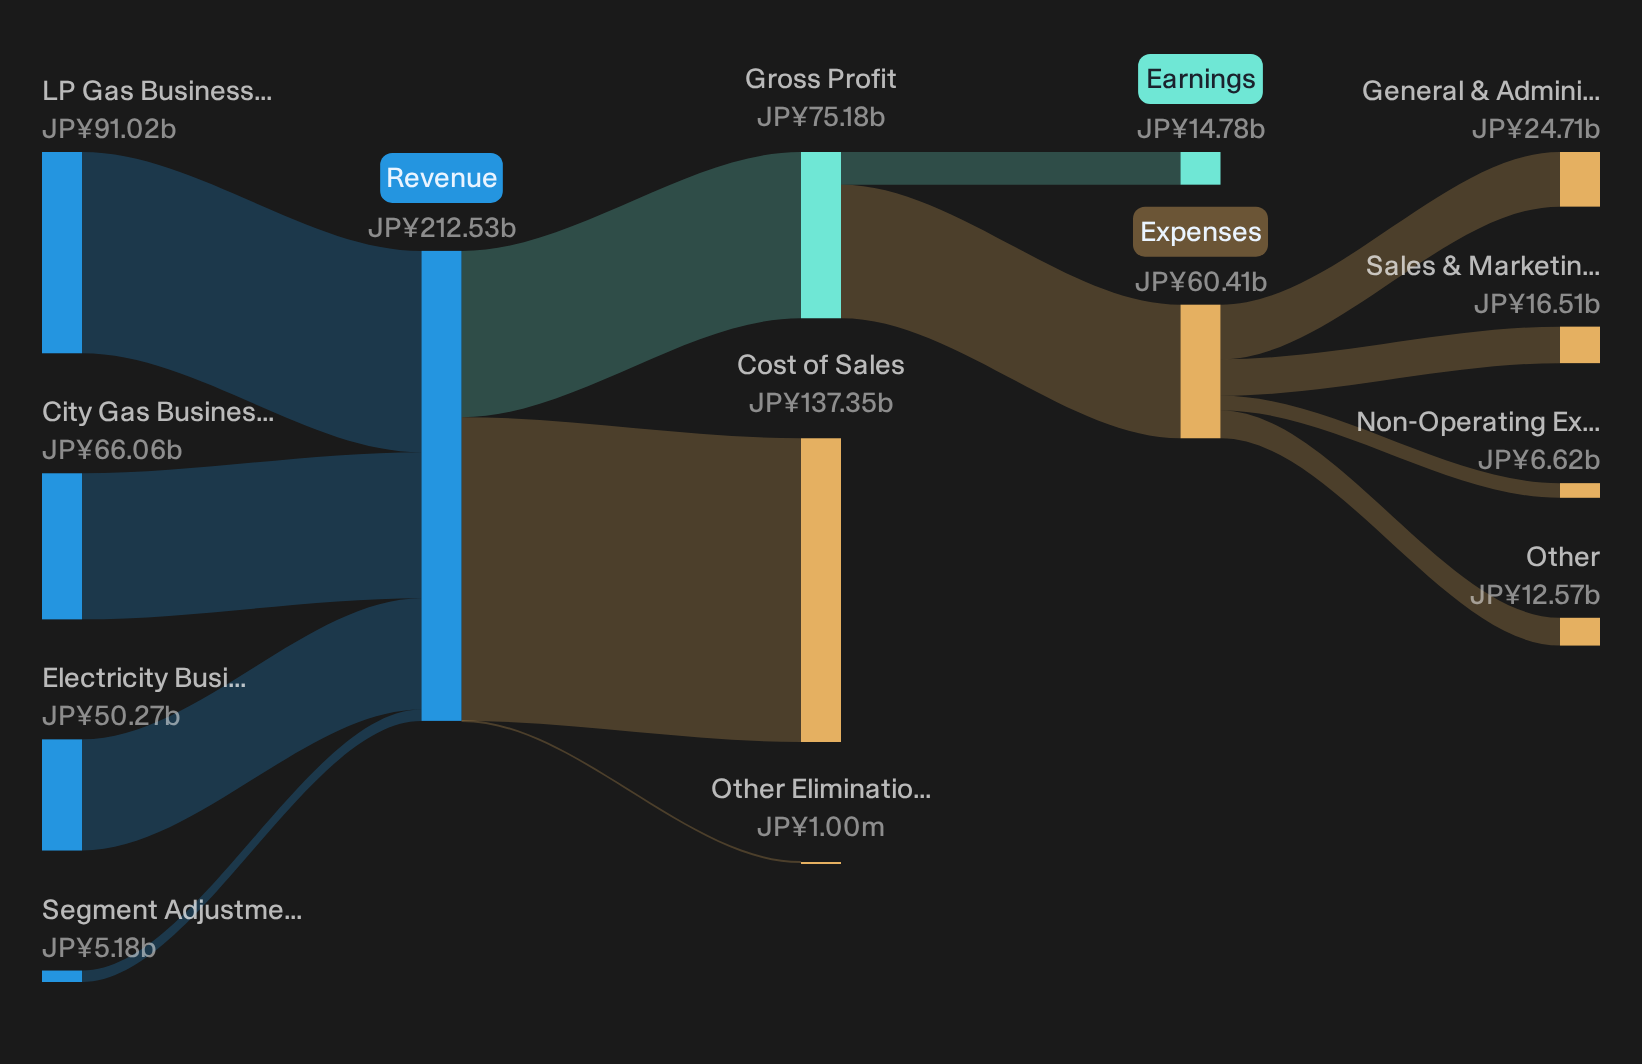
Nippon Gas is a large Tokyo based utility that fits the High-Quality Dividend Stocks in Developed Asia theme by selling essential LP and city gas. It generates about ¥91,017 million from LP Gas, ¥66,063 million from City Gas, ¥50,272 million from Electricity, and has a market value near ¥284.9b.
Nippon Gas provides exposure to a sizeable Japanese utility with essential energy demand, solid ROE and a history of shareholder returns. This aligns with a screen built around income resilience and moderate risk rather than rapid growth. The main watchpoint is the balance between funding costs and payout ambitions when these objectives conflict.
When that funding and payout trade off starts to bite, review the 3 key rewards and 1 important warning sign to see where Nippon Gas income potential may be quietly building or stalling.
Seeking Alternatives Before Momentum Flies Past
Fresh ideas move first, and late money often chases after breakouts once momentum is already flying. Scan these curated lists while it matters and get in early.
- Spot stronger balance sheets before others even glance at the filings by running the list of solid balance sheet and fundamentals (203 results).
- Track early waves in medical AI while they are still under the radar for now through the 129 healthcare AI stocks.
- Position ahead of potential power grid upgrades as electrification accelerates using the 43 power grid technology and infrastructure stocks.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com