
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
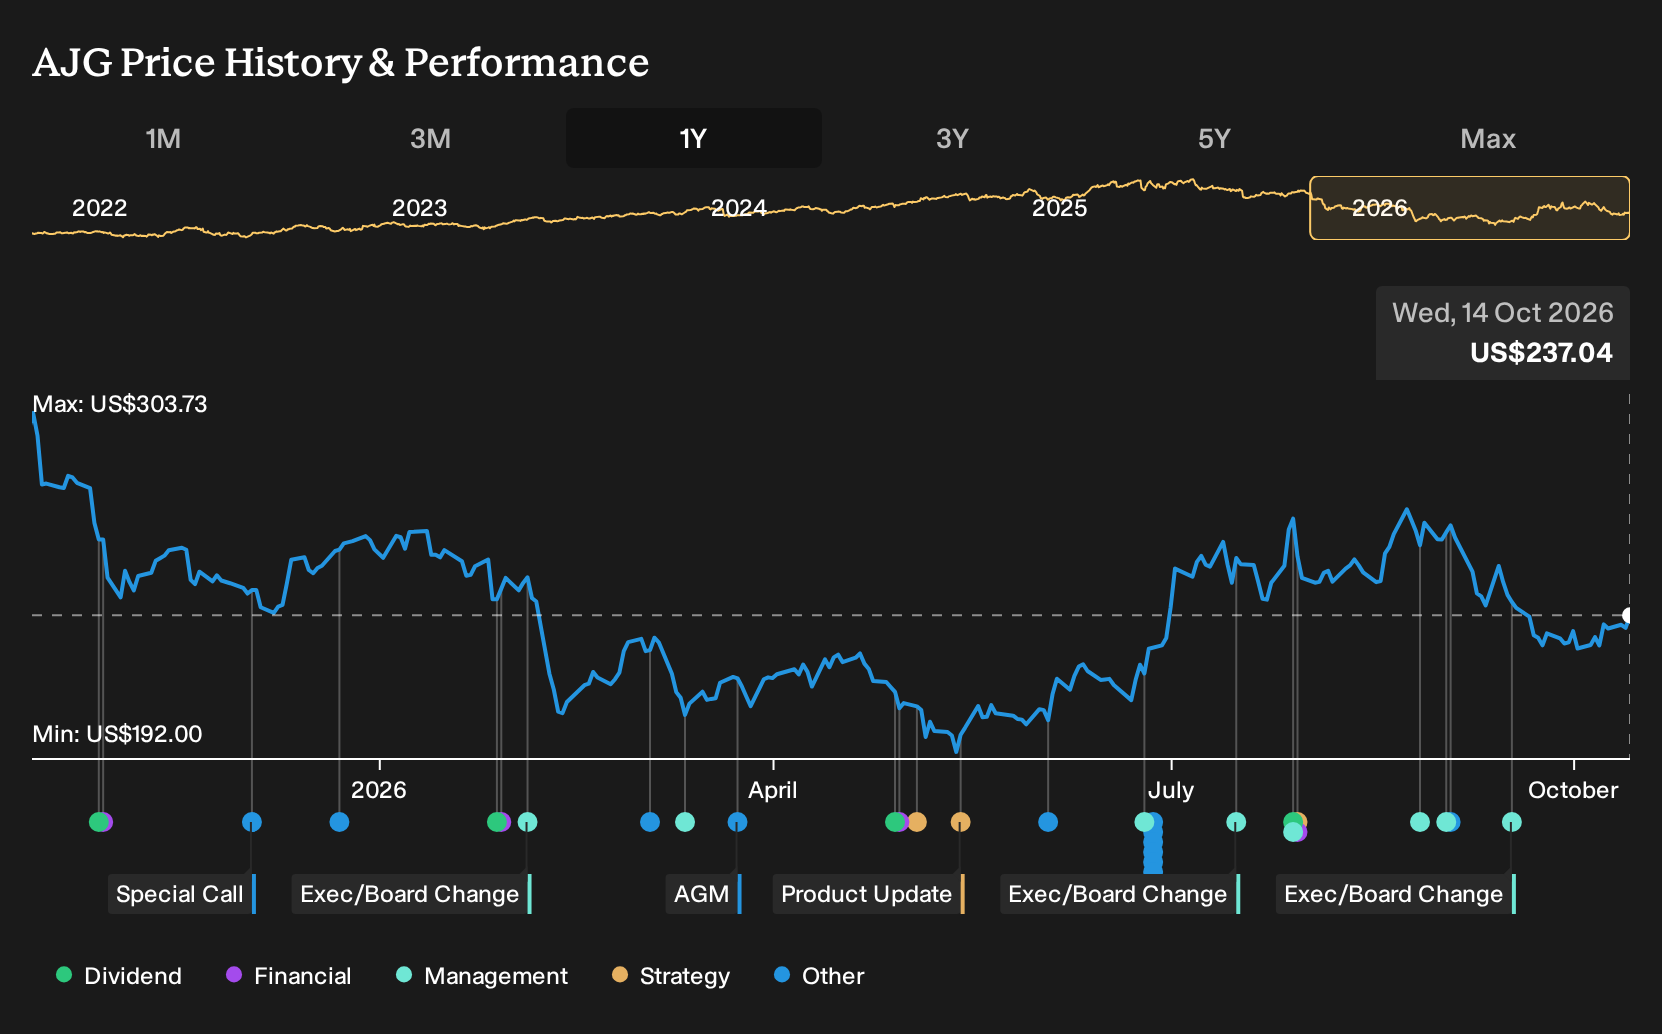
Did Higher Q3 Earnings Forecasts Just Shift Gallagher's (AJG) Investment Narrative?
- Arthur J. Gallagher is heading into its late October 2026 third quarter report with analysts expecting diluted earnings of $3.01 per share, compared with $2.32 a year earlier, following a June quarter that produced $4b in revenue and $323m in net profit.
- The sharper earnings forecast comes even as the brokerage manages softer insurance rate increases, wage pressure and concerns that automation could reshape how its core intermediation model works over time.
- The next area of focus is how Arthur J. Gallagher's investment narrative absorbs these higher earnings expectations against ongoing cost and automation headwinds.
Arthur J. Gallagher Investment Narrative Recap
To own Arthur J. Gallagher, you need to believe the brokerage can keep pairing steady client demand with disciplined cost control while insurance pricing and wage pressure stay in flux. The near term story turns on whether the expected $3.01 in diluted EPS for the third quarter confirms that recent operational noise, including one off items and softer organic growth, is manageable.
The biggest swing factor over the next year is execution on cost savings and workflow automation while property pricing stays less supportive. The main risk is that easing rates in key lines and slower M&A activity squeeze organic fees and delay the margin improvement investors are watching for, without a clear offset from efficiency projects.
One recent development that matters for the Arthur J. Gallagher outlook is the 2026 US Financial Benchmarks report. It highlights employers shifting from simply providing retirement access toward improving employee financial outcomes, using data, plan design and guidance as integrated tools. This lines up closely with the group’s benefits consulting and analytics capabilities.
That focus on financial wellbeing gives the advisory and benefits arm a clear operational runway, especially with more than one third of US employers facing significant health plan premium increases. For investors tracking catalysts, execution in this benefits franchise, together with cost efficiency and M&A integration, will be important for how the stock responds around upcoming earnings.
Arthur J. Gallagher's narrative projects US$20.3b in revenue and US$3.1b in earnings by 2029, based on analysts assuming 10.3% yearly revenue growth and an earnings increase of about US$1.5b from US$1.6b today.
Uncover why Arthur J. Gallagher's fair value indicates a 20% potential upside to its current price before that discount closes.
Exploring Other Perspectives
Some of the most optimistic analysts on Arthur J. Gallagher lean hard into the M&A catalyst. Before this earnings news, they were modelling revenue of about US$21.8b and earnings of roughly US$3.7b by 2029, compared with the US$20.3b and US$3.1b that the baseline view used. Your takeaway should be that expectations differ widely and may shift once the upcoming results land, so treat this report as a chance to compare those narratives and assess which one you consider more realistic.
Explore 3 other Arthur J. Gallagher fair value estimates, including one that suggests there may be as much as 39% upside from the current price!
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so trust your own analysis and judgment.
- A great starting point for your Arthur J. Gallagher research is our analysis highlighting 2 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Arthur J. Gallagher. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Arthur J. Gallagher's overall financial health at a glance.
Looking for more investment ideas beyond Arthur J. Gallagher?
Once you have formed a view on Arthur J. Gallagher, it can help to benchmark that thesis against other opportunities with different risk profiles, income potential and balance sheet strength. The Simply Wall St Screener is built for exactly that kind of comparison.
- If capital preservation ranks high on your list, review a group of 32 resilient stocks with low risk scores that score well on resilience and business stability.
- For readers hunting for quality at a reasonable entry point, scan a curated mix of 32 high quality undervalued stocks that pair solid fundamentals with more modest pricing.
- Income focused investors can target stocks that prioritise cash returns by filtering for 7 dividend fortresses and assessing which yields align with their goals.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com