
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Is SPIE (ENXTPA:SPIE) Below Fair Value Following Its New Ruhr Tech Campus Contract?
SPIE (ENXTPA:SPIE) has secured a five-year technical facility management mandate at the Ruhr Tech Campus Essen in Germany, partnering with Klüh on a project focused on energy efficiency, digital systems, and ESG compliance.
Set against this new Ruhr Tech Campus win, SPIE’s share price tells a mixed story. The stock closed at €41.98, with the 30 day share price return down 3.63% and the 90 day move lower by 11.77%. However, the 3 year total shareholder return of 72.54% and 5 year total shareholder return of 125.75% show that longer term holders have still seen strong value creation.
Scan a curated set of infrastructure and energy transition plays by reviewing the 43 power grid technology and infrastructure stocks that could benefit from the same push toward efficient, digital, ESG-ready facilities as SPIE.
Bulls point to SPIE’s contract wins and recent revenue and net income growth, while bears focus on the share price slide. Which side does the current valuation seem to support next?
Most Popular Narrative: 19% Undervalued
SPIE last traded at €41.98, while the most followed narrative assigns a fair value of €52.00. This frames the current pullback as a potential valuation gap rather than a verdict on the Ruhr Tech Campus contract.
Even though SPIE reports structurally strong cash generation, negative working capital around €800m and access to ESG linked financing including a €600m sustainability linked bond that supports more than €1.5b of liquidity, the continued use of this capacity for extensive M&A and shareholder returns raises the risk that any downturn in acquired activities such as industrial automation or cleanroom services would feed through disproportionately to free cash flow resilience and leverage metrics.
See why 4 investors see SPIE as 19% undervalued.
Result: Fair Value of €52.00 (UNDERVALUED)
Still, if SPIE continues to increase EBITDA margins while using its more than €1.5 billion in liquidity for disciplined deals, that could quickly challenge a cautious valuation gap.
Find out about the key risks to this SPIE narrative.
Another View: SPIE Through The P/E Lens
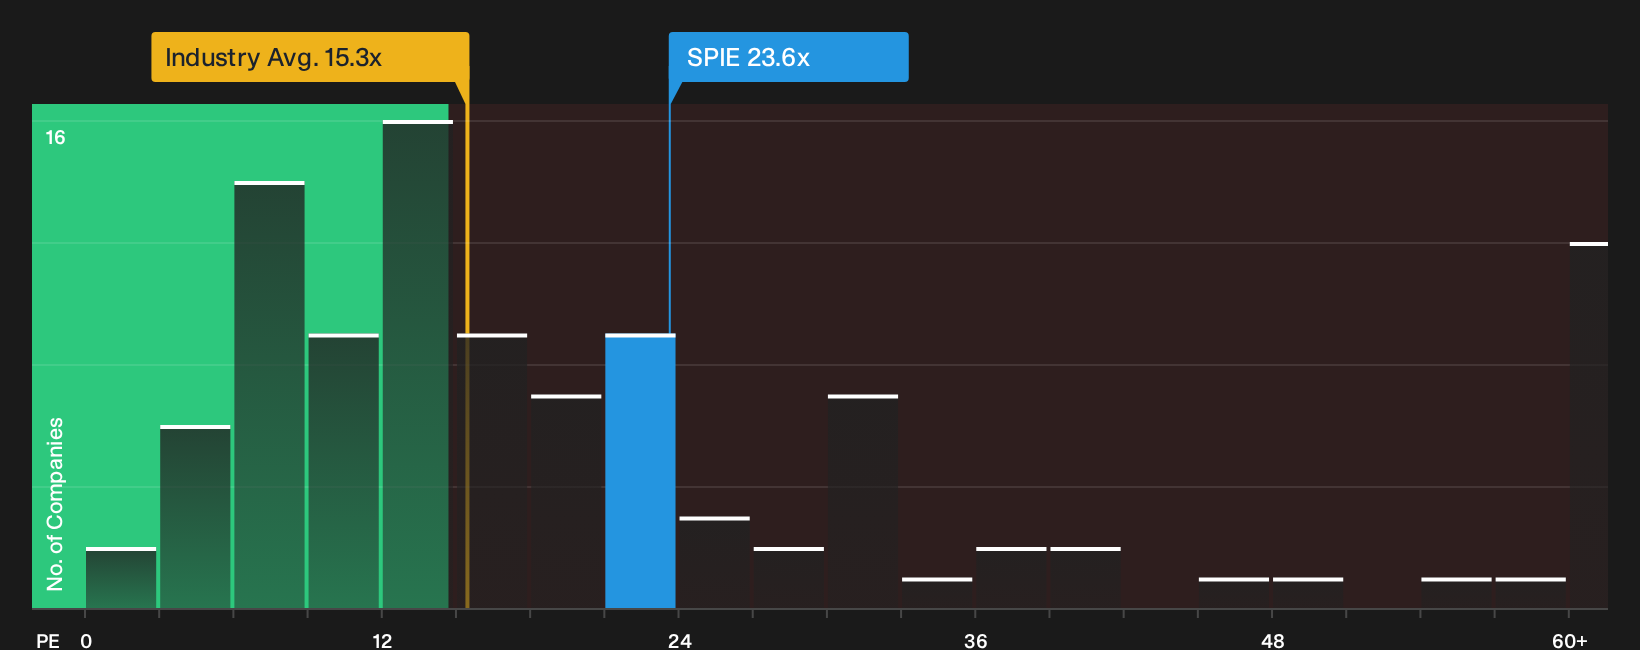
The story shifts when SPIE is viewed through its P/E ratio rather than the €52.00 fair value from the most followed narrative. At 23.6x earnings, the stock trades above the European Commercial Services average of 15.6x and above its own fair ratio of 20.6x, which points to richer pricing on this metric.
If the share price moved closer to that 20.6x fair ratio in line with peers and the wider industry, the upside suggested by the €52.00 fair value could look more limited. Which signal carries more weight for you right now: the discount to fair value or the premium P/E?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages on SPIE can make it tempting to lean on one metric and ignore the rest. However, the faster move is to review the full picture yourself and see how it aligns with your risk tolerance, especially once you weigh the 4 key rewards and 2 important warning signs.
Looking For More Ideas Beyond SPIE?
If SPIE has you thinking harder about pricing power, cash generation, and risk, do not stop at a single ticker. Use the Simply Wall Street Screener to quickly surface other companies that match the kind of profile you want to research next and keep your opportunity set from shrinking to just one stock.
- Target resilient value by scanning a curated set of companies that trade below intrinsic estimates through the 188 high quality undervalued stocks.
- Prioritise capital strength by filtering for businesses with cleaner finances and sturdier funding using the list of solid balance sheet and fundamentals (203 results).
- Hunt for under-the-radar potential by tracking a hand picked group of lesser known stocks with solid fundamentals via the 615 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com