
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
European Value Stocks Priced Below Estimated Worth In October 2026
European equities have experienced volatility recently, influenced by Middle East tensions, a hawkish European Central Bank stance, and mixed economic data from key markets like Germany and France. Despite these challenges, opportunities may exist in the form of undervalued stocks that offer potential value based on their current pricing relative to intrinsic worth. Identifying such stocks involves assessing factors like financial health and market position within the current economic landscape.
Top 10 Undervalued Stocks Based On Cash Flows In Europe
| Name | Current Price | Fair Value (Est) | Discount (Est) |
| Valmet Oyj (HLSE:VALMT) | €27.24 | €53.41 | 49% |
| Sentia (OB:SNTIA) | NOK80.10 | NOK155.57 | 48.5% |
| PORR (WBAG:POS) | €30.95 | €60.75 | 49% |
| Orthex Oyj (HLSE:ORTHEX) | €4.50 | €8.89 | 49.4% |
| Lindab International (OM:LIAB) | SEK127.30 | SEK251.22 | 49.3% |
| ING Groep (ENXTAM:INGA) | €30.08 | €59.70 | 49.6% |
| Huuuge (WSE:HUG) | PLN24.40 | PLN45.81 | 46.7% |
| Freelance.com (ENXTPA:ALFRE) | €2.11 | €3.85 | 45.2% |
| DWS Group GmbH KGaA (XTRA:DWS) | €66.30 | €127.26 | 47.9% |
| Apator (WSE:APT) | PLN25.45 | PLN49.53 | 48.6% |
Let's take a closer look at a couple of our picks from the screened companies.
Comer Industries (BIT:COM)
Overview: Comer Industries S.p.A. specializes in designing and producing engineering systems and mechatronic solutions for power transmission applications across multiple regions, with a market cap of €1.29 billion.
Operations: The company's revenue is derived from two primary segments: Industrial, contributing €633.42 million, and Agricultural, generating €489.35 million.
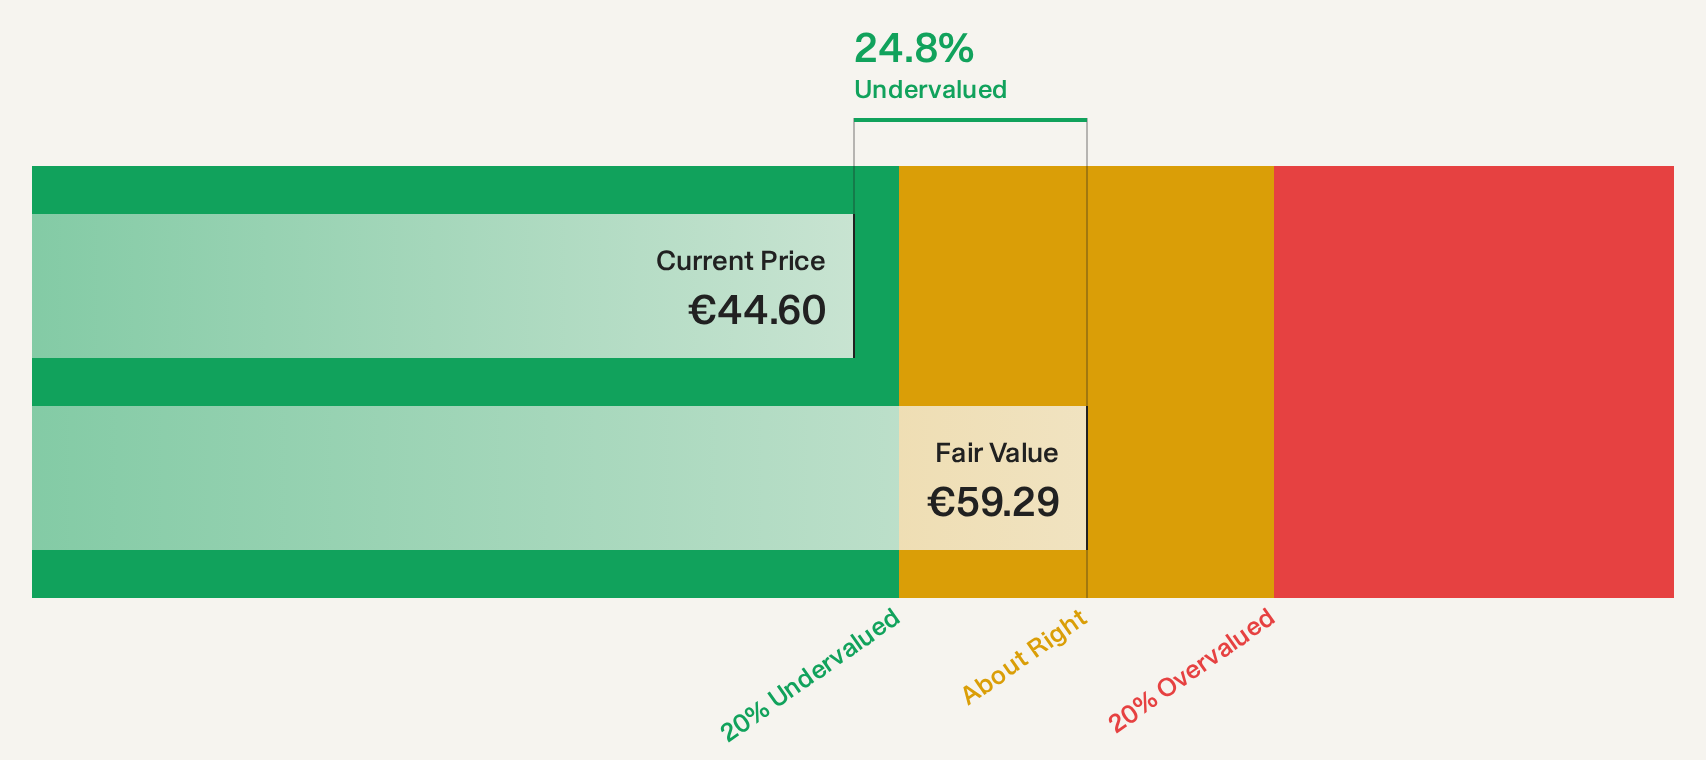
Estimated Discount To Fair Value: 24%
Comer Industries is trading at €44.9, below its estimated future cash flow value of €59.08, indicating it is undervalued by over 20%. Analysts expect a 33.1% stock price increase and forecast earnings to grow at 16.1% annually, outpacing the Italian market's growth rate of 10%. Recent half-year results showed sales of €676.31 million and net income of €41.18 million, reflecting strong financial performance despite an unstable dividend track record.
- Our expertly prepared growth report on Comer Industries implies its future financial outlook may be stronger than recent results.
- Delve into the full analysis health report here for a deeper understanding of Comer Industries.
Sulzer (SWX:SUN)
Overview: Sulzer AG specializes in developing and selling products and services for fluid engineering and chemical processing applications globally, with a market cap of CHF5.83 billion.
Operations: Sulzer AG's revenue is primarily derived from its Flow segment at CHF1.52 billion, followed by Services at CHF1.30 billion, and Chemtech at CHF662.30 million.
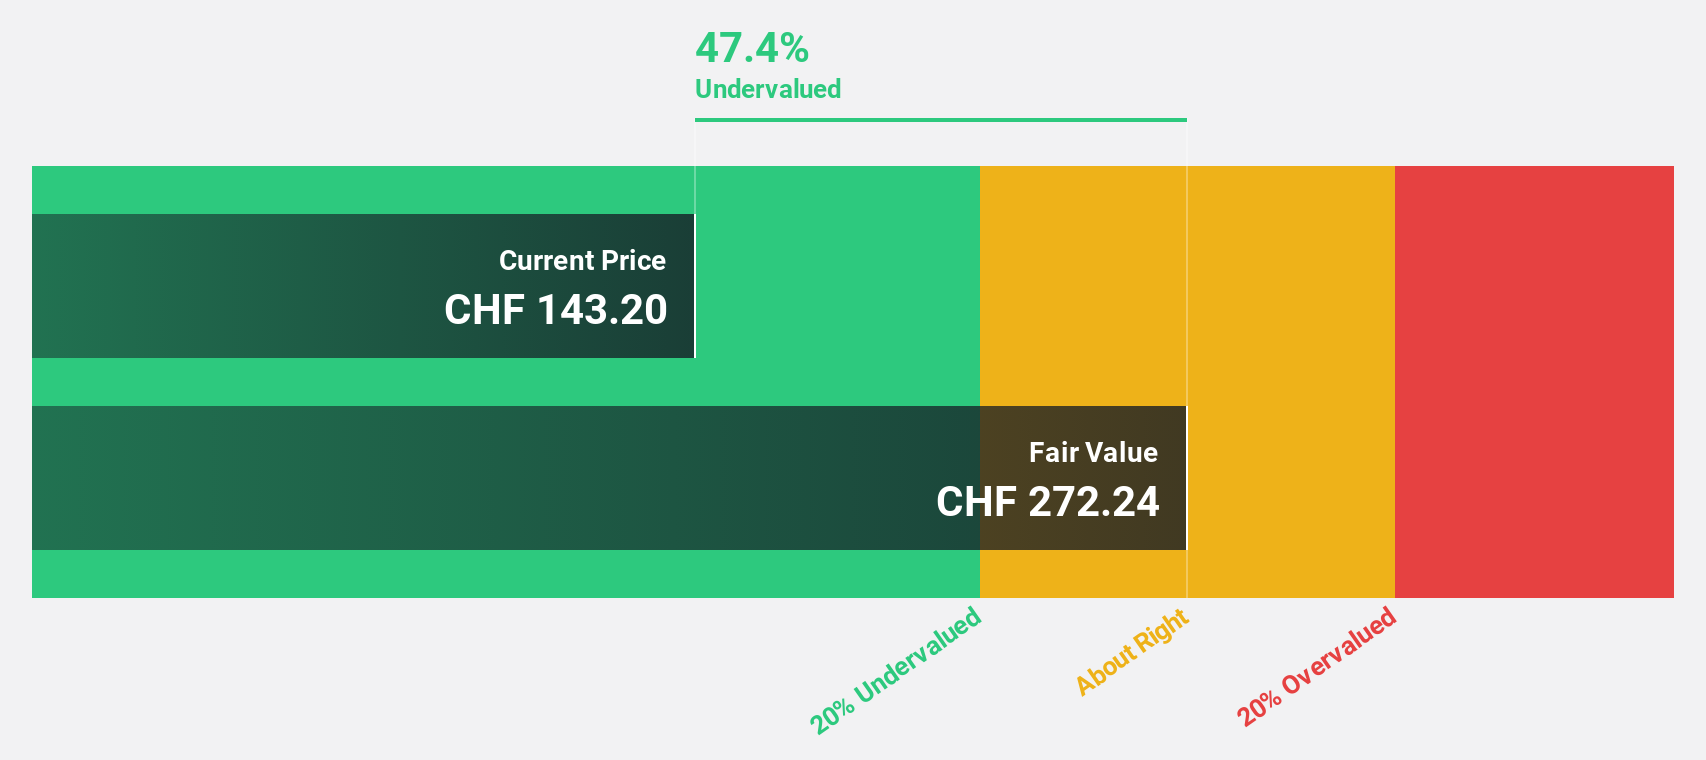
Estimated Discount To Fair Value: 36.7%
Sulzer is trading at CHF 172.1, significantly below its estimated future cash flow value of CHF 271.67, highlighting its undervaluation by over 20%. Despite slower revenue growth projections (3.8% annually) compared to the Swiss market, earnings are expected to grow at a solid rate of 10.22% per year. Recent half-year results showed net income increased to CHF 137.8 million from CHF 127.5 million the previous year, supporting strong financial performance and a reliable dividend yield of 2.76%.
- Insights from our recent growth report point to a promising forecast for Sulzer's business outlook.
- Click to explore a detailed breakdown of our findings in Sulzer's balance sheet health report.
Ypsomed Holding (SWX:YPSN)
Overview: Ypsomed Holding AG, along with its subsidiaries, specializes in the development, manufacturing, and sale of injection and infusion systems for self-medication across Switzerland, Europe, North America, and globally; it has a market cap of CHF 4.83 billion.
Operations: Ypsomed Holding AG's revenue is primarily derived from its Ypsomed Delivery Systems segment, which generated CHF 601.55 million, and its Ypsomed Diabetes Care segment, contributing CHF 75.16 million.
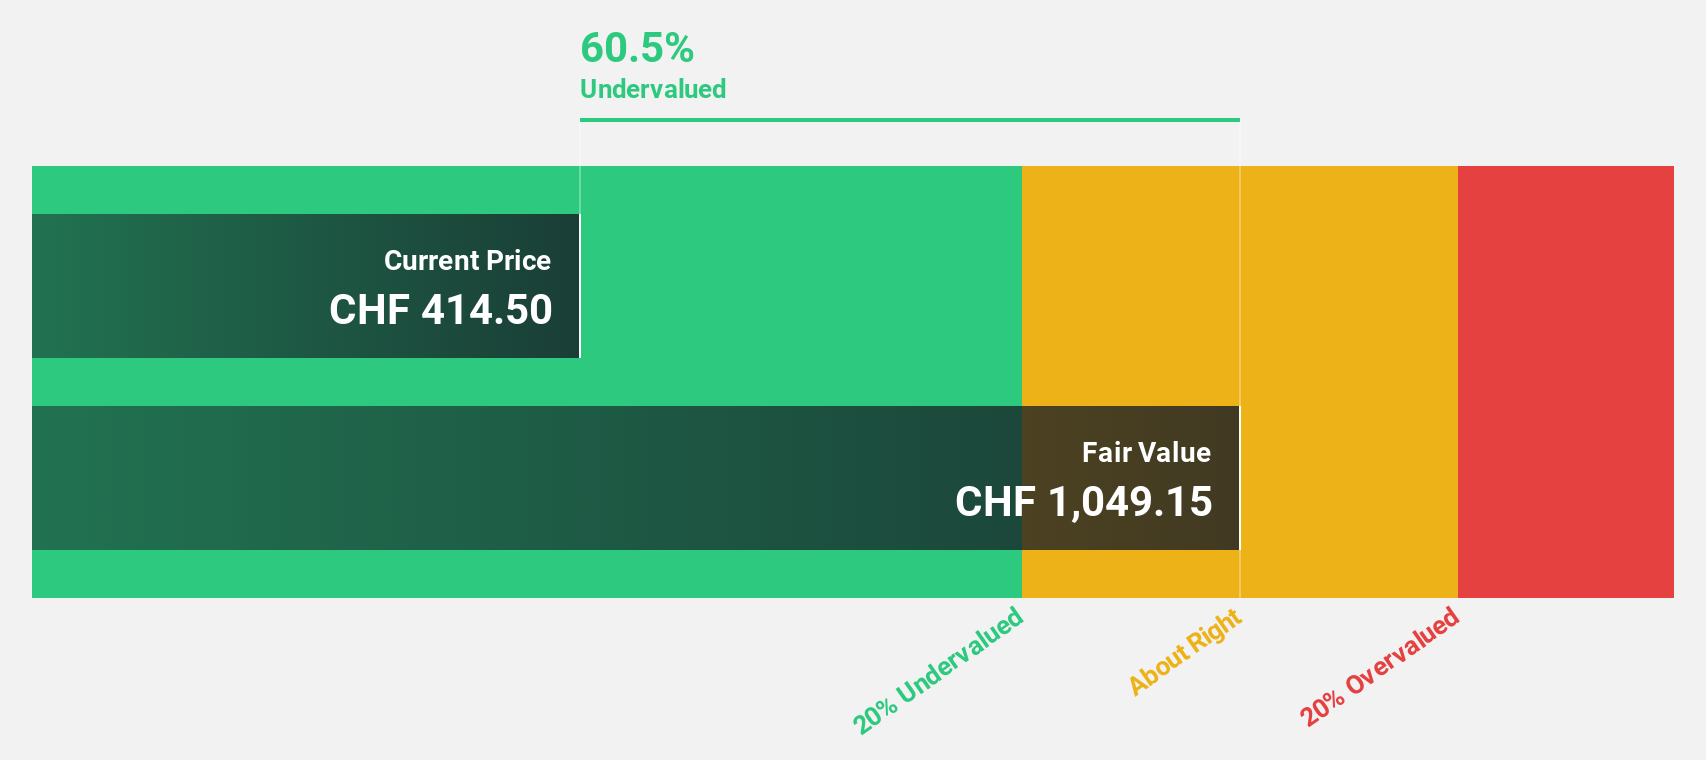
Estimated Discount To Fair Value: 35.3%
Ypsomed Holding is trading at CHF 367.6, well below its estimated future cash flow value of CHF 568.29, indicating significant undervaluation by over 20%. The company anticipates revenue growth of 8.7% annually, surpassing the Swiss market's average. Although earnings are projected to grow slower than the market at 6% per year, Ypsomed's recent expansion into North Carolina with a new facility underscores its commitment to capturing global demand for self-injection systems.
- Our comprehensive growth report raises the possibility that Ypsomed Holding is poised for substantial financial growth.
- Navigate through the intricacies of Ypsomed Holding with our comprehensive financial health report here.
Seize The Opportunity
- Unlock our comprehensive list of 67 Undervalued European Stocks Based On Cash Flows by clicking here.
- Hold shares in these firms? Setup your portfolio in Simply Wall St to seamlessly track your investments and receive personalized updates on your portfolio's performance.
- Streamline your investment strategy with Simply Wall St's app for free and benefit from extensive research on stocks across all corners of the world.
Looking For Alternative Opportunities?
- Explore high-performing small cap companies that haven't yet garnered significant analyst attention.
- Diversify your portfolio with solid dividend payers offering reliable income streams to weather potential market turbulence.
- Fuel your portfolio with companies showing strong growth potential, backed by optimistic outlooks both from analysts and management.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com