
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Missed Usiminas' Rally? Here's What Early Buyers Saw
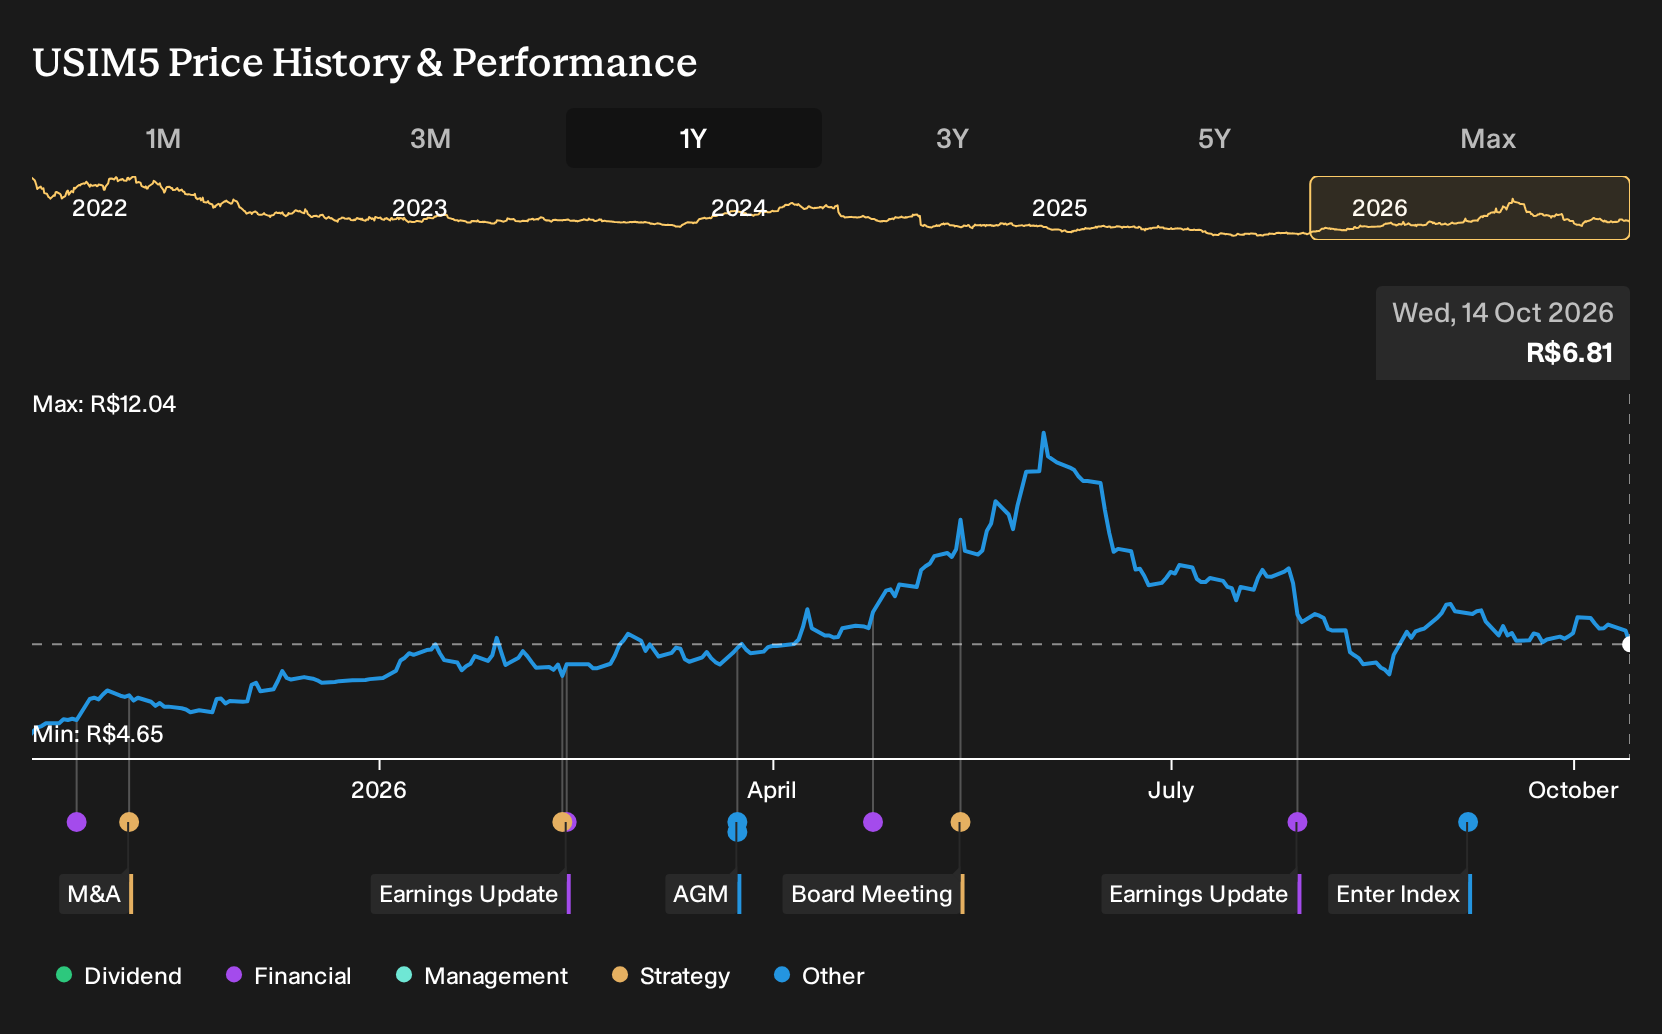
If Usinas Siderúrgicas de Minas Gerais was on your watchlist rather than in your portfolio, the last twelve months may feel like an expensive lesson in hesitation. For Usinas Siderúrgicas de Minas Gerais shareholders, the return over the past year was 42.2%, including dividends. The obvious question is not just why the share price moved, but whether the earlier thesis about digitalization and trade defenses cutting unit costs was visible enough to flag that potential before it showed up in net margin.
The easy part of this move is behind Usinas Siderúrgicas de Minas Gerais. Zero in on 188 high quality undervalued stocks for companies trading below our estimates.
The Two Stories Investors Had To Weigh On Usinas Siderúrgicas de Minas Gerais
The shares cost R$4.65 at the start of the period, so anyone looking at Usinas Siderúrgicas de Minas Gerais then had to pick between two very different stories.
On the optimistic side, the bullish view argued that digitalization and trade defenses would cut unit costs and support a Fair Value of R$5.43. This price was implied by assumptions such as 1.7% annual revenue growth and profit margins reaching 2.2%, with a future P/E of 20.5x.
The cautious camp focused on rising imports and regulatory gaps, arguing for a Fair Value of R$4. That view assumed revenue would fall 1.8% a year and margins would compress toward 1.1%, with earnings still needing a much higher 32.4x future P/E to justify that level.
What The Results Changed For Usinas Siderúrgicas de Minas Gerais
The clearest new data point is profitability. Usinas Siderúrgicas de Minas Gerais reported Q2 2026 net income of R$382.373 million versus R$95.182 million a year earlier, with net margin moving from 1.4% to 6.2% while revenue slipped from R$6,626.381 million to R$6,131.378 million. That pattern supported the optimistic cost-cutting story, although the weaker top line kept the cautious case alive.
The lesson is simple. When a thesis hinges on efficiency, treat net margin and absolute profit as the core test and check whether progress holds up even when sales soften.
What Usinas Siderúrgicas de Minas Gerais' Price Already Assumes
Usinas Siderúrgicas de Minas Gerais now trades at R$6.81 after a 42.2% gain over the past year, and the selected Narrative’s Fair Value sits below that level. That view leans on import pressure, long project timelines and capital intensity as the main constraints on how much of the recent improvement sticks.
The question for you is what must keep going right for that price to hold. A buyer today would need to judge whether higher value steel mix, PCI efficiencies and disciplined capex can all offset import pressure, mining and freight costs, and the cash demand of multi year coke and gasometer projects.
"Even if recent antidumping steps on coated, cold rolled and hot rolled products move ahead, flat steel import penetration at 22% of apparent consumption with increasing exposure to Southeast Asia suggests domestic pricing power and capacity utilization may remain under pressure, which can limit revenue growth and net margin resilience."
That disagreement has a full argument behind it. → Uncover the lower Fair Value this Narrative argues for
Find Your Own Contrarian Opportunity
The story behind this run has already been told. The next one could be taking shape somewhere else. Where could you start looking before it becomes the headline?
- Company 1 - 36% below our estimate - uses multichannel retail investments to emphasize higher margin electronics and appliance categories.
- Company 2 - 50% below our estimate - ramps modular and timber based building systems to streamline complex, long duration housing projects.
- Company 3 - 26% below our estimate - expands the maintenance sales force to secure longer term recurring elevator service contracts.
Those are three of them. See every one of the 203 solid balance sheet companies →
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com