
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
What Alector Bears Saw Before The Fall
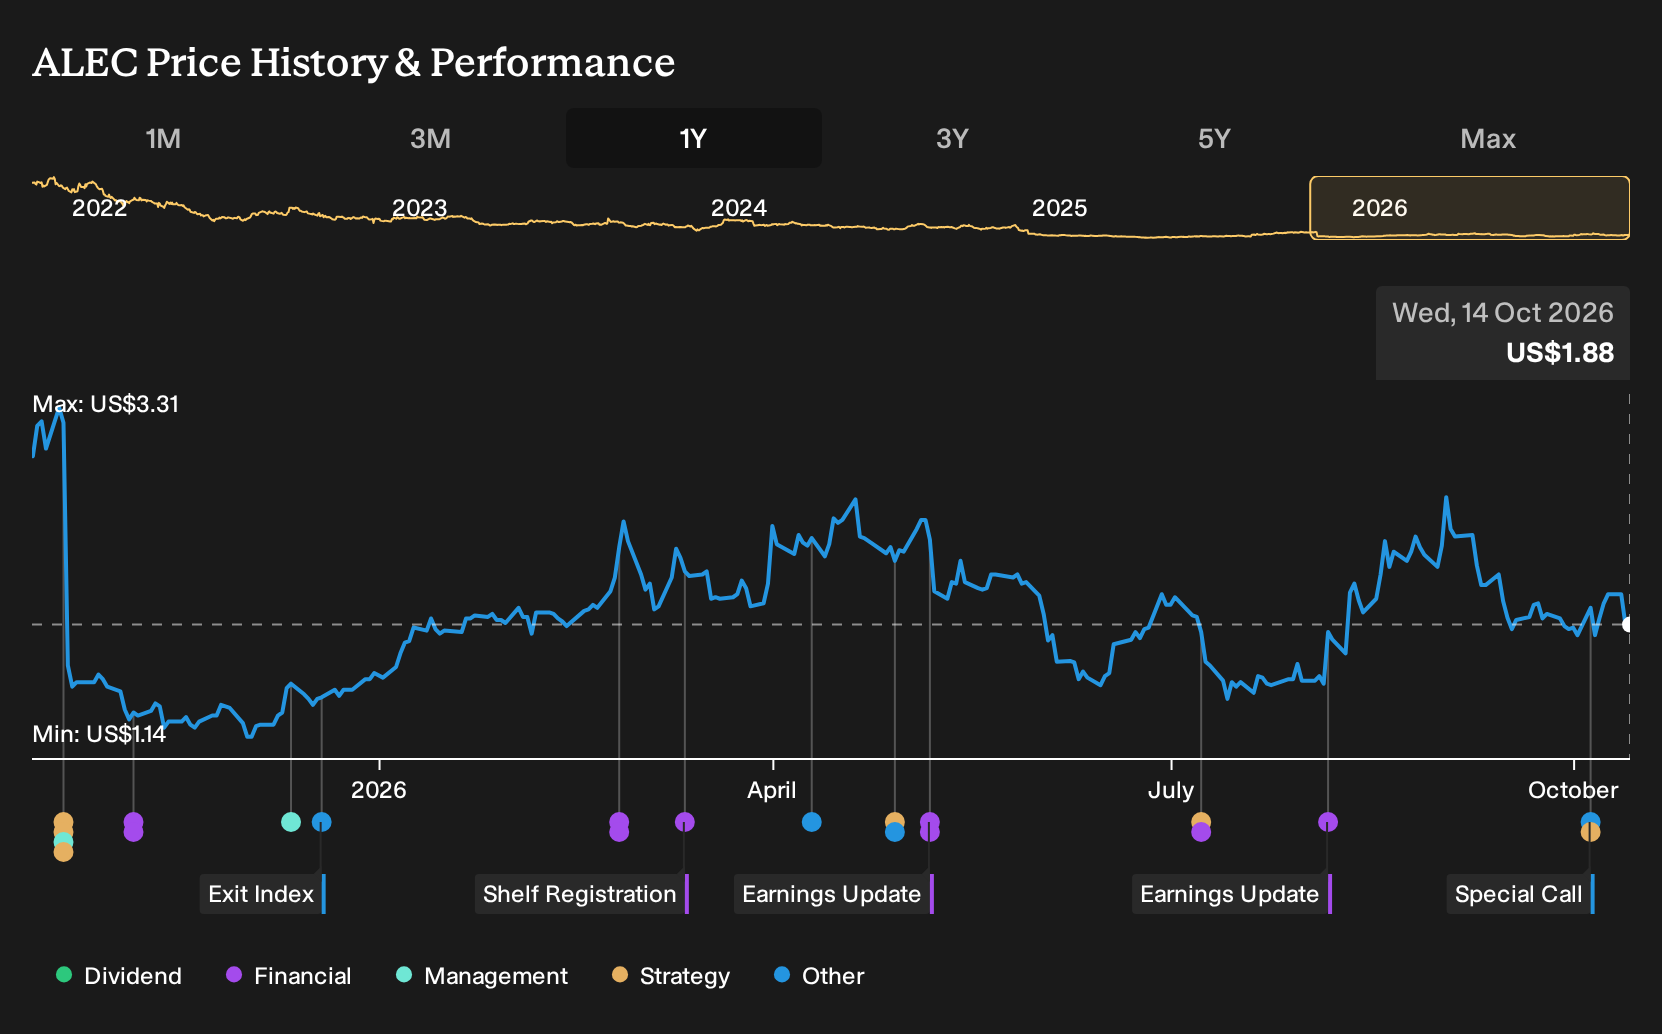
If you had looked at Alector on 14 October 2025 and decided to stay on the sidelines while analysts argued over US$3.83 versus US$1.00 fair value scenarios, that choice avoided real pain. For Alector shareholders, the loss over the past year was 41.1%, including dividends. With Q2 2026 results now showing lower revenue but a smaller loss, the question is which early assumption about trial risk, market size or dilution risk deserved more scrutiny.
If the move has made Alector harder to judge, start where the gap is still open and scan 32 high quality undervalued stocks.
The Two Stories Investors Had To Choose Between On Alector
The shares cost US$2.99 at the start of the period, and Alector looked like a classic biotech coin toss built around a single late stage program.
In the bullish story, a Fair Value of US$3.83, the price implied by optimistic trial and earnings assumptions, rested on latozinemab reshaping care in frontotemporal dementia and analysts assuming revenue growth of 64.8% with profit margins turning positive to 18.8% within three years.
The bearish view pointed to a Fair Value of US$1, based on shrinking revenue at a 43.3% rate, pressure from a tiny FTD-GRN market of 8,000 to 17,000 patients and ongoing dilution risk from high R&D spending.
What The Results Changed For Alector
The cleanest data point was Alector’s Q2 2026 report, which showed revenue at US$3.32m versus US$7.874m a year earlier, while the loss narrowed from US$30.524m to US$22.99m. That mix challenged the bullish call for rapid top line expansion and still left profitability unproven, so the evidence leaned toward the more cautious case.
The key assumption was not trial headlines but the pace of revenue and loss recovery. When you judge another biotech, track whether reported sales and net income are actually moving toward the multi year targets that supported the original P/E story.
What Alector’s Lower Price Now Asks You To Believe
Alector trades at US$1.88 after a 41.1% loss over the past year, while the selected Narrative’s Fair Value sits above the current price and rests on its ABC brain shuttle platform rather than the discontinued late stage work.
For the fall to look like opportunity instead of warning, a buyer would need confidence that AL137 and other ABC assets actually reach human trials and show biomarker proof that justifies a broader CNS portfolio.
"Key Takeaways: Some analysts expect Alector to turn its ABC blood brain barrier platform and refocused neurodegeneration pipeline into a portfolio of brain penetrant biologics and nucleic acid therapies as multiple programs move toward the clinic by 2027. The main factor that would need to go right is successful clinical entry and biomarker proof of concept for AL137 and other ABC based assets, supported by current non human primate data, manufacturing readiness, and the extended cash runway associated with the AL050 partnership."
That disagreement has a full argument behind it. → Uncover the higher Fair Value this Narrative argues for
Looking One Step Beyond Alector
Alector asks you to think about brains, not just balance sheets. Its focus on difficult neurological problems is not unique in healthcare.
Another large drug group pursues similar questions from a different angle. It develops treatments for obesity, diabetes and cancer, with neuroscience also involved.
The shared thread is medicine that may reshape difficult disease patterns over time. Reaching that point requires extensive trial programs and careful safety monitoring.
Where Alector leans on early stage platforms, this other business already has established products in use. That contrast can guide how you weigh risk, commitment and timing.
It is written up in full, assumptions and all. → Explore the Narrative that puts this company 22% above its price
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com