
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Should New Cell Culture Plate Require Action From Mitsui Chemicals (TSE:4183) Investors?
- Mitsui Chemicals has launched InnoCell P-Type, an adherent cell culture plate that uses highly oxygen permeable materials and surface treatment technology to support organoid and cell tissue model development for more precise drug efficacy and toxicity testing.
- The new InnoCell P-Type product strengthens Mitsui Chemicals' positioning in life science tools at a time when its specialty segments in semiconductors, medical devices, and vision care materials are seeing solid demand across multiple end markets.
- The focus now is on how Mitsui Chemicals' expanding InnoCell P-Type cell culture platform could influence the broader investment narrative.
See how Mitsui Chemicals fits into the wider life science tool opportunity by comparing it with our hand picked 10 healthcare AI stocks benefiting from data driven drug discovery and advanced research platforms.
Mitsui Chemicals Investment Narrative Recap
To own Mitsui Chemicals, you need to believe the shift toward specialty products like ICT, life science tools and healthcare materials can steadily outweigh pressure in Basic & Green Materials. The key near term swing factor is execution on that portfolio mix, while keeping cash generation healthy in the face of high fixed costs and maintenance needs.
The launch of InnoCell P-Type looks incremental for now. It supports the Life & Healthcare Solutions story but does not change that the largest risk is prolonged weakness or restructuring noise in commodity linked units, together with currency swings that can squeeze margins even when specialty demand is solid.
The InnoCell P-Type release plugs directly into the Life & Healthcare Solutions segment, where Mitsui Chemicals already supplies vision care, medical materials and agrochemicals. Adding higher value lab tools gives the group another way to lean into data driven drug discovery and research spending, while reducing dependence on more volatile bulk chemicals.
For you as an investor, the practical question is whether this type of niche, IP heavy product can scale fast enough to matter against headwinds like high debt levels and FX sensitivity. Execution on pricing, adoption by pharma and biotech customers, and disciplined capital allocation will decide how much this new platform really contributes to earnings quality.
Mitsui Chemicals' current earnings sit at ¥65.7 billion, while analysts on consensus expect earnings to reach ¥87.8 billion by 2029. This implies an increase of about ¥22.1 billion, with this forecast sitting alongside an assumption of 5.3% yearly revenue growth and projected 2029 revenues of ¥1,998.5 billion.
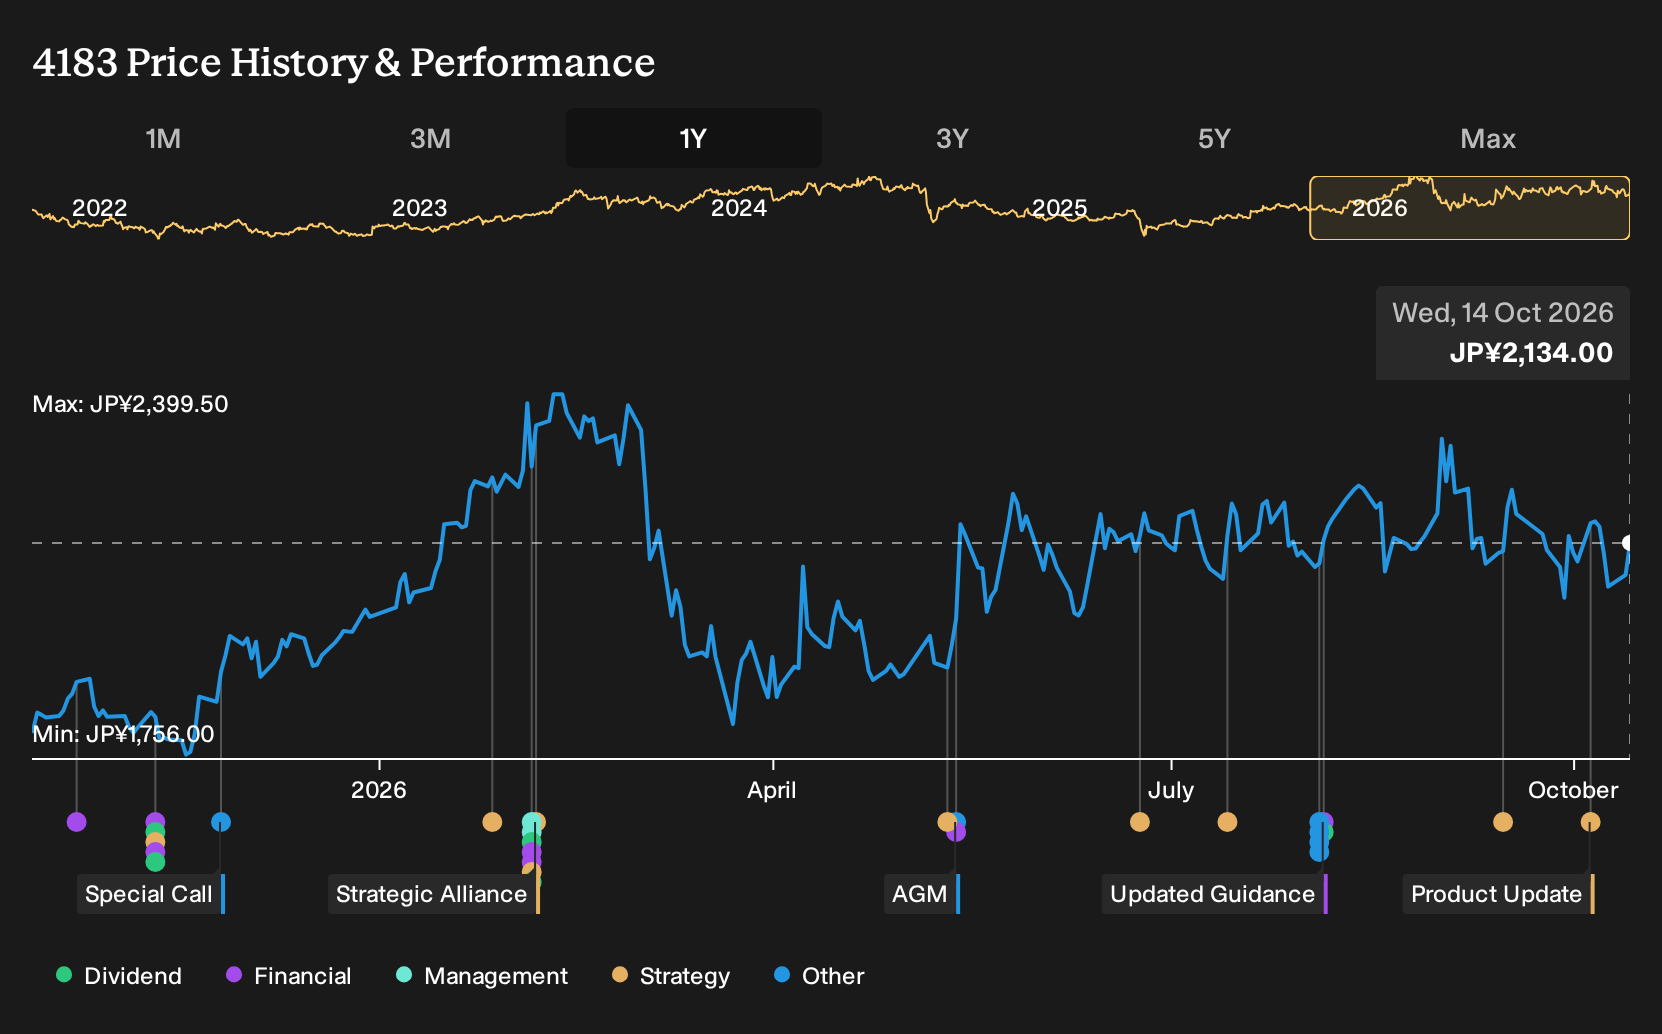
Uncover why Mitsui Chemicals' fair value indicates an 18% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
One alternate view leans hard into Mitsui Chemicals’ potential as a specialty player. The most optimistic analysts were already penciling in revenues of ¥2,077.8 billion and earnings of ¥108.1 billion by 2029 before InnoCell P-Type appeared. You can treat this launch as a fresh test of whether that upbeat storyline still holds or needs rethinking.
The Verdict Is Yours
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Mitsui Chemicals research is our analysis highlighting 5 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Mitsui Chemicals. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Mitsui Chemicals' overall financial health at a glance.
Looking For More Investment Ideas Beyond Mitsui Chemicals?
If you want to pressure test your view on Mitsui Chemicals, it can help to compare it with other opportunities that share different mixes of quality, income, and risk. The Simply Wall St Screener gives you curated sets of stocks that fit specific profiles so you can quickly spot what appeals to your own approach.
- If you care most about resilient balance sheets and solid fundamentals, start by scanning this list of solid balance sheet and fundamentals (21 results) to see which businesses match that profile.
- For investors hunting for mispriced quality, use the focus on attractively valued, fundamentally sound companies in the 15 high quality undervalued stocks to broaden your watchlist.
- If income reliability matters to your process, you can zero in on higher yielding opportunities through a curated 28 dividend fortresses that targets payout strength.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com