
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Dividend Investors: Don't Be Too Quick To Buy Amlak International Finance Company (TADAWUL:1182) For Its Upcoming Dividend
Readers hoping to buy Amlak International Finance Company (TADAWUL:1182) for its dividend will need to make their move shortly, as the stock is about to trade ex-dividend. Typically, the ex-dividend date is two business days before the record date, which is the date on which a company determines the shareholders eligible to receive a dividend. The ex-dividend date is of consequence because whenever a stock is bought or sold, the trade can take two business days or more to settle. Thus, you can purchase Amlak International Finance's shares before the 19th of October in order to receive the dividend, which the company will pay on the 1st of November.
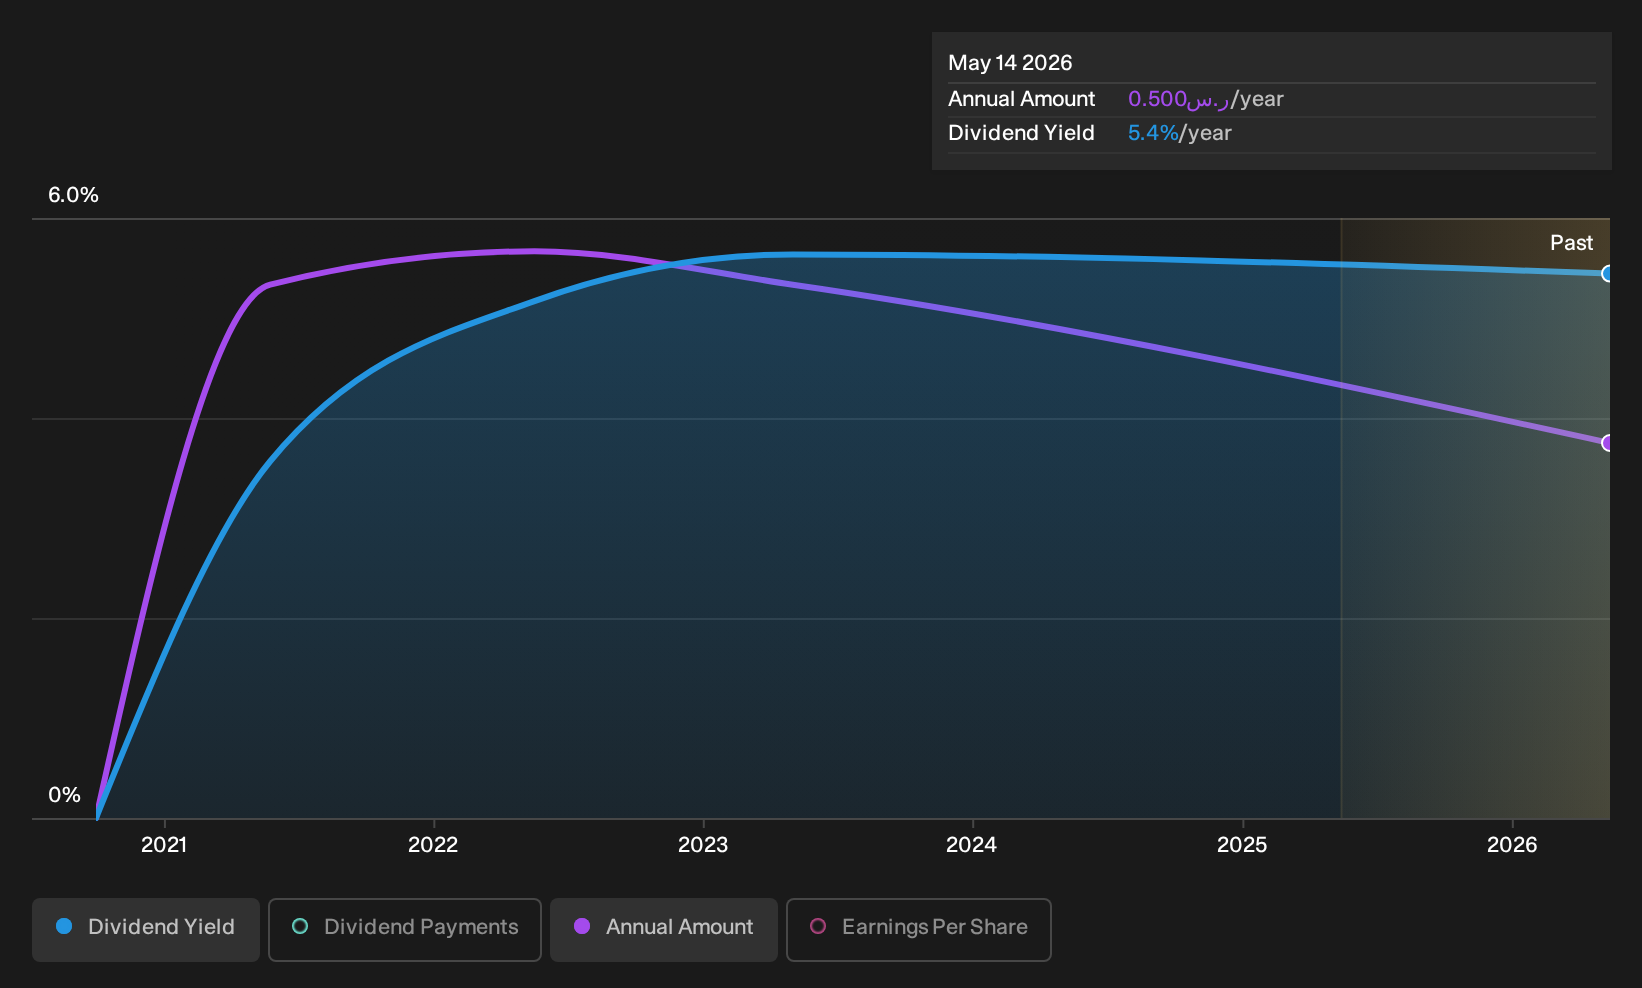
The company's next dividend payment will be ر.س0.30 per share. Last year, in total, the company distributed ر.س0.50 to shareholders. Based on the last year's worth of payments, Amlak International Finance has a trailing yield of 5.7% on the current stock price of ر.س8.76. Dividends are a major contributor to investment returns for long term holders, but only if the dividend continues to be paid. So we need to investigate whether Amlak International Finance can afford its dividend, and if the dividend could grow.
Dividends are typically paid from company earnings. If a company pays more in dividends than it earned in profit, then the dividend could be unsustainable. Amlak International Finance paid out more than half (69%) of its earnings last year, which is a regular payout ratio for most companies. Amlak International Finance paid a dividend despite reporting negative free cash flow over the last twelve months. This may be due to heavy investment in the business, but this is still suboptimal from a dividend sustainability perspective.
Companies that pay out less in dividends than they earn in profits generally have more sustainable dividends. The lower the payout ratio, the more wiggle room the business has before it could be forced to cut the dividend.
See our latest analysis for Amlak International Finance
Click here to see how much of its profit Amlak International Finance paid out over the last 12 months.
Have Earnings And Dividends Been Growing?
Companies with falling earnings are riskier for dividend shareholders. Investors love dividends, so if earnings fall and the dividend is reduced, expect a stock to be sold off heavily at the same time. Readers will understand then, why we're concerned to see Amlak International Finance's earnings per share have dropped 5.6% a year over the past five years. Such a sharp decline casts doubt on the future sustainability of the dividend.
The main way most investors will assess a company's dividend prospects is by checking the historical rate of dividend growth. Amlak International Finance has seen its dividend decline 5.7% per annum on average over the past six years, which is not great to see. While it's not great that earnings and dividends per share have fallen in recent years, we're encouraged by the fact that management has trimmed the dividend rather than risk over-committing the company in a risky attempt to maintain yields to shareholders.
To Sum It Up
Should investors buy Amlak International Finance for the upcoming dividend? We're not overly enthused to see Amlak International Finance's earnings in retreat at the same time as the company is paying out more than half of its earnings as dividends to shareholders. These characteristics don't generally lead to outstanding dividend performance, and investors may not be happy with the results of owning this stock for its dividend.
With that being said, if you're still considering Amlak International Finance as an investment, you'll find it beneficial to know what risks this stock is facing. Be aware that Amlak International Finance is showing 3 warning signs in our investment analysis, and 2 of those are potentially serious...
Generally, we wouldn't recommend just buying the first dividend stock you see. Here's a curated list of interesting stocks that are strong dividend payers.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team (at) simplywallst.com.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.