
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
T Mobile (TMUS) Stock Trades At A Discount Following Its 36% 5 Year Return
T-Mobile US has seen its share price fall in recent months, and the pullback has sharpened the question of whether the current valuation lines up with what the business earns today. With the stock reacting to both competitive headlines and changing expectations, the key issue now is how much of T-Mobile US's earnings power is already reflected in the price.
- Over the past 5 years the stock has delivered a total return of 36.1%, which puts longer term gains at stake if the current earnings profile does not support that journey.
- Fresh pressure from SpaceX's Starlink plans and a new joint venture with AT&T and Verizon can influence how investors think about T-Mobile US's future profitability, capital needs and the timing of cash flows that underpin any earnings based valuation.
- The analysts covering T-Mobile US have run their own numbers. See what analysts think T-Mobile US's shares could be worth.
The issue now is whether T-Mobile US's current share price is adequately supported by its earnings when judged against the Fair Ratio benchmark.
If you want a broader feel for how other telecom related stocks compare on quality and value, line T-Mobile US up against the companies in the 32 high quality undervalued stocks.
Does T-Mobile US Look Undervalued on Earnings?
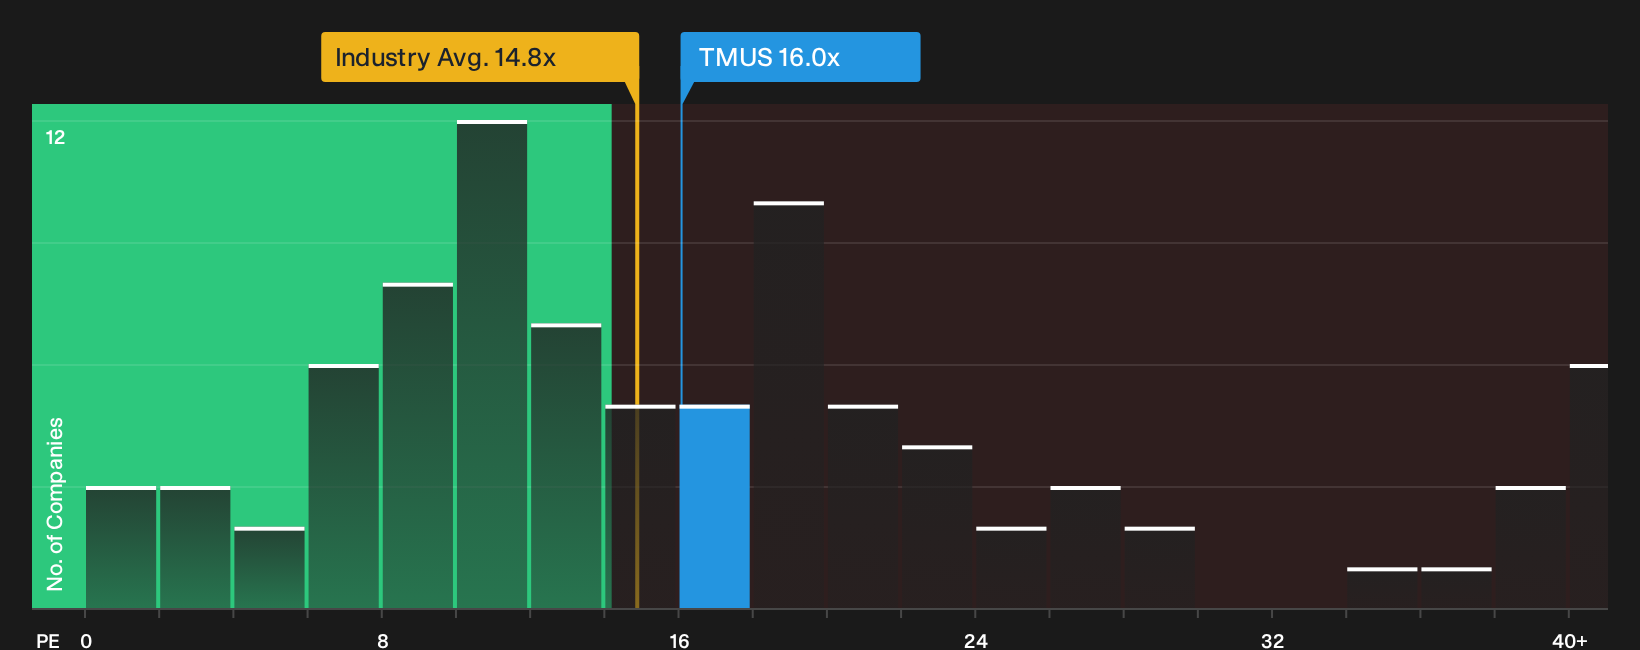
P/E is a useful lens for T-Mobile US because investors often focus on earnings for mature telecom operators where profit streams are relatively established. The stock trades on a P/E of about 16.0x, which is above the wireless telecom sector average of roughly 14.8x but well below the broader peer group on about 33.2x.
On Simply Wall St's Fair Ratio framework, which adjusts the P/E you might expect for T-Mobile US for its growth profile, margins, scale and risk, the current multiple sits below the modelled level, so the shares screen as undervalued on this measure. Despite the recent Starlink spectrum deal putting pressure on sentiment, the P/E still prices T-Mobile US at a discount to the Fair Ratio benchmark that other investors following this approach may want to explore in more detail. Explore the numbers behind T-Mobile US's P/E valuation.
The T-Mobile US Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for T-Mobile US connect the valuation puzzle above to concrete guesses about the future by outlining what paths for growth, margins and earnings would need to occur for the stock to be worth materially more or materially less than it trades for today. Each scenario links a fair value estimate to a particular mix of potential catalysts and risks, allowing you to track over time which version of T-Mobile US' story is actually unfolding on the Community page.
One of the top community narratives on T-Mobile US: 33% undervalued
"The main thing that has to go right is that T-Mobile US continues to convert network and AI investments into higher value postpaid, broadband and adjacency revenue..."
Discover why this Narrative puts T-Mobile US at 33% undervalued.
T-Mobile US investors still have one big piece of the puzzle left
Price and current earnings only tell part of T-Mobile US's story, because professional analysts have laid out where they think this business could be a few years from now. Explore where analysts expect T-Mobile US to be in a few years.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com