
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Special Dividend Could Change The Case For Winmark Stock
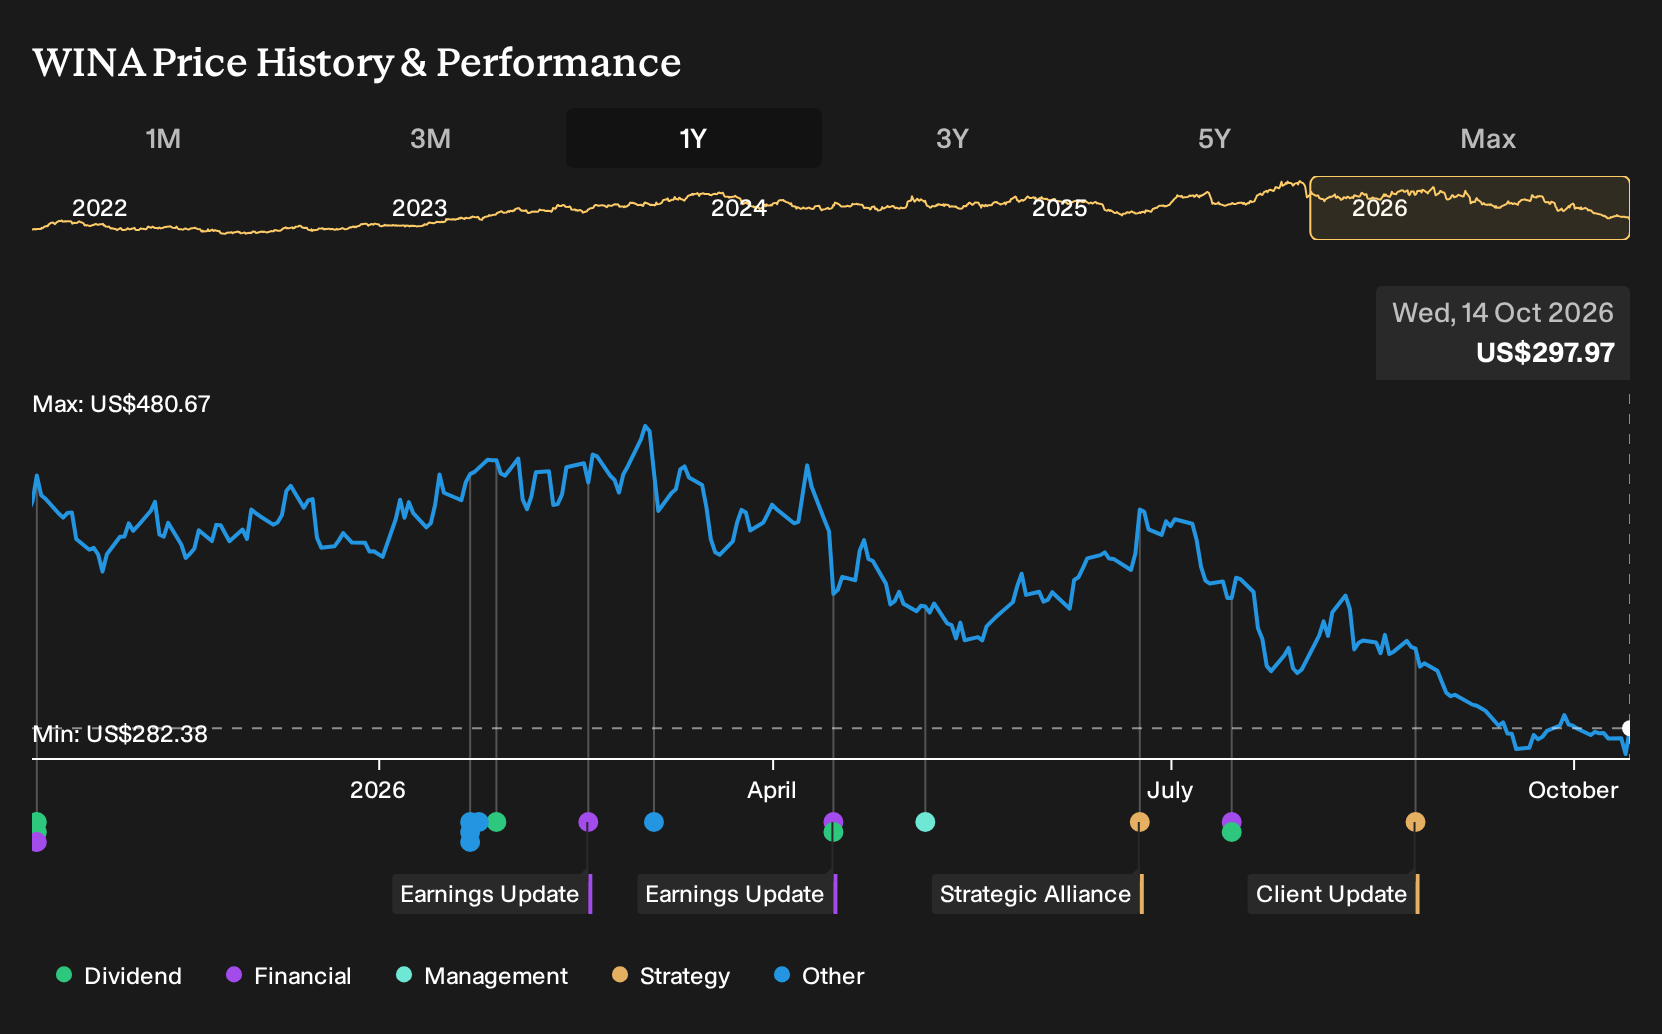
- Winmark announced Board approval of a regular quarterly dividend of $1.02 per share and a special dividend of $4.00 per share, both scheduled for payment on December 1, 2026, to shareholders of record on November 11, 2026, alongside third quarter 2026 revenue of $27.89 million and net income of $11.82 million.
- The business is pairing cash returns funded from cash on hand with a marketing push, including a North American Advertising Fund for Plato's Closet and planned advertising funds for Once Upon A Child and Play It Again Sports from 2027, highlighting a shift toward broader brand awareness alongside franchising economics.
- This article reviews how Winmark's investment narrative is influenced by the special dividend announcement in combination with the latest quarterly earnings figures.
Compare Winmark's dividend-focused profile with a curated shortlist of income ideas in our 7 dividend fortresses, which pairs high yields with robust underlying businesses.
What Is Winmark's Investment Narrative?
To own Winmark, you need to be comfortable with a franchisor that leans heavily on high margin royalty streams and relatively light capital needs, while layering on meaningful cash returns. The regular and special dividends signal that management still views excess cash as better in shareholder hands than sitting on the balance sheet. Third quarter revenue of US$27.89 million and net income of US$11.82 million show the engine that funds those payouts, although nine month earnings are essentially flat year on year, so this is not a pure growth story.
The near term swing factors are execution on brand marketing, franchisee economics and the balance between dividends, buybacks and debt. The new North American Advertising Fund and the planned 2027 funds for Once Upon A Child and Play It Again Sports push spending up before any benefit to system sales is clear. At the same time, Winmark carries high debt, negative equity and a dividend that recent analysis flagged as not well covered by free cash flow, which makes a US$14.2 million special dividend feel like a more consequential capital allocation call than a routine check.
Even so, there is one capital structure wrinkle that could change how you think about Winmark's dividend story entirely...
There's only one way to know the right time to buy, sell or hold Winmark. Head to Simply Wall St's company report for the latest analysis of Winmark's Fair Value.
Exploring Other Perspectives
Across 2 fair value estimates from the Simply Wall St Community, targets stretch from about US$307 to US$545 per share, which shows just how far opinions on Winmark can spread. Those views were set before the latest dividend moves and marketing spending, so you may want to consider how fresh cash returns and higher brand investment might affect that range.
Explore another Winmark fair value estimate, including one that suggests it could be worth just $306.99.
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Winmark research is our analysis highlighting 2 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Winmark. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Winmark's overall financial health at a glance.
Looking For More Investment Ideas Beyond Winmark?
If Winmark's mix of cash returns, franchising economics and brand building has your attention, it can help to put it alongside a wider watchlist of opportunities that fit different goals and risk levels. The Simply Wall St Screener lets you quickly scan the market using clear filters, then zero in on the handful of stocks that deserve your time.
- If you care most about durability and balance sheet strength, start with companies that pair healthy cash flows with conservative funding by running a list of solid balance sheet and fundamentals (25 results).
- If value is your priority, look across businesses that combine quality fundamentals with prices that look conservative relative to their metrics using the 32 high quality undervalued stocks.
- If you want ideas that are less crowded, focus on under-followed opportunities with strong fundamentals by checking out the 20 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com