
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Plains GP Holdings (PAGP) Stock Still Looks Cheap On Sales Today
Plains GP Holdings has delivered a strong multi‑year run, which puts fresh focus on a simple question for anyone looking at the stock today. Given that history, is the current share price still adequately supported by the revenue the business is generating.
- Over the past 5 years the stock has gained 222.8%, which raises the issue of how much sales strength is already reflected in the current valuation.
- Management recently highlighted asset sales, lower leverage and targeted growth spending, which can reshape how much future revenue growth and capital intensity investors build into their expectations.
- There is a second opinion on Plains GP Holdings worth weighing. See what analysts think Plains GP Holdings's shares could be worth.
The stock's next move may depend on whether Plains GP Holdings' current price is well aligned with what investors are willing to pay for each dollar of its sales.
If you are weighing Plains GP Holdings against other businesses where sales and valuation are in focus, it can help to compare it with companies in the 32 high quality undervalued stocks
Is Plains GP Holdings Still Cheap on Sales?
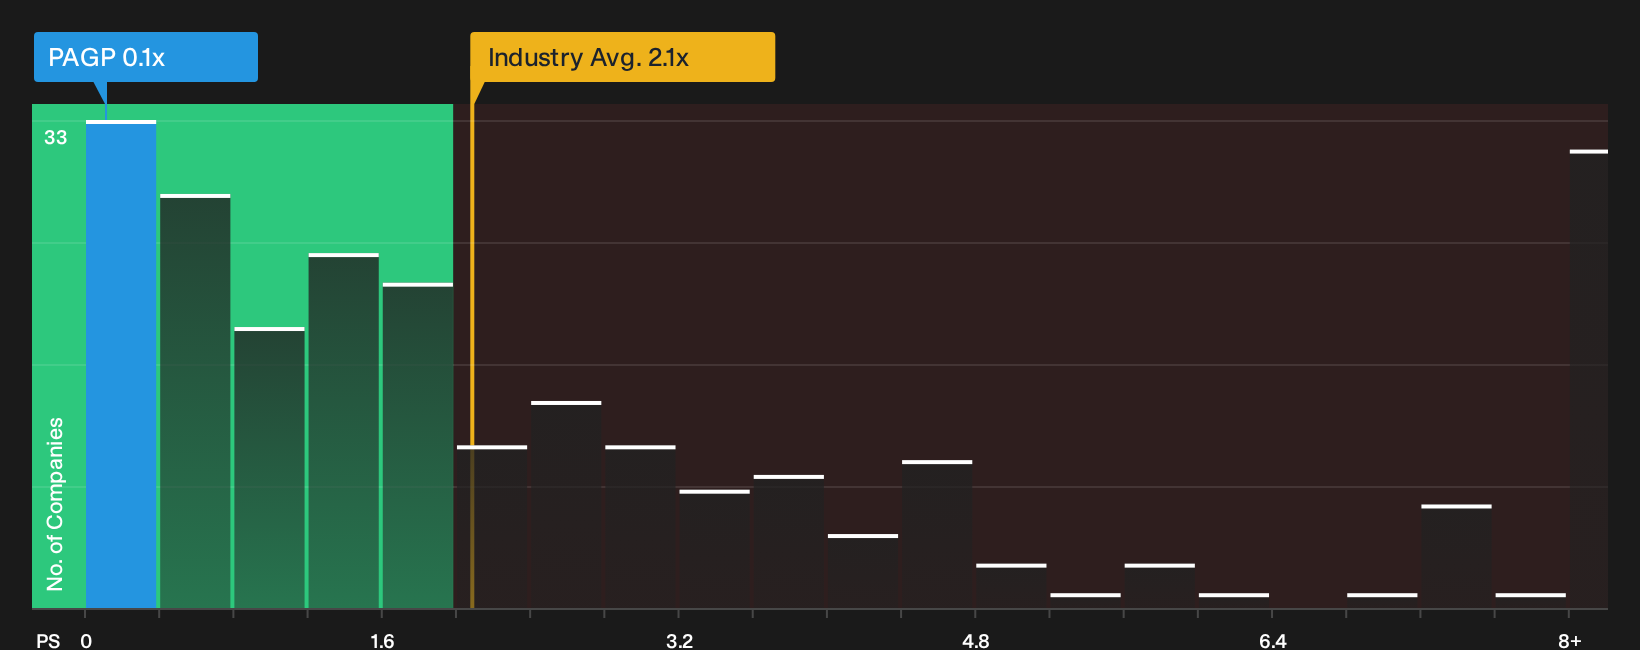
P/S fits Plains GP Holdings because investors tend to focus on the value of its fee based volumes and contracts rather than headline net income swings. On this metric, the stock trades on a P/S of 0.1x, compared with an Oil and Gas sector average of about 2.1x and a peer group closer to 3.2x. That is a very low sales multiple, even before thinking about how its assets or contracts compare qualitatively with rivals.
Because of the Canadian NGL sale and leverage reduction highlighted in the recent Q2 2026 call, some investors may have expected the P/S multiple to move closer to sector levels. Yet it still screens well below what the tailored fair multiple model implies for Plains GP Holdings. That framework, which blends the business mix, margins, market size and risk profile, points to a higher P/S than the one currently in the market, so the shares screen as undervalued on this lens. Explore the numbers behind Plains GP Holdings's P/S valuation.
The Plains GP Holdings Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the P/S puzzle leaves off for Plains GP Holdings' stock by spelling out which combinations of future growth, profitability and earnings power would need to play out for the shares to look meaningfully higher or lower than today. Each scenario ties its number to a clear view on how Plains GP Holdings' revenue trajectory, margin profile and risk picture might evolve, giving you something specific to revisit as new information emerges.
One of the top community narratives on Plains GP Holdings: 5% overvalued
"The planned divestiture of the NGL segment and redeployment of proceeds into core crude oil operations and bolt-on acquisitions are expected to streamline operations…"
Discover why this Narrative puts Plains GP Holdings at 5% overvalued.
One more cross check for Plains GP Holdings beyond the price tag
Before you stop at the P/S comparison for Plains GP Holdings, it is worth asking who is steering the business and how their pay packets line up with your priorities. See who runs Plains GP Holdings and how they are paid.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com