
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
AZZ (AZZ) Stock Shrugs Off Record Sales As Earnings Power Draws Scrutiny
AZZ stock barely flinched after record results, edging up less than 1% even as the business posted a standout quarter. The headline is simple: revenue reached about US$486.9m for Q2 FY2027, with adjusted diluted earnings per share at US$2.00 and adjusted EBITDA of US$110.9m. The market saw a steady industrial player, while the numbers point to a metals and coatings specialist putting real operating muscle to work.
Is AZZ a quiet bargain with a lower P/E than peers, or is the stock simply priced for margins that no longer hold up after the recent compression? See how the current share price lines up against cash flow assumptions and peer multiples in the full valuation analysis for AZZ
Q2 2027 Earnings Summary
- Revenue (Q2 2027 vs Q2 2026): US$486.9m vs. US$417.3m (up about 16.7%)
- Net Income, Excl. Extra Items (Q2 2027 vs Q2 2026): US$58.5m vs. US$89.3m (down about 34.6%)
- Basic EPS, Earnings Per Share (Q2 2027 vs Q2 2026): US$1.95 vs. US$2.97 (down about 34.5%)
- Adjusted EBITDA Margin, Earnings Before Interest, Taxes, Depreciation and Amortization (Q2 2027 vs Q2 2026): 22.8% of sales vs. prior year level not specified (margin expansion of about 80 basis points year on year)
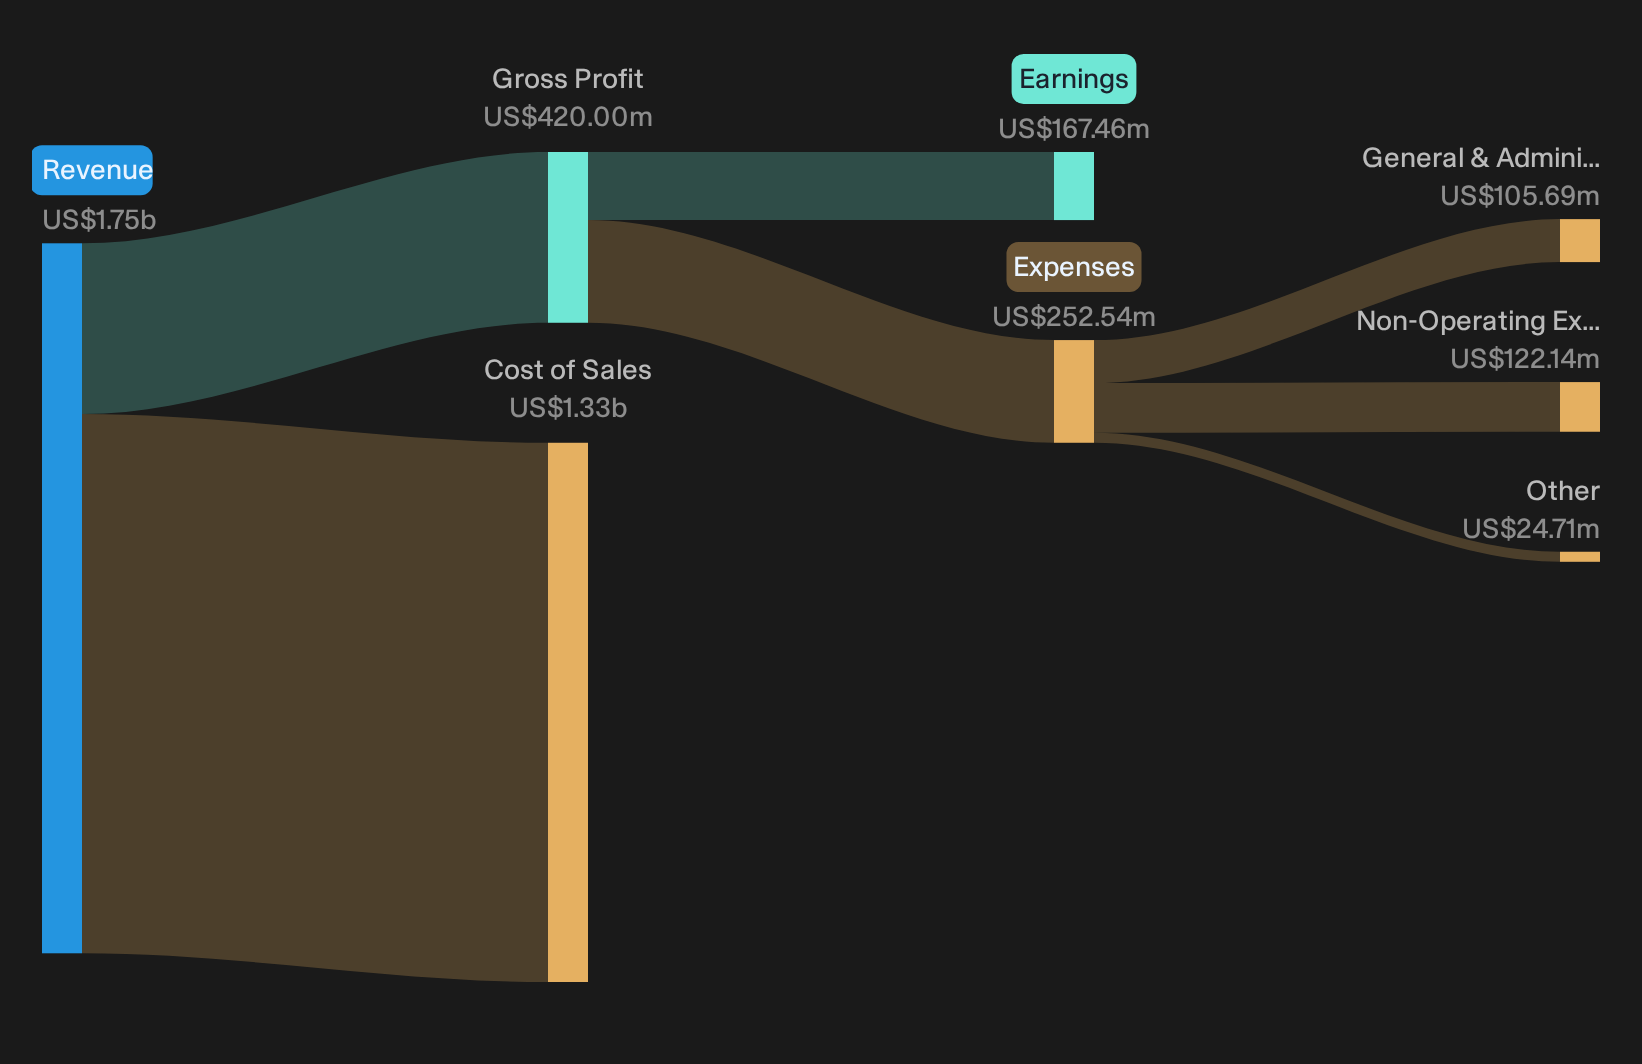
Prefer clean visuals instead of another page of dense earnings tables? See AZZ’s full financial picture, including a clear view of its recent earnings power and profitability trends, in the company report for AZZ.
AZZ bull case: execution on growth levers gets real
Bulls argue AZZ can turn new capacity, digital tools and bolt on deals into higher quality earnings, not just bigger sales. Q2 supports that view in several places. Washington, Missouri is the clearest proof point. Management reports it ramping as planned, already meeting contribution margin targets and driving very strong container growth. Metal Coatings posted 30.7% adjusted EBITDA margin on 22.9% higher revenue, which lines up with the thesis that kettles, greenfields and better pricing can sustain attractive economics. Segment EBITDA of US$110.9m at 22.8% of sales, alongside US$102.8m of operating cash flow, backs the idea that growth is coming through with cash. Raised full year guidance for revenue, EBITDA and EPS shows management leaning into that momentum rather than treating Q2 as a one off.
AZZ bear case: utilization, cyclicality and ramp risk not gone
Skeptics worry AZZ is execution sensitive, with weather, input volatility and ramp timing capable of knocking earnings off track. Parts of Q2 keep those concerns alive. Overall galvanizing fleet utilization is only 60% to 70%, so the story still relies on filling a lot of empty hours at new and upgraded plants. Management called out ongoing steel substrate tightness for Precoat, which can pressure volumes or mix if it worsens. Seasonality is not theoretical either. Q4 is flagged as softer and exposed to winter weather that has previously cut production days. The Washington, Missouri and Seattle Galvanizing ramps are going well, yet the thesis still assumes similar outcomes from Tulsa and future projects. With the stock roughly flat over 7 days and down about 9% over 90 days, investors appear to be treating these execution and cyclicality risks as active issues, not old history.
Compare AZZ’s on the ground progress with what the Street is baking into its models. See the consensus price target analysis for AZZ to evaluate how current analyst targets stack up against this mix of execution upside and utilization, ramp and cyclicality risk.Stay Ahead With Simply Wall St
If AZZ’s mix of record Q2 revenue and margin questions has your attention, register for free with Simply Wall St and add it to a Watchlist to keep an eye on share price moves against fair value and wait for a setup that fits your plan. Once you hold AZZ or other positions, use the Portfolio Command Center to cut through market noise and focus on the key fundamental changes that matter. For longer term decisions, lean on the Community to see how other investors are thinking through the same risks and potential catalysts. By surfacing hidden drivers and pressure points early, Simply Wall St provides tools that can help you make informed decisions based on your own analysis.
Seeking Alternatives Beyond AZZ Stock?
Fresh ideas move first. Breakout themes gain momentum, then get caught by the crowd. Use these curated stock shortlists while the data still matters and get in early.
- Scan for resilient compounding stories with low volatility profiles by reviewing the carefully filtered 32 resilient stocks with low risk scores that can help anchor your portfolio when sentiment turns.
- Target companies riding structural demand in cleaner energy and grid upgrades with the curated 43 power grid technology and infrastructure stocks to explore opportunities in this area.
- Hunt for durable income opportunities with pricing power using the hand picked 7 dividend fortresses so potential high yield candidates are on your radar.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com