
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Lionsgate Studios (LION) Slides Following A Sharp Pullback, Is The Stock Cheap?
Lionsgate Studios (LION) has been drawing attention after a period where the share price fell about 20% over the past 3 months, even as year to date and 1 year returns remain strongly positive.
Lionsgate Studios’ recent 90-day share price decline of 20.3% contrasts with a stronger backdrop, where the year-to-date share price return is 19.6% and the 1-year total shareholder return sits at 82.3%. This suggests that momentum has cooled after a powerful run.
Compare Lionsgate Studios’ recent pullback with a curated 20 high quality undiscovered gems that may be flying under the radar before sentiment shifts.
The question now is simple. After Lionsgate Studios’ sharp pullback following a strong 1-year run, does it make more sense to start building a position here or wait for a clearer valuation cushion?
Most Popular Narrative: 24% Overvalued
The most followed narrative sets Lionsgate Studios’ fair value at $9.00 using a 12.54% discount rate. This sits below the recent $11.12 close, so the current pullback still prices the shares above that framework.
While the company expects to return to positive free cash flow and OIBDA growth in fiscal 2027, anchored by major tentpole releases and an uptick in episodic TV deliveries, high debt levels and elevated interest expenses remain a persistent overhang, constraining capital available for reinvestment and potentially limiting net margin improvement if operating results fall short of targets. Even as Lionsgate expands into emerging distribution channels such as FAST and AVOD to further monetize its back catalog, the shift toward fragmented, direct-to-consumer formats and higher production costs from ongoing unionization and labor disruption risks introduce additional earnings volatility, posing challenges for reliable bottom-line improvement in the years ahead.
See why 2 investors see Lionsgate Studios as 24% overvalued.
Result: Fair Value of $9.00 (OVERVALUED)
Still, there are clear pressure points that could overturn this fair value view, including Lionsgate Studios’ reported 1.5b dollars in net debt and ongoing operating losses.
Find out about the key risks to this Lionsgate Studios narrative.
Another Take: DCF Points To Undervaluation
The narrative crowd sees Lionsgate Studios as 24% overvalued at $11.12 versus a $9.00 fair value. Our DCF model tells a different story. On projected future cash flows, it points to a value of $12.94, which puts the current quote about 14% below that estimate. Which lens do you trust more?
For a closer look at the moving parts behind that cash flow view, Look into how the SWS DCF model arrives at its fair value.
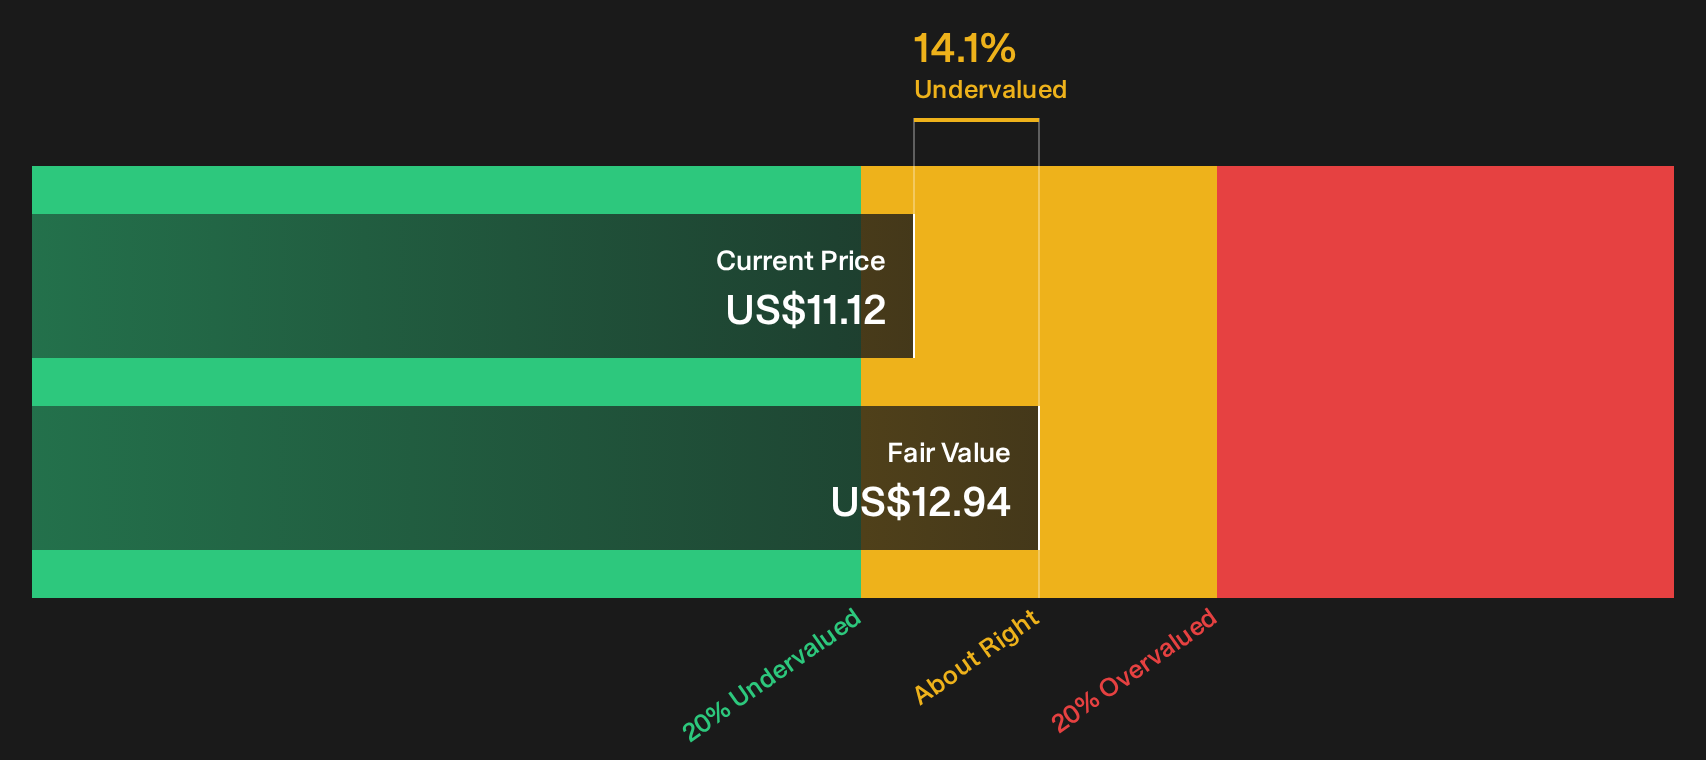
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Lionsgate Studios for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 32 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Conflicting signals around Lionsgate Studios can feel messy, so move quickly, review the data across both risks and potential upsides, and weigh the 3 key rewards and 2 important warning signs.
Looking for more ideas beyond Lionsgate Studios?
If Lionsgate Studios has sharpened your focus on risk, reward, and timing, broaden your watchlist now using a few targeted stock lists built from hard numbers.
- Target potential mispricings by scanning a curated 32 high quality undervalued stocks that combine quality fundamentals with prices that lag their underlying business strength.
- Anchor your portfolio with income by reviewing a focused set of 8 dividend fortresses that pair higher yields with robust payout histories and balance sheets.
- Sleep easier through volatility by filtering for 32 resilient stocks with low risk scores designed to prioritize resilient financial profiles over headline excitement.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com