
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Is Energizer Holdings (ENR) Cheap Or Fully Valued After Its Recent Rebound?
Energizer Holdings (ENR) has drawn fresh attention after recent price moves, with the stock last closing at $21.85. Investors are weighing that share level in relation to its recent performance and the company’s underlying earnings profile.
Recent trading has been constructive for Energizer Holdings, with the 1-day share price return of 3.21% adding to a 30-day share price return of 6.17% and a 90-day share price gain of 5.61%. That short stretch contrasts with weaker long-term performance. The 1-year total shareholder return declined 2.59% and the 5-year total shareholder return fell 27.47%, suggesting recent momentum is building from a much softer base.
Scan beyond Energizer Holdings and spot other consumer-focused stocks showing similar momentum and quality traits with the curated list of solid balance sheet and fundamentals (25 results)
The rebound in Energizer Holdings is modest compared with the longer term slide. This puts the spotlight on where fair value really sits between a US$21.85 price and a wide range of estimates. How much gap is left to close?
Price-to-Earnings of 18.4x: Is it justified?
Energizer Holdings trades on a P/E of 18.4x, which investors are weighing against its $21.85 share price and how that compares with both peers and fair value estimates.
The P/E multiple compares the current share price to earnings per share. For a business like Energizer Holdings that sells everyday consumer products and auto care brands, this ratio is a common shortcut for how much the market is willing to pay for each dollar of profit.
On Simply Wall St’s framework, Energizer Holdings screens as good value with a P/E of 18.4x against an estimated fair P/E of 18.9x. The difference between the two figures is very small and indicates that the current pricing is close to where a regression-based view of fair value places the multiple.
Against the wider Household Products group, the picture shifts. A P/E of 18.4x is described as expensive relative to the global industry average of 17x, yet still lower than a peer set average of 23x. The stock therefore trades above the broad sector yardstick but below closer comparable companies, which points to a middle ground rather than a clear bargain or obvious excess optimism.
Explore the SWS fair ratio for Energizer Holdings.
Result: Price-to-Earnings of 18.4x (ABOUT RIGHT)
Still, Energizer Holdings carries clear risks, including pressure from private label competition in everyday batteries and reliance on retailers that could reset shelf space or pricing.
Find out about the key risks to this Energizer Holdings narrative.
Another View on Energizer Holdings: Cash Flows Tell a Different Story
While the P/E of 18.4x suggests Energizer Holdings is roughly in line with a fair ratio of 18.9x, the SWS DCF model points in a very different direction. On that cash flow view, a share price of $21.85 compares with an estimated future cash flow value of $89.90. This frames the stock as heavily undervalued and raises the question of whether earnings multiples are missing something important.
Look into how the SWS DCF model arrives at its fair value.
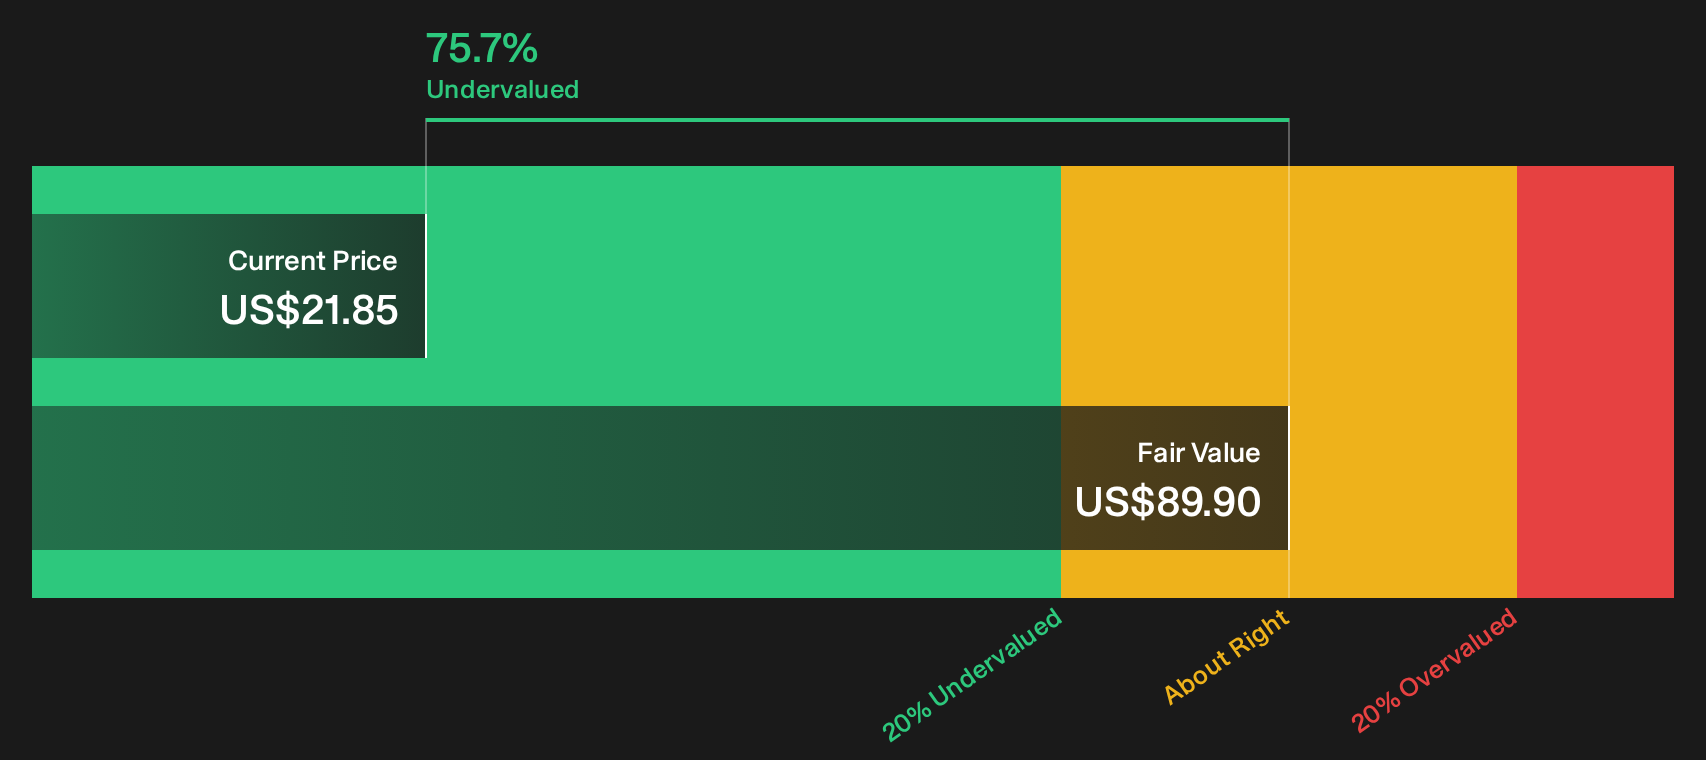
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Energizer Holdings for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 32 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals on Energizer Holdings so far. If the valuation gap and sentiment split matter to you, follow the numbers yourself and decide whether the potential trade off of risk and reward feels acceptable after reviewing the 2 key rewards and 4 important warning signs.
Looking for more investment ideas beyond Energizer Holdings?
If Energizer Holdings has you rethinking value and risk, do not stop here. Use targeted stock lists to pressure test your next move and avoid leaving potential ideas untouched.
- Chase potential value opportunities by scanning a curated pool of companies that combine quality fundamentals with appealing pricing through the 32 high quality undervalued stocks.
- Firm up your income toolkit by reviewing a focused group of high yielding payers that aim for resilience in their payouts using the 8 dividend fortresses.
- Tighten your risk filter by checking a pre-vetted 32 resilient stocks with low risk scores that highlights businesses with more resilient profiles when conditions get tougher.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com