
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Learn Why The Bull Case For Graphic Packaging Holding Stock Could Change Following Delayed Customer Orders
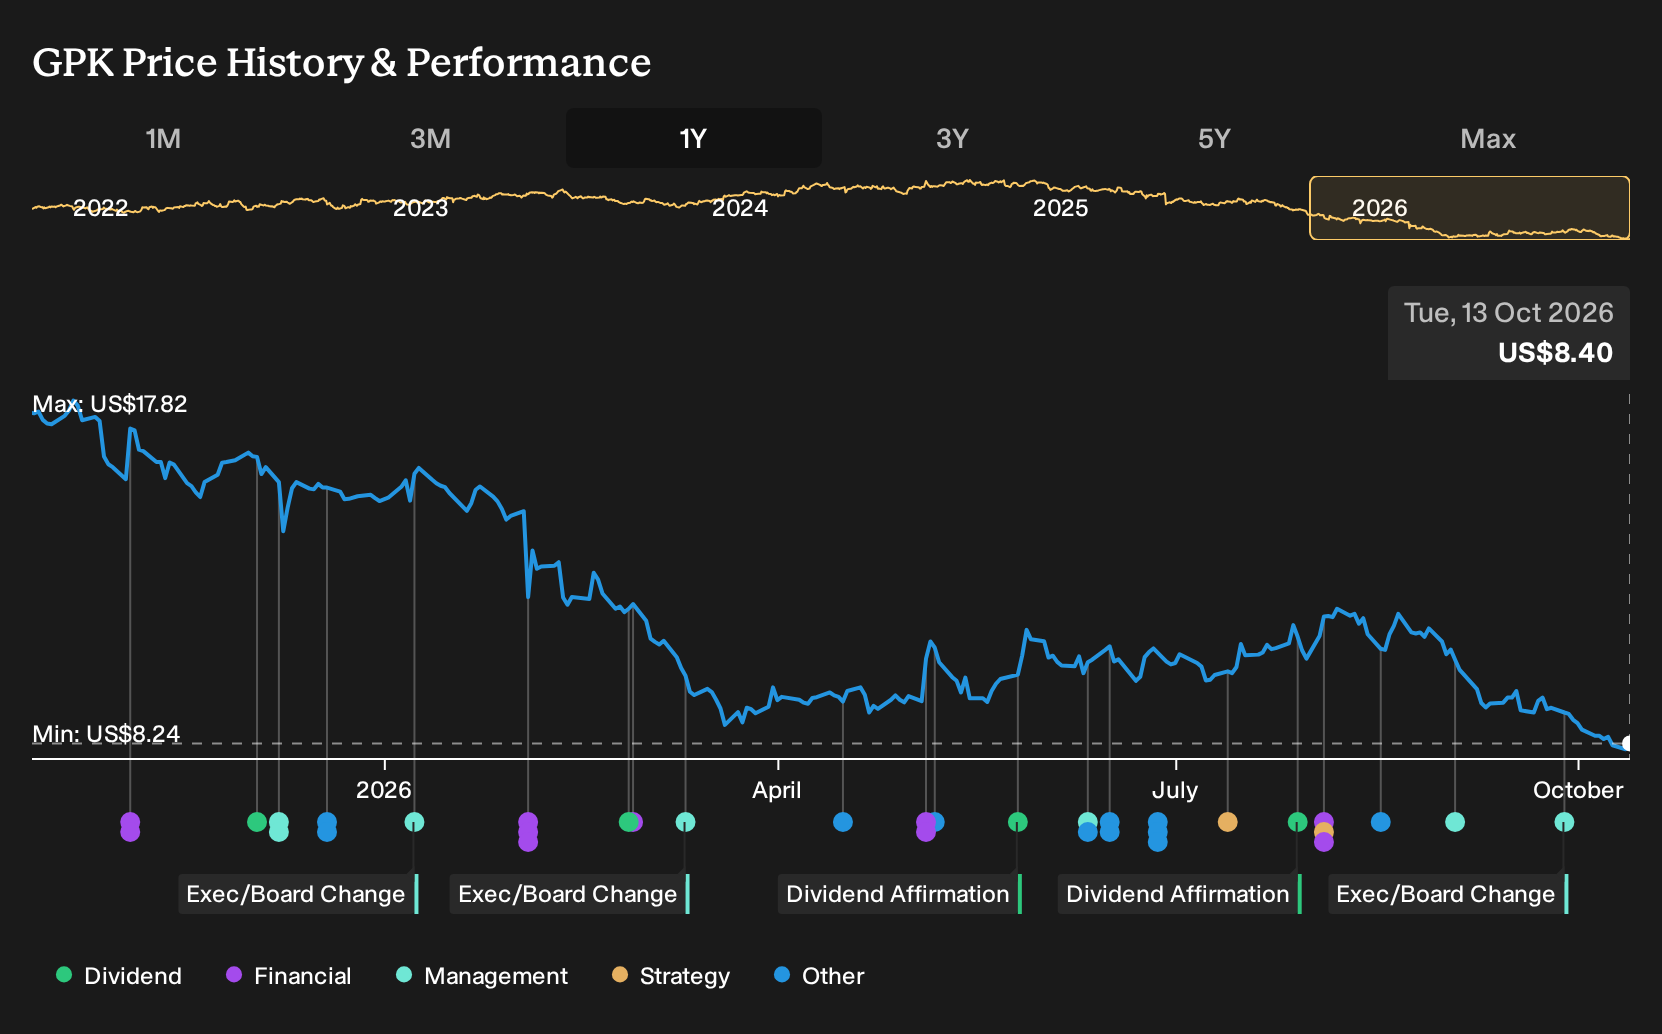
- Graphic Packaging Holding has reported a 2.5% annual revenue decline over the past two years and a 36.8% annual drop in earnings per share, with estimated sales for the next 12 months expected to remain flat as customers postpone purchases.
- The combination of weaker demand, delayed customer orders and sharply lower earnings is putting the company’s ability to improve long term performance under closer investor scrutiny.
- We will look at how Graphic Packaging Holding's investment narrative is challenged by ongoing earnings pressure from a softer demand backdrop.
Graphic Packaging Holding Investment Narrative Recap
To remain a shareholder in Graphic Packaging Holding, you would need to believe that the heavy investment phase and current earnings pressure eventually translate into steadier cash generation and healthier margins. In the short term, customer volumes are the main swing factor. With revenue and EPS both under pressure and sales expected to stay flat, any pickup in orders would likely have a quick impact.
The biggest risk at the moment is that weak demand lasts longer than management or customers expect, keeping mills underused and reducing returns on past capital expenditures. Inflation and higher costs have already affected profitability. If pricing power weakens while volumes remain soft, the earnings drag that is visible today could continue.
Recent guidance on capital spending is the announcement most connected to this weaker earnings backdrop. Graphic Packaging Holding now plans for 2026 capital expenditures below US$450 million after cancelling about US$200 million of automated roll warehouse projects. This points to a pause in large build-outs and a shift toward preserving cash.
For shareholders, the key issue is the link between lower spending and the earnings decline. A lighter capital expenditure bill can help support free cash flow if demand improves, but it also underscores how sensitive large projects can be to inflation and changes in scope. If future projects encounter similar cost overruns or need to be scaled back, achieving stronger margins and repairing the balance sheet may become more challenging.
What The Current Forecasts Assume For Graphic Packaging Holding
Graphic Packaging Holding's current analyst narrative rests on a forecast that revenue rises to US$9.0b and earnings reach US$396.0m by 2029. This is based on an assumed 1.5% annual top line growth rate and a margin lift from 2.2% today to 4.4% over the same period.
On the earnings side, the projections imply that profit almost doubles from US$194.0m today to that US$396.0m level. That is an earnings increase of about US$202.0m, with consensus clustering around this target but a wide spread between the most optimistic and most cautious estimates. For you as a shareholder or potential investor, the key question is whether a move to roughly 2x current earnings and a modest revenue growth rate looks realistic against the softer demand backdrop described earlier and the planned pullback in capital spending.
Graphic Packaging Holding's narrative projects US$9.0b revenue and US$396.0m earnings by 2029. This requires 1.5% yearly revenue growth and an earnings increase of about US$202.0m from US$194.0m today.
Uncover why Graphic Packaging Holding's fair value indicates a 47% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
One alternative view on Graphic Packaging Holding leans hard into the inflation risk. The most cautious analysts were only penciling in about US$8.6b of 2029 revenue and US$302.1m of earnings before this latest earnings setback. Their story is that persistent cost pressure caps any recovery. That more pessimistic script may evolve once this new data is fully reflected.
Explore 2 other Graphic Packaging Holding fair value estimates, including one that suggests it could be worth just $10.95!
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Graphic Packaging Holding research is our analysis highlighting 4 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Graphic Packaging Holding. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Graphic Packaging Holding's overall financial health at a glance.
Looking For More Investment Ideas Beyond Graphic Packaging Holding?
Once you have weighed the case for Graphic Packaging Holding, it can help to compare it with other businesses that match different priorities such as value, resilience, or balance sheet strength. The Simply Wall St Screener lets you filter the market using those kinds of traits so you can build a watchlist that fits your own risk comfort and return goals.
- If you want potential upside combined with quality fundamentals, start with a focused group of value opportunities using the 32 high quality undervalued stocks.
- For investors who care most about financial resilience and lower risk profiles, narrow the field with a 32 resilient stocks with low risk scores that emphasises sturdier metrics.
- If balance sheet strength is your priority, compare Graphic Packaging Holding with companies filtered through a list of solid balance sheet and fundamentals (25 results) to see which ones better fit your criteria.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com