
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Did Backlog Declines Just Shift Meritage Homes (MTH) Investment Narrative?
- Meritage Homes has faced sustained operational pressure, with its backlog declining an average of 27.6% year on year and EPS falling 7.7% annually over five years, alongside a weaker return on invested capital.
- The combination of shrinking order backlog and softer earnings suggests Meritage Homes may be struggling to convert past demand into durable, high returning projects.
- We will now look at how Meritage Homes's weaker backlog trend reshapes the broader investment narrative for the business.
Compare Meritage Homes' recent pressure on backlog and earnings with other builders that screen stronger on fundamentals by scanning our curated list of solid balance sheet and fundamentals (25 results).
Meritage Homes Investment Narrative Recap
For a shareholder in Meritage Homes, the core belief is that its focus on entry level and first move up buyers, combined with quick close spec inventory and cost controls, can turn into steadier orders and healthier gross margins over time. The sharp backlog decline and falling EPS now put that thesis under more pressure and make execution on existing communities more important.
The key near term catalyst is whether Meritage Homes can stabilise order trends without leaning heavily on incentives that drag margins, while still moving inventory quickly. The biggest risk is that affordability headwinds and higher rate sensitivity for its customer base keep backlog weak, which would limit any margin recovery and keep earnings under strain.
With no fresh company specific announcements tied directly to this backlog and EPS deterioration, the most relevant context is the earlier push into faster cycle spec building and structural cost reductions. Those initiatives rely on healthy throughput to matter. When backlog falls an average of 27.6% year on year and EPS declines 7.7% annually, that throughput is exactly what comes under question.
For you as an investor, the link is straightforward. The more Meritage Homes can keep cycle times tight and construction costs contained while still protecting its adjusted home closing gross margin, the more room it has to work through a softer demand patch. If weaker orders persist, the risk is that incentives, lower average selling prices and compressed profit margins become a longer running feature rather than a temporary trade off.
Meritage Homes' current analyst blueprint points to US$6.3b in revenue and US$462.5 million in earnings by 2029. That path assumes 5.6% yearly revenue growth and an earnings increase of about US$133.2 million from US$329.3 million today.
Uncover how Meritage Homes' fair value indicates a 38% potential upside to its current price, which could narrow quickly if Meritage Homes executes more cleanly.
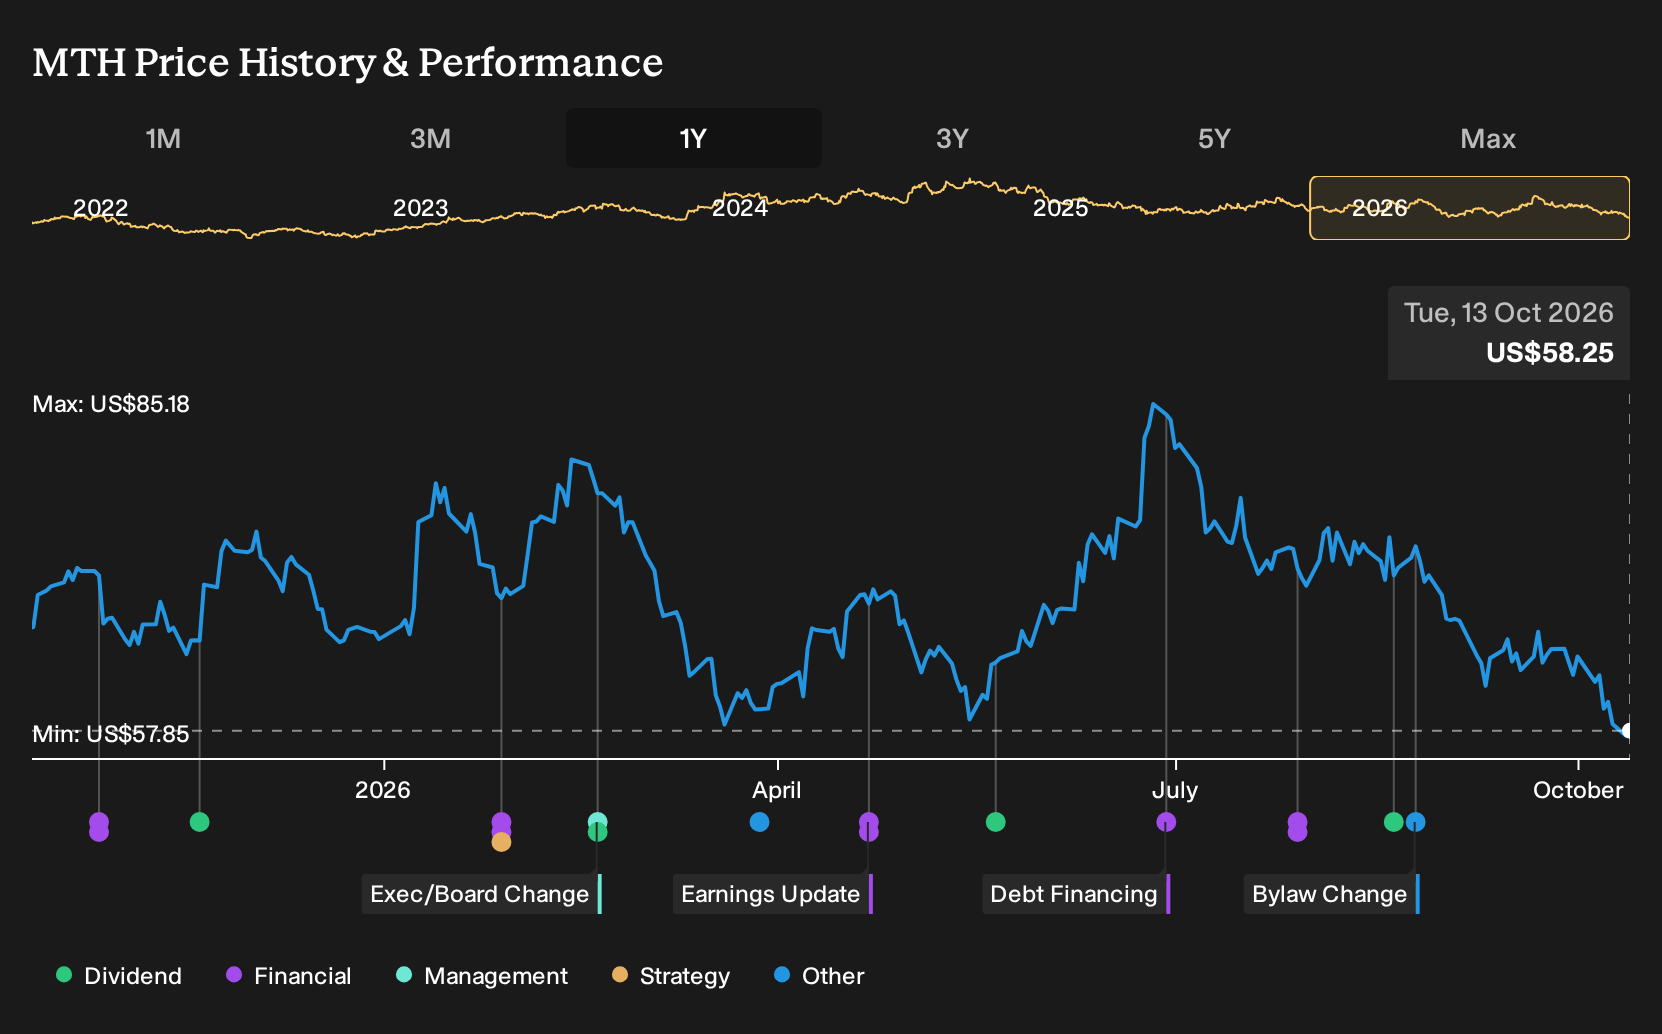
Exploring Other Perspectives
One alternate view on Meritage Homes treats the long slog through higher cost land as the real issue. The most pessimistic analysts were already working off roughly US$6.3b of revenue and about US$476.9 million of earnings by 2029, yet still applied a lower 9.3x P/E. That signals far more caution, and today’s backlog and EPS news could push those narratives even further apart. You are seeing in real time how sharply opinions can diverge. It is worth exploring both sets of assumptions before deciding what this story means for you.
Explore 3 other Meritage Homes fair value estimates, including one that suggests it could be worth just $65.00.
Form Your Own Verdict
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Meritage Homes research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Meritage Homes. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Meritage Homes' overall financial health at a glance.
Looking For More Ideas Beyond Meritage Homes?
Once you have a view on Meritage Homes, it can help to line that opinion up against other opportunities that fit different risk, income and quality profiles. The Simply Wall St Screener is a useful way to do that side by side without getting lost in noise.
- If capital preservation is front of mind, focus on resilience first and see which companies pass the test in our 32 resilient stocks with low risk scores.
- For investors hunting for stronger balance sheets and steadier fundamentals, use the curated list of solid balance sheet and fundamentals (25 results) to spot businesses with financials that may better match your comfort level.
- If you prefer ideas that are less widely followed, broaden your watchlist with a 20 high quality undiscovered gems that combine quality fundamentals with lower market attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com