
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Learn Why The Bull Case For Cytokinetics Stock Could Change Following Phase 3 HCM Data
- Cytokinetics reported new ACACIA-HCM Phase 3 data showing aficamten significantly improved global exercise performance and multiple clinical domains in non-obstructive hypertrophic cardiomyopathy, with no new safety signals identified.
- The breadth of benefit across BEAP-RS domains and plans for a supplemental FDA filing point to a potential expansion of MYQORZO's addressable patient pool and future treatment mix.
- The focus now turns to how Cytokinetics' investment narrative could shift if aficamten's multidomain benefits support a broader label.
Cytokinetics Investment Narrative Recap
Cytokinetics is still largely a single-franchise story, so being a shareholder means believing aficamten can support a broader hypertrophic cardiomyopathy portfolio while Myqorzo builds real prescription depth. The fresh ACACIA-HCM data support that clinical thesis but do not remove the central operational challenge: turning strong trial outcomes into predictable, recurring product revenue.
The near term hinges on execution around the planned Q4 2026 sNDA for non obstructive HCM and ongoing commercialization of Myqorzo. The biggest risk stays the same. High spend, negative equity and dependence on a small set of cardiomyopathy assets leave Cytokinetics sensitive to any regulatory delay or slower than expected uptake.
The clearest tie to today’s story is the October 12 HFSA presentation itself, which expanded on ACACIA-HCM with multidomain BEAP RS data in non obstructive disease. That update feeds directly into the Q4 2026 sNDA plan, because it adds clinically relevant color around symptoms, exercise capacity and biomarkers on top of the original dual primary endpoints.
Operationally, if regulators accept this package as sufficiently consistent and clean on safety, Cytokinetics could move from a single approved HCM setting to two within the same franchise. The flip side is obvious for you as an investor: any surprise around label language, REMS requirements or monitoring expectations could raise complexity, weigh on adoption and keep losses elevated for longer.
Cytokinetics' current analyst narrative points to about US$1.0b in revenue and US$178.9 million in earnings by 2029, built on forecast yearly revenue growth of 114.3%, which implies an earnings swing of roughly US$1.0b from an earnings loss of US$829.6 million today.
Uncover why Cytokinetics' fair value indicates a 75% potential upside to its current price that could narrow quickly.
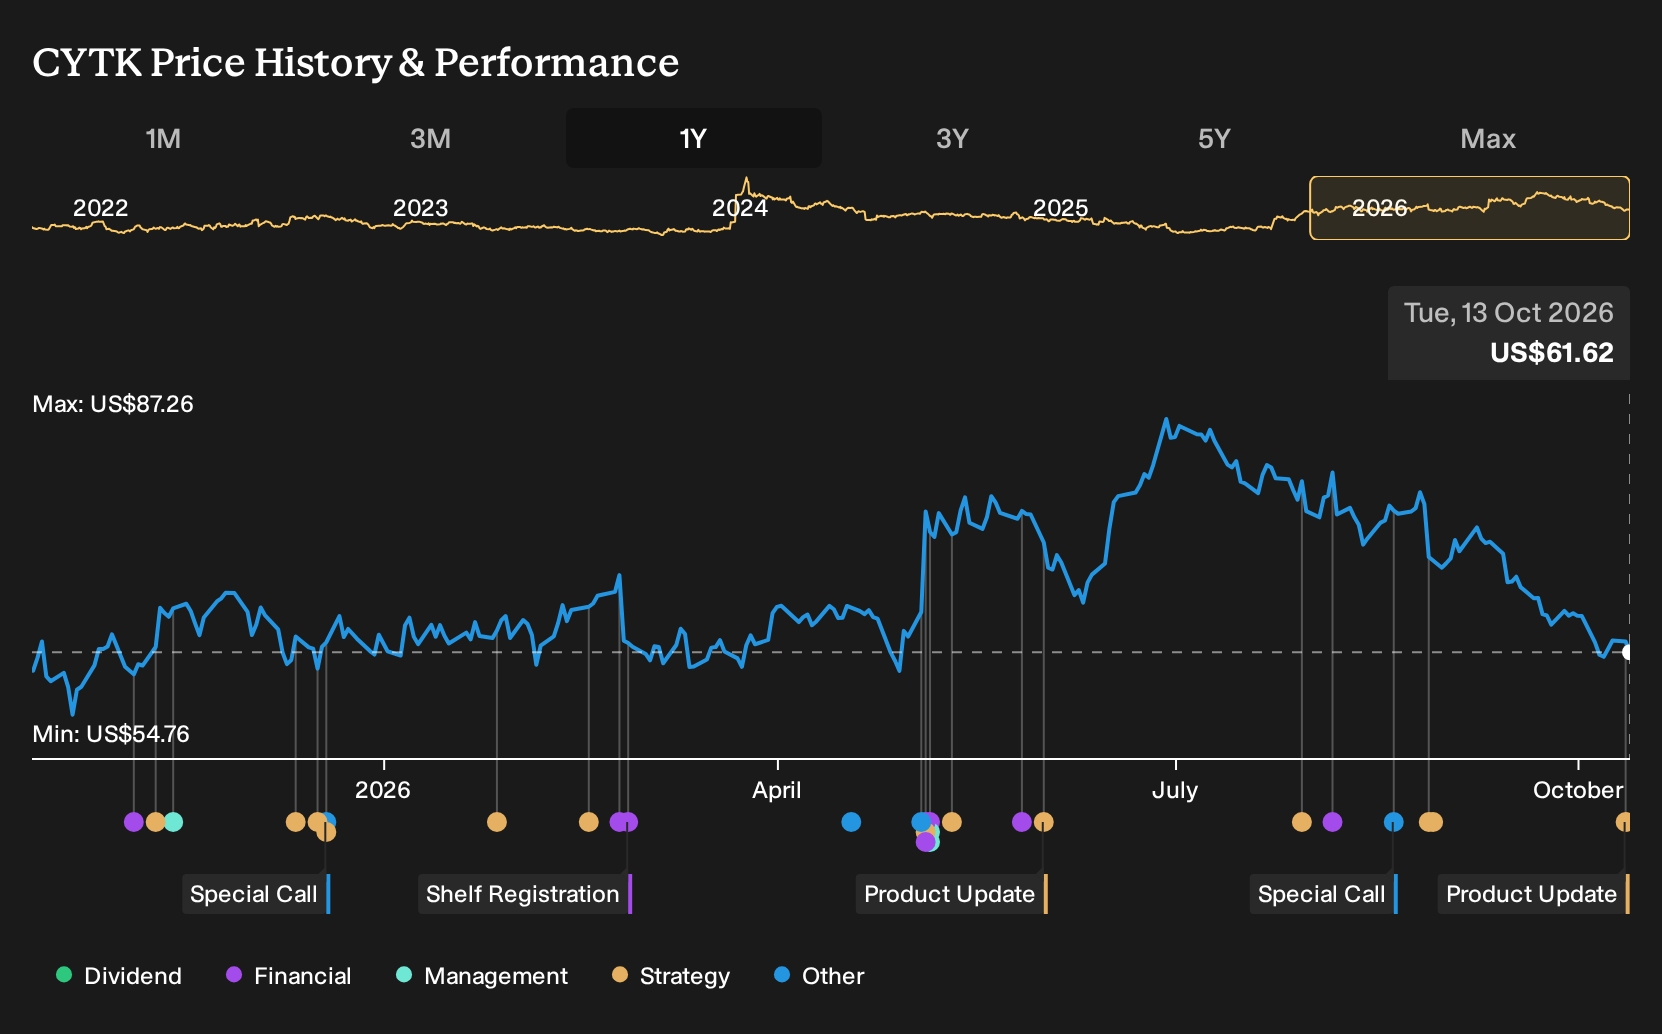
Exploring Other Perspectives
You might see the HFSA data and think label expansion is the whole story, yet the lowest Cytokinetics analysts focus on dilution risk instead. They were working off 3 year share count growth of 7.0% and 2029 earnings of about US$164.5 million. That more cautious setup could shift if today’s results reshape expectations.
Explore 2 other Cytokinetics fair value estimates, including one that suggests it could be worth just $107.80!
The Verdict Is Yours
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Cytokinetics research is our analysis highlighting 3 key rewards and 4 important warning signs that could impact your investment decision.
- See our latest analysis for Cytokinetics. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Cytokinetics' overall financial health at a glance.
Looking For More Ideas Beyond Cytokinetics?
Once you have a view on Cytokinetics, it can help to compare that thesis with other opportunities using the Simply Wall St screener so your portfolio is not built around a single story.
- If you want potential mispriced opportunities with strong underlying quality, start by scanning our hand picked 32 high quality undervalued stocks that pass demanding fundamental checks.
- For income focused investing, balance your research by reviewing a curated set of stocks offering solid yields through our 8 dividend fortresses that prioritise reliable payer profiles.
- When capital preservation matters most, consider companies with sturdier finances by running through the 32 resilient stocks with low risk scores that score well on resilience and balance sheet strength.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com