
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
How Analyst Upgrade Will Impact Sallie Mae Stock Investors
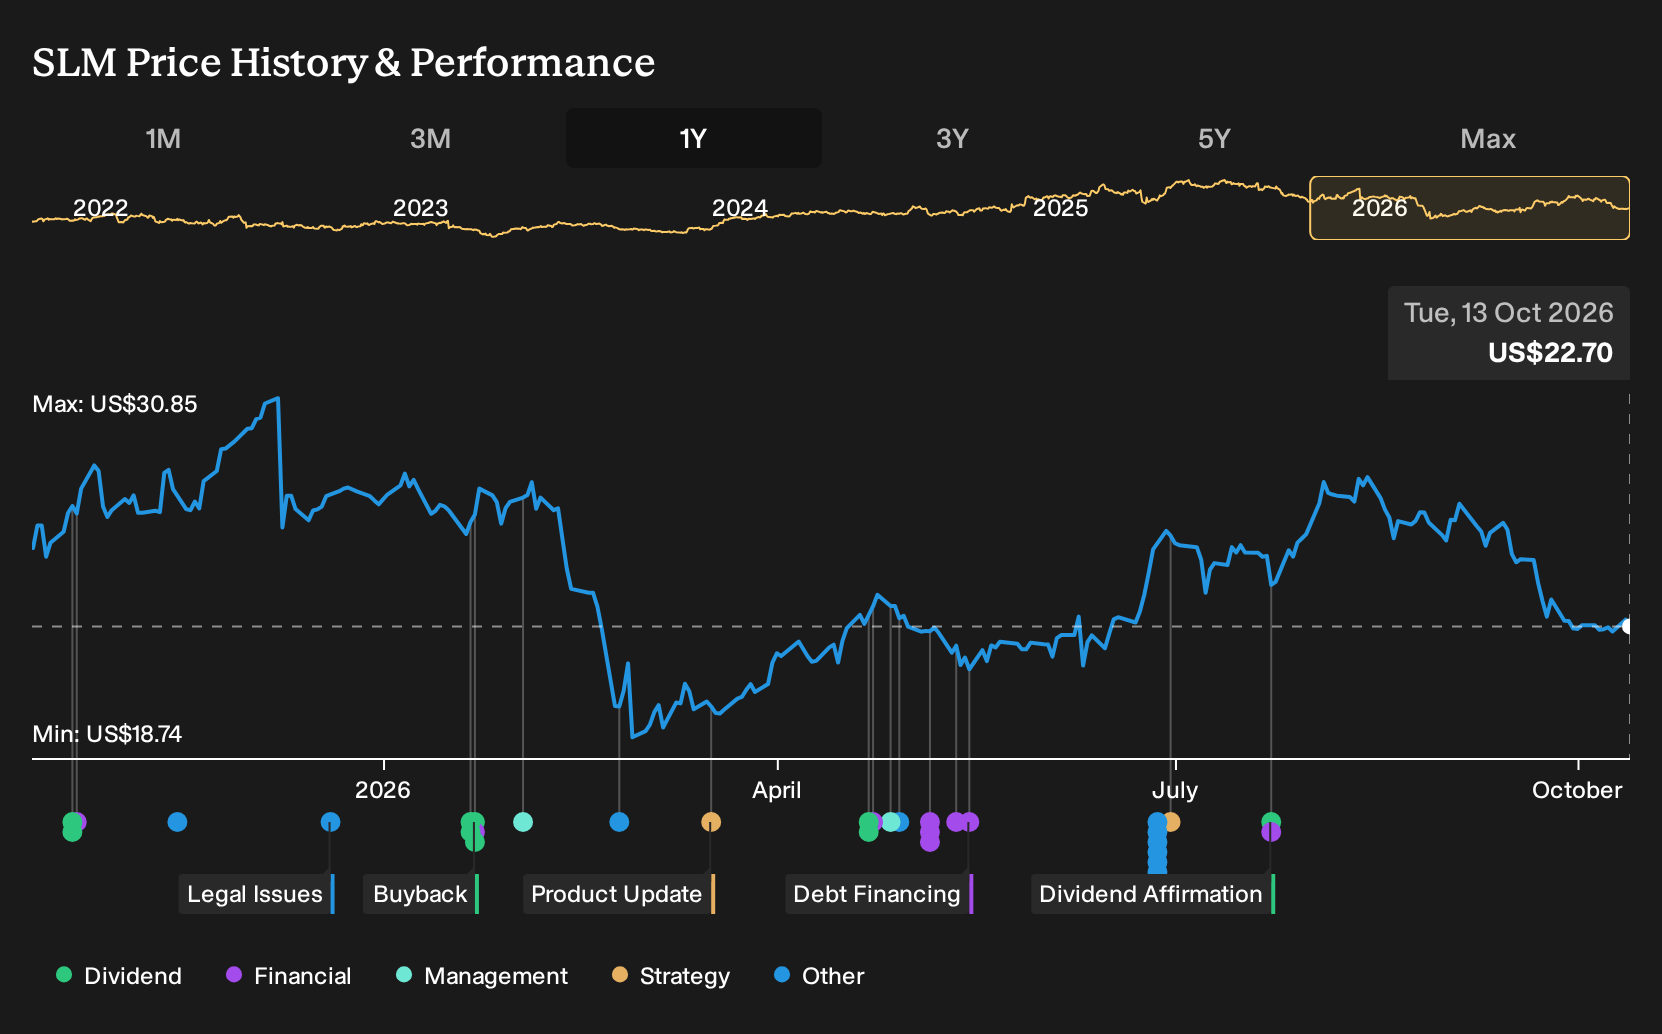
- Morgan Stanley recently upgraded SLM Corporation from Equalweight to Overweight, citing a more constructive view on how its private education lending and capital-light loan sale model are positioned within the current regulatory and funding backdrop.
- The interesting angle for you is how SLM’s execution on private loan partnerships and servicing, rather than the rating change itself, frames the real business test behind this analyst shift.
- We will now examine how SLM’s investment narrative could be influenced by Morgan Stanley’s upgrade and its focus on capital-light loan partnerships.
Scan how analysts are reassessing private lenders like SLM by comparing it with a hand picked 32 high quality undervalued stocks, which may also be priced for a sentiment shift.
SLM Investment Narrative Recap
To own SLM, you need to be comfortable with a private student lender that is trying to turn federal loan reforms into higher originations while leaning harder into a capital light partnership and loan sale model. The Morgan Stanley upgrade does not change that core bet. The near term swing factor remains how quickly those private credit partnerships scale without stressing funding.
The biggest operational threat still sits on the cost and credit side. Net charge offs of US$113 million in Q2 2026 and a full year 2026 expense guide of US$750 million to US$780 million keep pressure on margins. The upgrade does not remove that risk. It instead highlights execution on partnerships and servicing as the main thing to watch.
With no fresh operating announcements tied directly to this Morgan Stanley call, the most important reference point is still SLM management's existing push into private credit partnerships such as the agreement with KKR that carries a US$2b annual flow commitment. Those arrangements are designed to tilt economics toward recurring fees and lower capital intensity.
For you, that is where the upgrade connects back to the story. If SLM can route 30% to 40% of originations through similar vehicles while keeping delinquency, net charge offs and noninterest expenses under tighter control, the partnership and servicing engine becomes the practical catalyst. Missteps on credit quality or operating efficiency would cut straight across that thesis.
SLM's analyst narrative points to revenues of US$1.4b and earnings of US$581.0 million by 2029. That path assumes revenue declines of 5.7% per year and an earnings decrease of US$139.6 million from US$720.6 million today.
Uncover why SLM's fair value indicates a 26% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
The real fork in the road is earnings visibility. While the baseline view sees SLM grinding to about US$581.0 million of profit by 2029, the lowest analysts were pencilling in roughly US$579.8 million on slightly faster revenue declines of 6.2% a year. That cohort is more cautious on the loan sale tilt and may reassess their stance after Morgan Stanley’s upgrade. Use that spread in expectations as a prompt to compare several narratives, not just one.
Explore 2 other SLM fair value estimates, including one that suggests it could be worth just $28.36!
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so trust your own analysis.
- A great starting point for your SLM research is our analysis highlighting 4 key rewards and 4 important warning signs that could impact your investment decision.
- See our latest analysis for SLM. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate SLM's overall financial health at a glance.
Looking For More Investment Ideas Beyond SLM?
Once you have formed a view on SLM, it can help to pressure test that thinking against other businesses with different strengths and risk profiles using the Simply Wall St Screener.
- If you want firms that aim to pair quality fundamentals with what could be mispriced sentiment, take a look at our 20 high quality undiscovered gems that might not be on most investors' radar yet.
- For readers who care most about resilience and capital protection, filter for companies on the 32 resilient stocks with low risk scores to see which ones screen well on stability.
- If balance sheet strength is your first filter before you even consider earnings or valuation, start with this curated list of solid balance sheet and fundamentals (25 results) and then work backward into the details.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com