
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Core Natural Resources (CNR) Gets A Leer South Boost, Is The Upside Already Priced In?
Core Natural Resources (CNR) is back in focus after Q2 2026 results related to a $155 million Leer South insurance settlement, increased shareholder payouts, and new rare earth and defense related partnerships.
Recent price action reflects that mix of good news and lingering questions. The 90 day share price return of 6.18% contrasts with a 30 day share price pullback of 6.08%. At the same time, the 1 year total shareholder return has declined 8.0%, and the 5 year total shareholder return is still very strong at about 3.2x. This pattern suggests that long term holders in Core Natural Resources have been rewarded even as momentum has cooled this year.
Scan how Core Natural Resources compares with other miners adjusting to energy transition and defense demand by reviewing the hand picked 32 best rare earth metal stocks alongside this latest Q2 update.
Core Natural Resources now trades near a year of mixed returns, fresh cash from Leer South, and new rare earth ambitions. Is most of the re rating already in the rear view mirror, or is the bigger upside still ahead?
Most Popular Narrative: 16% Undervalued
Against a last close of $91.54, the most followed valuation narrative for Core Natural Resources points to a fair value of $109.50, which frames Q2 news and the Leer South settlement within a wider cash generation story.
Strong execution on cost efficiencies, flexible market strategy, and shareholder returns are expected to drive margin expansion, stable cash flow, and increased intrinsic value.
See why 26 investors see Core Natural Resources as 16% undervalued.
Result: Fair Value of $109.50 (UNDERVALUED)
Still, the Core Natural Resources story could change if coal demand weakens faster than expected or if regulatory support and export conditions become less favorable.
Find out about the key risks to this Core Natural Resources narrative.
Another View: Multiples Put Pressure On The Core Natural Resources Story
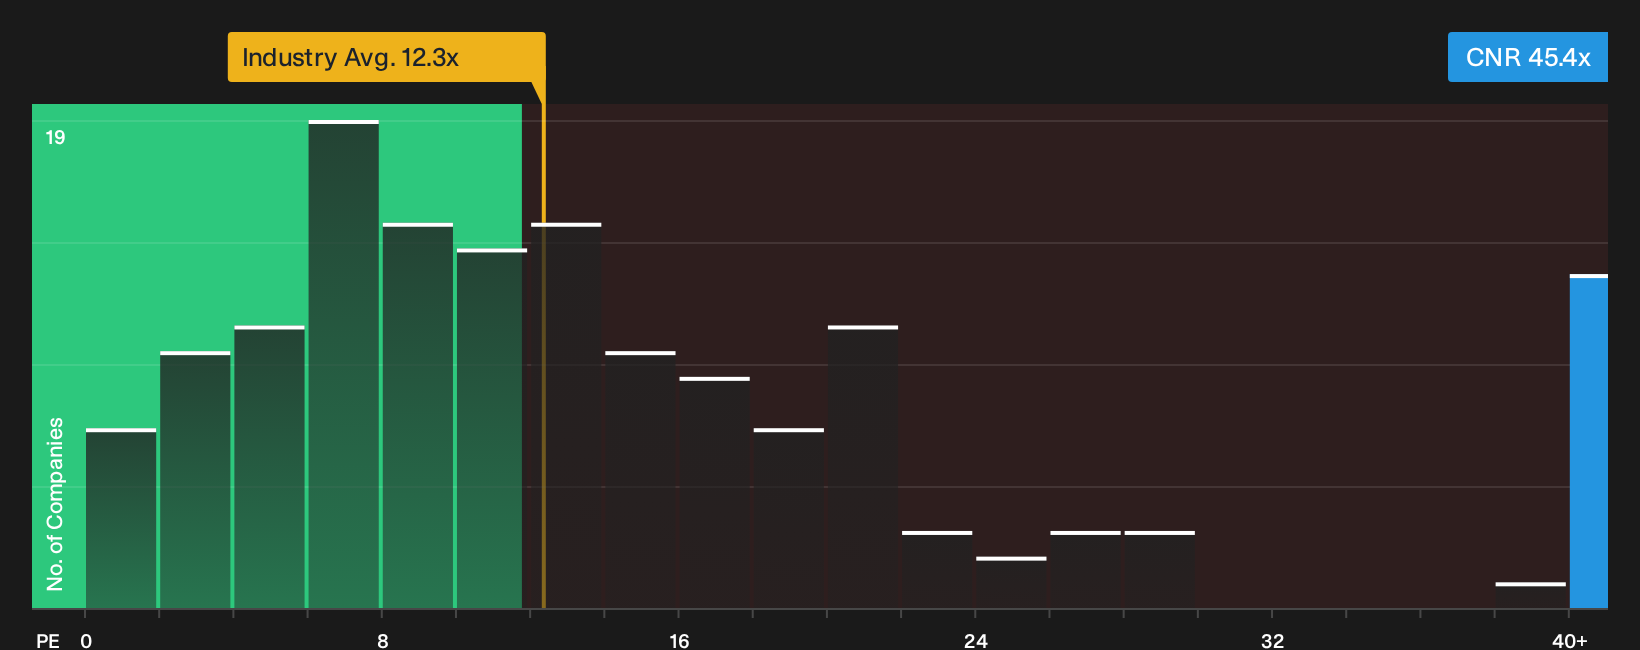
The fair value narrative leans on cash flows, yet on simple earnings multiples Core Natural Resources looks stretched. The stock trades on a P/E of 45.4x, compared with about 12.3x for the wider US Oil and Gas group and 24.6x for close peers, while the fair ratio sits at 25.3x. That gap points to meaningful valuation risk if sentiment cools. Is the cash flow case strong enough to justify paying almost double that fair ratio?
For a closer look at what the current pricing implies, including how this P/E gap lines up against earnings quality and growth, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed feelings on Core Natural Resources so far, or leaning firmly one way? Act while this Q2 story is fresh and stress test both sides of the debate through the 3 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Core Natural Resources?
If Core Natural Resources has sharpened your thinking, use that momentum and scan other opportunities before this earnings season reshapes the opportunity set again.
- Target potential mispricing by reviewing a curated 32 high quality undervalued stocks that already filters for quality alongside attractive entry points.
- Build a steadier income base by shortlisting companies in the 8 dividend fortresses that combine higher yields with fundamental support.
- Reduce portfolio stress by filtering for companies in the 32 resilient stocks with low risk scores that pair resilient balance sheets with lower risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com