
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Toro (TTC) Faces Soft Growth Questions Following Fair Value Upside Narrative
Soft growth triggers closer look at Toro
Recent commentary on Toro (TTC) points to revenue growth running below industrial peers and returns on capital losing steam. This is prompting investors to reassess how durable the company’s core profit engines really are.
Toro’s share price has climbed 22.1% year to date, supported by a 5.6% 30 day share price return. However, the 1 year total shareholder return of 33.5% signals momentum that contrasts with the softer growth and returns on capital story now emerging.
Compare Toro's softer growth profile with a hand-picked 32 high quality undervalued stocks that currently combines stronger fundamentals with more attractive value signals.
After a 33.5% total return over the past year and softer growth signals starting to bite, Toro now looks like a classic test case. Does the current valuation still leave enough upside to justify fresh risk?
Most Popular Narrative: 12% Undervalued
On the most followed view, Toro’s fair value sits at $111 against a last close of $97.88, which puts recent share price strength in context rather than contradicting it. That narrative leans on specific profit drivers and cost actions rather than a vague hope that past returns simply reappear.
Acceleration of the AMP productivity program, which has already surpassed the updated US$125 million run rate savings goal and helped deliver the strongest operating margin in 12 quarters, points to further structural cost benefits that can continue to support higher net margins and earnings power beyond the formal end of the program.
See why 9 investors see Toro as 12% undervalued.
Result: Fair Value of $111 (UNDERVALUED)
Still, Toro’s past deterioration in operating margins and returns, along with relatively modest 3.4% forecast revenue growth, could easily undermine the underpriced upside story.
Find out about the key risks to this Toro narrative.
Another View on Toro’s Valuation
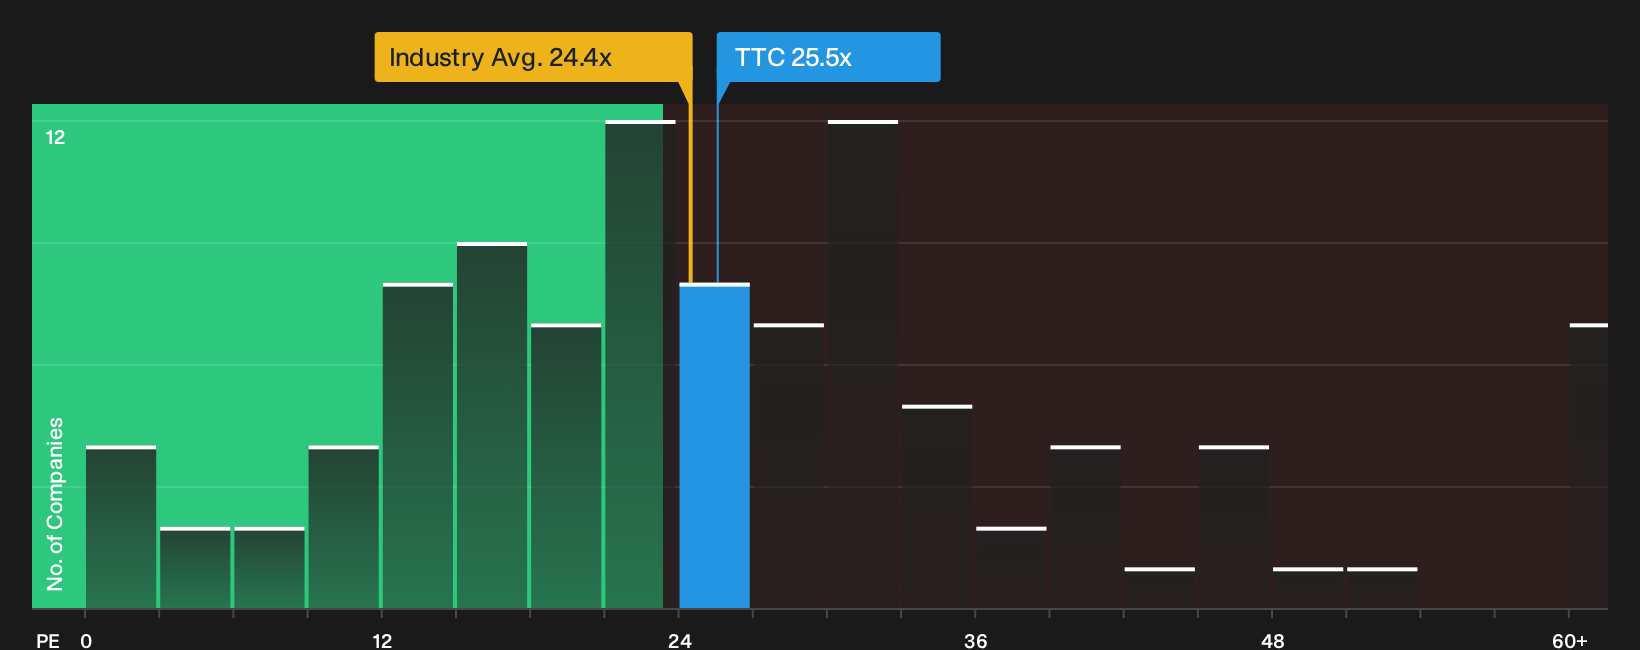
On earnings multiples, Toro looks far tighter. The stock trades on a P/E of 25.5x, slightly above both the US Machinery industry at 24.4x and its own fair ratio of 21.4x. That gap points to valuation risk if sentiment cools before the profit story fully plays out.
See what the numbers say about this price in our valuation breakdown, then ask whether Toro deserves that premium today or if patience is safer for fresh capital. See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals around Toro's growth, profitability and valuation make this a judgment call that data needs to settle. Act while the facts are fresh and weigh both sides of the story by reviewing the full breakdown of 4 key rewards and 1 important warning sign
Looking for more ideas beyond Toro?
Do not stop your research with one ticker. Broaden your watchlist with focused screeners that surface different kinds of opportunities other investors may be missing.
- Target higher income potential by scanning for companies offering robust yields and stable profiles through our 8 dividend fortresses.
- Hunt for quality at a better price by reviewing a curated 32 high quality undervalued stocks backed by stronger fundamentals.
- Strengthen your downside protection by filtering for a 32 resilient stocks with low risk scores that prioritises resilient balance sheets and steadier risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com