
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
How Raised Revenue Guidance At Sanmina (SANM) Has Changed Its Investment Story
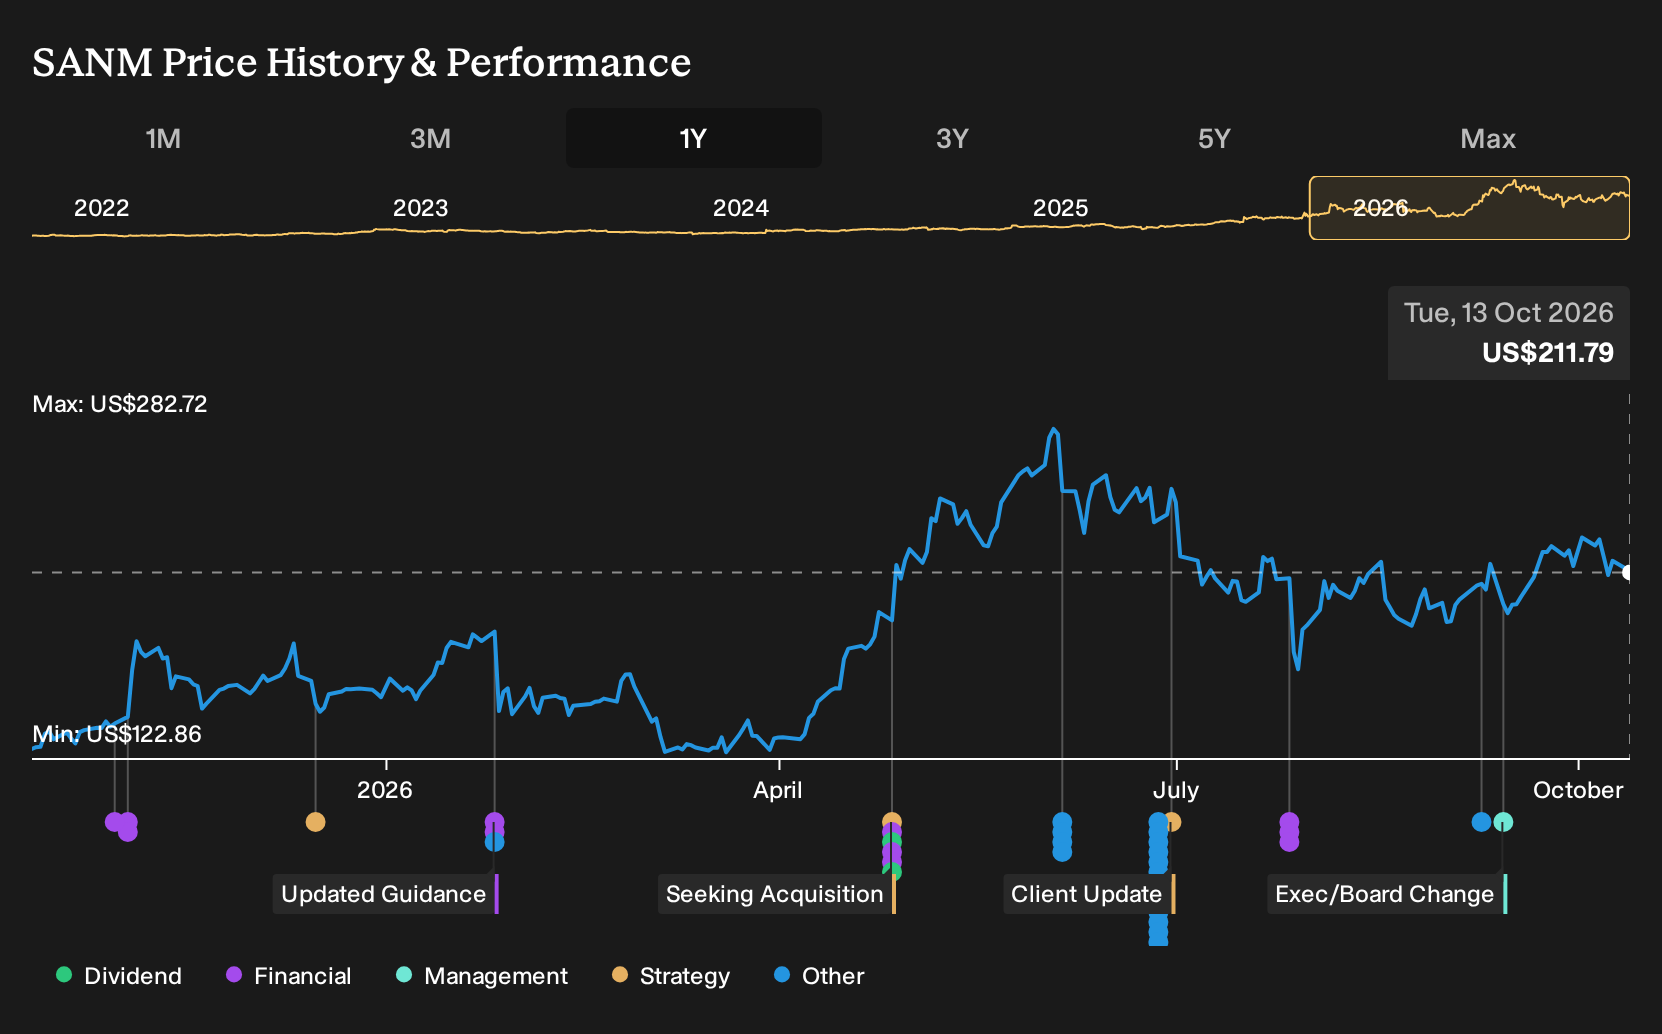
- Sanmina recently raised its fiscal 2026 revenue outlook to US$14.15b at the midpoint and highlighted new automotive electronics programs shifting into full-scale production, while redirecting cash from buybacks toward growth and acquisitions such as ZT Systems.
- The combination of rising automotive program volumes, larger exposure to advanced electronics manufacturing and a tighter share count has sharpened attention on how Sanmina converts these operating shifts into long term earnings power.
- This article reviews how Sanmina's investment narrative is influenced by the raised 2026 revenue guidance and the transition of automotive programs into production.
Scan how Sanmina’s shift toward advanced automotive electronics compares with other manufacturers by running the hand picked 91 robotics and automation stocks alongside this story.
Sanmina Investment Narrative Recap
To own Sanmina today, you need to be comfortable with a manufacturing story that is leaning harder into complex automotive and AI centric electronics at scale. The raised 2026 revenue outlook and automotive programs entering full production point to heavier use of automated plants and quality systems, which could help efficiency but also amplifies execution risk.
The near term swing factor is whether those new automotive and accelerated compute programs ramp as expected and support the current level of working capital and capex. The biggest risk remains a demand slowdown or delay that leaves Sanmina carrying high inventory, pressuring cash flow, margins and eventually valuation.
The clearest recent marker for this thesis is management lifting fiscal 2026 revenue guidance to US$14.15b at the midpoint, while redirecting cash from buybacks toward ZT Systems and other growth projects. That move ties your Sanmina view closely to how well the company can integrate ZT and support large AI rack and automotive volumes without stretching the balance sheet.
If those ramps track forecasts, the larger scale in communication networks, cloud and AI infrastructure, plus automotive electronics, could reinforce analyst expectations for strong earnings growth. If they do not, investors face a combination of high inventory, elevated valuation metrics and intense competition from Jabil and Flex in next generation vehicle and electrification programs.
Sanmina's current analyst story points to US$20.6b of revenue and US$792.1 million of earnings by 2029, built on an assumed 17.2% yearly revenue growth rate and an earnings step up of about US$484 million from the US$308.1 million reported today.
Uncover how Sanmina's fair value indicates a 23% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
Some bullish analysts focus on a different catalyst for Sanmina. They lean hardest into AI and cloud exposure, not automotive, and before this guidance update were already sketching out about US$21.8b of revenue and US$900.5 million of earnings by 2029. That is a far more optimistic script. Use this jump in outlook as a cue to compare several narratives, and then decide which assumptions feel realistic to you.
Explore 2 other Sanmina fair value estimates, including one that suggests as much as 24% potential price appreciation from the current level.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Sanmina research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Sanmina. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Sanmina's overall financial health at a glance.
Looking for more investment ideas beyond Sanmina?
Sanmina might be front of mind after this guidance update, but your portfolio benefit often comes from lining up a few different angles at once. The Simply Wall St Screener can help you quickly filter for other companies that match the type of risk and balance sheet profile you want to pair with this stock.
- For sturdier balance sheets and cleaner fundamentals, review the list of solid balance sheet and fundamentals (25 results) that could complement a higher volatility position like Sanmina.
- If you want potential mispricing opportunities, scan the 32 high quality undervalued stocks that ranks companies on quality and valuation in a single pass.
- Income focused investors can balance growth stories like Sanmina with reliable cash returns by checking the 8 dividend fortresses that screens for higher yielding payers.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com