
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Earnings Beat Might Change The Case For Investing In Expeditors International of Washington (EXPD)
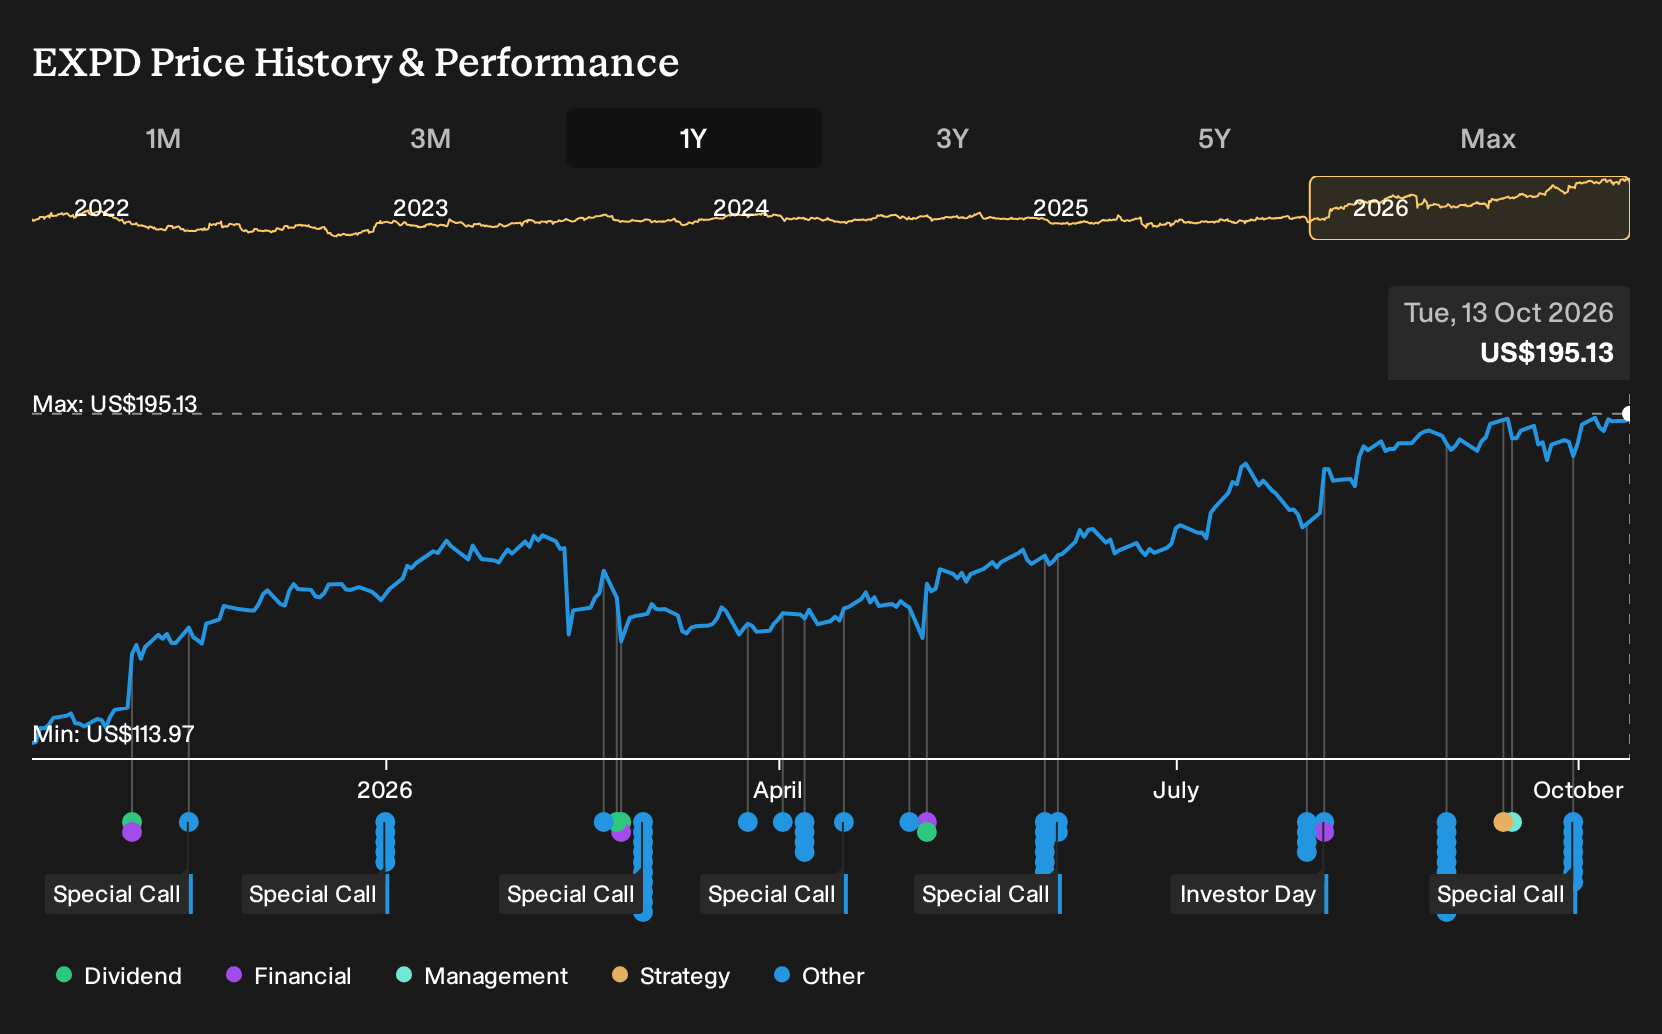
- Expeditors International of Washington recently hosted a series of special calls on quality management, compliance, Canadian distribution, Incoterms and denied party screening, reflecting management's focus on operational discipline and risk control across its global logistics offering.
- The emphasis on topics like North American trade compliance and Incoterms risk sharing highlights how Expeditors International of Washington is leaning into higher value advisory and process driven services that can deepen customer relationships and support its fee based logistics model.
- We will now look at how Expeditors International of Washington's recent earnings results may reshape its investment narrative for investors.
Scan logistics and compliance focused peers showing similar momentum by reviewing our curated list of list of solid balance sheet and fundamentals (25 results) alongside Expeditors International of Washington.
Expeditors International of Washington Investment Narrative Recap
To own Expeditors International of Washington, you need to believe the logistics group can keep pushing toward higher value, fee based services while holding onto its execution in airfreight, customs brokerage and critical logistics. The recent special calls on quality, Incoterms and compliance look additive to that story, but do not materially change the near term setup.
The immediate swing factor still sits in freight and brokerage volumes after the recent 14% airfreight volume move and 32% revenue move in Q2 2026. The biggest risk is that any cooling in those flows or disruption from technology restructuring hits earnings just as the stock trades on a premium P/E.
The session that feels most relevant right now is “North American Trade Outlook, Key Customs & Compliance Developments for U.S. Importers.” That topic goes straight to Expeditors International of Washington’s customs brokerage and compliance work, which has been an important support for fee based income as trade rules stay complex.
For you as a shareholder, that focus ties directly into the main catalysts. Growth in customs and refund processing, the build out of Critical Logistics hubs and heavier use of AI across these workflows depend on tight compliance and documentation. Stronger execution here can support productivity and help offset any softness in freight driven revenue.
Expeditors International of Washington's current analyst script points to revenues of $13.3b and earnings of $1.0b by 2029, based on a 3.5% yearly revenue growth assumption and an earnings increase of about $81.2m from the current $918.8m level.
Uncover why Expeditors International of Washington's fair value indicates a 9% potential downside to its current price, which leaves little room for error.
Exploring Other Perspectives
Another angle many readers are exploring focuses on Expeditors International of Washington’s compliance services as a growth catalyst. The most optimistic analysts were already modeling revenue of about $14.8b and earnings of $1.2b by 2029 before these quality and denied party screening calls. You could see those forecasts shift if this compliance push proves more powerful, or less powerful, than expected.
Explore 2 other Expeditors International of Washington fair value estimates, including one estimate that values it at up to $193.47.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Expeditors International of Washington research is our analysis highlighting 1 key reward that could impact your investment decision.
- See our latest analysis for Expeditors International of Washington. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Expeditors International of Washington's overall financial health at a glance.
Looking For More Investment Ideas Beyond Expeditors International of Washington?
If the Expeditors International of Washington story has sharpened your thinking but you want a broader watchlist, the Simply Wall St Screener can help you line up other candidates that match your risk tolerance and income goals.
- For investors who want potential mispricings with solid fundamentals, start with a focused set of 30 high quality undervalued stocks that may warrant a closer look on your radar.
- If capital preservation ranks high on your checklist, concentrate on a 31 resilient stocks with low risk scores that might better fit a steadier approach.
- When you want quality operations without stretching on leverage, build out your watchlist from a list of solid balance sheet and fundamentals (25 results) to sit alongside Expeditors International of Washington in your research pipeline.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com