
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
3 Bank Stocks Investors Are Watching After Big US Bank Earnings
Big U.S. banks just reminded markets how powerful their earnings engines can be, with higher profits setting a confident tone while fresh warnings on inflation, rates, and asset prices keep everyone on edge. That mix of strength and stress creates a live test for investors who do not want to miss where capital might quietly be repositioning. This article walks through 3 large bank stocks that screens suggest could be positively exposed to the latest news shock, and explains why their stories matter now.
The three banks highlighted next are only a starter set, and the full screen turns up 21 more large U.S. diversified franchises with equally compelling stories that are not covered here. If you want to identify your own highest conviction ideas from that wider group, head straight into the U.S. Large-Cap Diversified Banks screener
CVB Financial (CVBF)
CVB Financial slots into this large cap diversified banks screen as a regional lender deeply tied to everyday U.S. business activity, and its recent expansion move has turned what used to be a compact California franchise into something much more ambitious.
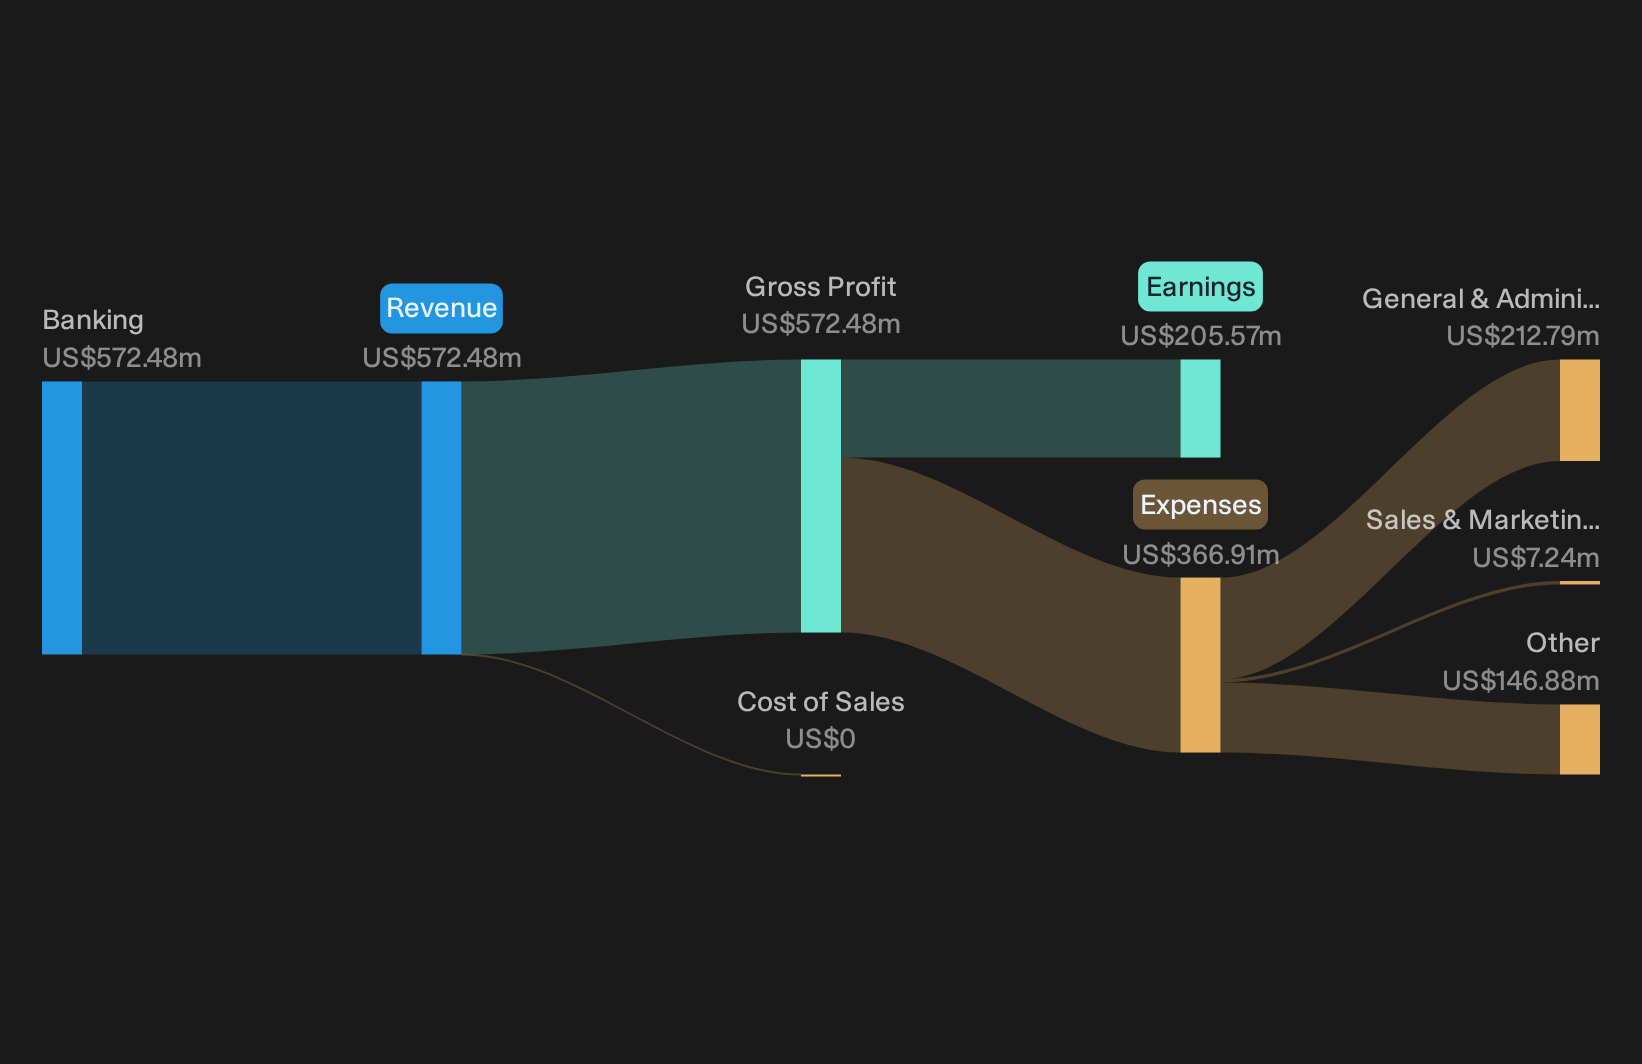
CVB Financial runs Citizens Business Bank, a California based lender focused on small and mid sized businesses, individuals, and municipalities within the broader U.S. large cap diversified banks universe. It generates about US$572 million of banking revenue and carries a market value near US$3.8b.
"Successful integration of Heritage Commerce, which lifted CVB Financial’s assets to about US$21.2b along with US$3.15b of loans and US$4.75b of deposits, creates a larger, statewide franchise that can support higher revenue and earnings from a broader California customer base."
What really moves the needle for CVB Financial now is how one less visible constraint shapes future pricing power and profit margins across that bigger balance sheet.
That quiet constraint is exactly what the full narrative unpacks, so read the full narrative for CVB Financial to see how CVB Financial’s pricing power story could be evolving.
Credicorp (BAP)
Credicorp brings a different flavor to this large cap diversified banks screen, giving you a Peru led multi country financial group with universal banking, insurance, pensions, microfinance, and investment services built around Banco de Crédito del Perú as its main engine.
Credicorp generates most of its PEN 23.3b banking and financial income from Universal Banking at Banco de Crédito del Perú at about PEN 15.4b, with additional contributions from Pacífico Seguros at PEN 1.8b, Mibanco microfinance at PEN 2.1b, and a roughly PEN 1.2b investment management and advisory arm, and the stock carries a market value near US$30.3b.
"Expansion of Credicorp’s digital financial services like Yape is now tied to a much larger base of more than 16 million monthly active users who transact frequently and already contribute close to 10% of risk adjusted revenues, with further product roll out and higher revenue per user potentially supporting fee income and earnings."
The key issue to watch is how one quiet pressure on profitability evolves if growth in this wider Latin American footprint continues.
If that pressure point on profitability is what you are watching, read the full narrative for Credicorp to see how Credicorp’s earnings mix could be quietly shifting.

Bancorp (TBBK)
The Bancorp gives this large cap diversified banks screen a different angle by tying traditional deposit and lending products to embedded finance and fintech programs that plug directly into U.S. consumer and business activity.
The Bancorp runs a U.S. focused bank that supports everyday deposit accounts as well as fintech partners, with about US$263 million of revenue from Fintech, US$103 million from Real Estate Bridge Lending, US$68 million from Commercial activity, US$51 million from Corporate, and US$47 million from Institutional Banking, and the stock carries a market value near US$2 billion.
"Chime announced it would buy Stride Bank for $590 million in cash. The next trading day, The Bancorp fell 22.33%, from $64.41 to $50.03."
What matters next is how a single shifting partnership ripple could reshape the profitability profile investors currently see in The Bancorp.
To see how that partnership risk could be masking other forces around The Bancorp’s earnings engine, read the full narrative for Bancorp for what the market may be missing.

Seeking Alternatives Before The Crowd?
Fresh ideas often move first. Breakout trends, quiet momentum, and under the radar stories can be recognized late once prices start moving sharply. Scan these curated sets now to evaluate opportunities at an earlier stage.
- Target consistent income while payout resilience still appears overlooked by studying a focused group of high yield candidates via the 8 dividend fortresses.
- Identify potential future category leaders by tracking fast growing enablers of artificial intelligence through the curated 92 AI infrastructure stocks.
- Review infrastructure suppliers that may benefit from electrification and grid upgrades by using the specialist 43 power grid technology and infrastructure stocks.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com