
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Kulicke And Soffa Industries (KLIC) Could Be 17% Undervalued Before Its Investor Summit
Kulicke and Soffa Industries conference appearance puts investor focus on fundamentals
Kulicke and Soffa Industries (KLIC) is set to present at the 18th Annual CEO Investor Summit 2026 on October 13 in San Francisco, drawing fresh attention to its semiconductor assembly equipment business.
The upcoming conference slot comes as the shares recently closed at US$88.39 and posted mixed short term returns, including a decline over the past week but a gain over the past month.
Over the past year, Kulicke and Soffa Industries has seen strong momentum, with the share price up 82.81% year to date and a 1 year total shareholder return of 123.41%. However, a 7 day share price decline of 10.47% signals some profit taking ahead of the upcoming investor summit.
Look beyond Kulicke and Soffa Industries and explore other semiconductor companies that are demonstrating strong momentum and financial resilience with our curated 92 AI infrastructure stocks
Kulicke and Soffa Industries has a long-established role in chip assembly gear and a share price that has surged this year. After the recent pullback, does that strength still line up with what you are paying today?
Most Popular Narrative: 17% Undervalued
The most followed valuation narrative puts Kulicke and Soffa Industries at a fair value of $106.67, compared with the latest close at $88.39. This sets up an earnings power debate around its Advanced Solutions push.
Management is preparing for a production ramp in Fluxless thermocompression and vertical wire into fiscal 2026, yet both are still in early phases with first HBM system shipments and initial vertical wire qualifications. Any delay or slower adoption in high bandwidth memory or on device AI could pressure the anticipated contribution to revenue growth and limit margin expansion.
See why 6 investors see Kulicke and Soffa Industries as 17% undervalued.
This storyline uses a discount rate of 10.85% and assumes revenue growth of roughly 22.8% a year and a profit margin near 28.4%. It also relies on earnings reaching about $500.1m by 2029 and the market being willing to pay a P/E of 15.4x on those earnings, which is lower than the current industry figure referenced in the narrative.
Those inputs combine to a fair value of $106.67, around 17% above the recent share price. However, they also incorporate meaningful execution risk in thermocompression, vertical wire and power semiconductor assembly. If the ramp in those areas is slower or more uneven than projected, the earnings and margin profile underpinning that fair value could look ambitious.
Result: Fair Value of $106.67 (UNDERVALUED)
Still, this hinges on thermocompression and vertical wire gaining traction as planned, and on advanced dispense and APS orders turning current enthusiasm into sustained earnings power.
Find out about the key risks to this Kulicke and Soffa Industries narrative.
Another View: Kulicke and Soffa Industries through future cash flows
The first story frames Kulicke and Soffa Industries as roughly 17% below a fair value of $106.67 based on analyst earnings and multiples. A second lens, the SWS DCF model for future cash flows, points to a value of about $49.08 instead, which signals a very different risk profile. Which narrative matches your own expectations for how and when cash actually turns up?
Look into how the Look into how the SWS DCF model arrives at its fair value.
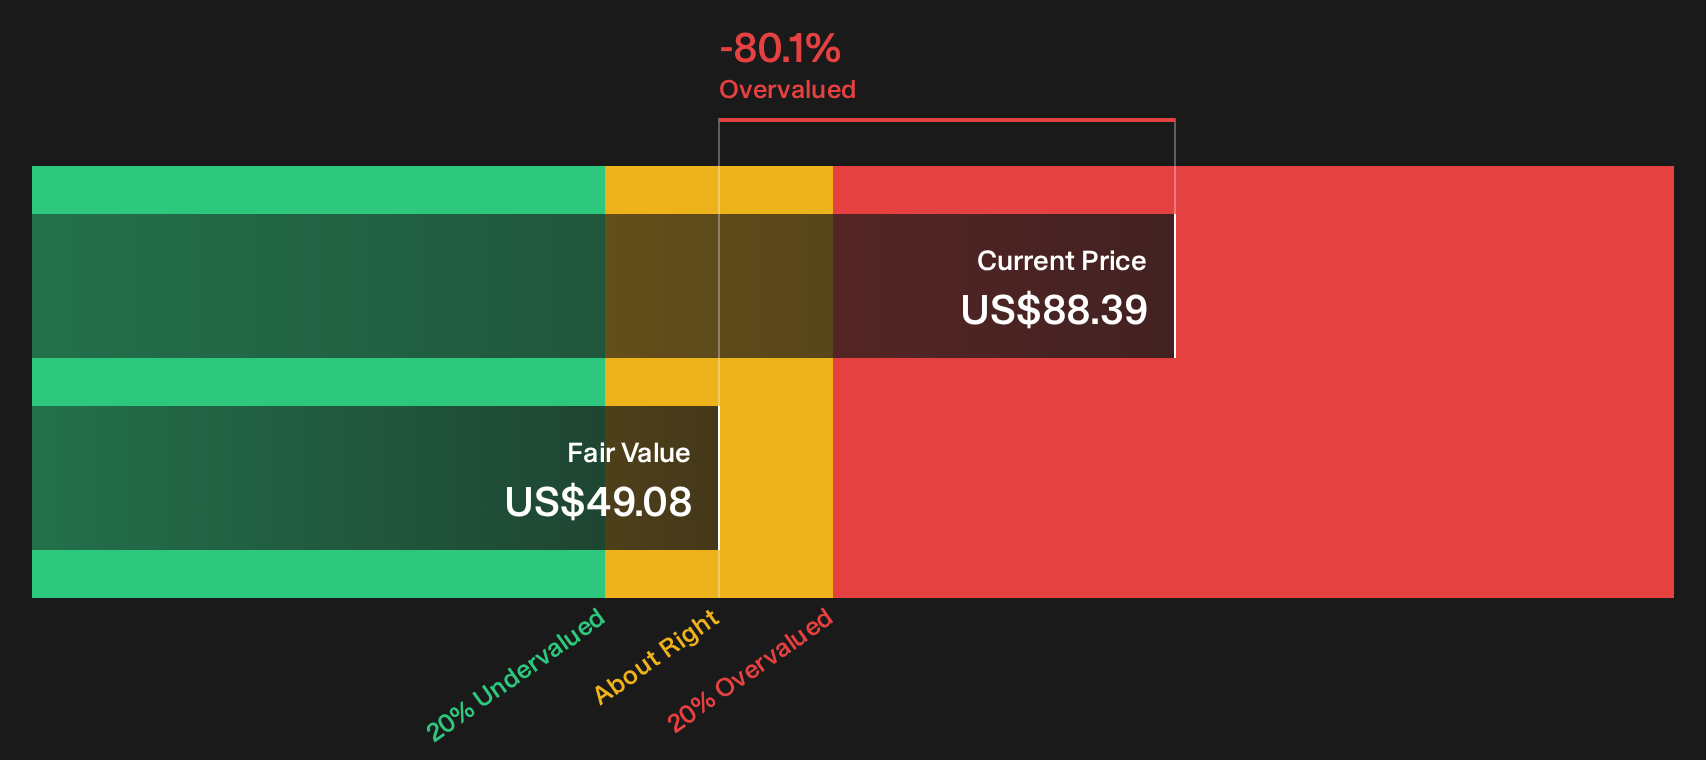
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Kulicke and Soffa Industries for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 29 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals on Kulicke and Soffa Industries so far. If the blend of risk and reward feels finely balanced, move quickly to check the underlying data and stress test your own thesis using our breakdown of 4 key rewards and 1 important warning sign
Looking for more Kulicke and Soffa Industries investment ideas?
If Kulicke and Soffa Industries has sharpened your focus, do not stop here. Cast a wider net now so you are not reacting after the best ideas move.
- Target resilient balance sheets and steadier sleep at night by scanning a curated list of solid balance sheet and fundamentals (25 results) that filters for financial strength and durable fundamentals.
- Hunt for mispriced quality by using the purpose built 29 high quality undervalued stocks to surface businesses where fundamentals and current prices look out of sync.
- Lock in potential income streams by reviewing the 8 dividend fortresses that highlights higher yielding payouts with a focus on stability and consistency.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com