
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
How Investors Are Reacting To PG&E (PCG) Wildfire Sensor Rollout
- PG&E and Itron expanded their collaboration to roll out grid edge sensing devices across high fire risk parts of California, using real time fault detection to support wildfire risk reduction and grid reliability, with plans to scale deployments significantly by 2030.
- The project highlights how PG&E is tying wildfire mitigation directly to grid operations, using granular data from thousands of field devices to inform maintenance priorities, outage response, and long term investment planning.
- We will now look at how PG&E's wildfire focused grid edge rollout with Itron could influence the utility's long term investment narrative.
Scan PG&E's wildfire and grid resilience theme across the wider market by checking hand picked 43 power grid technology and infrastructure stocks that could be repositioning critical infrastructure for the next phase of electrification.
PG&E Investment Narrative Recap
To own PG&E, you need to believe the utility can keep tightening wildfire risk while funding heavy grid investment and serving rising electricity demand from data centers and electrification. The near term story still revolves around execution on safety, regulatory trust, and cost control, all while returns on that growing rate base remain recoverable.
The biggest short term catalyst is operational performance that supports constructive decisions on wildfire cost recovery and future capital plans. The key risk is still an adverse regulatory or legislative shift on wildfire liability or allowed returns. The Itron partnership looks helpful for risk management but does not fundamentally change that equation on its own.
Among recent developments, the Itron grid edge rollout stands out because it ties directly into PG&E’s core risk and opportunity. Deploying fault sensing devices in high fire threat areas is about more granular visibility, faster response, and clearer evidence when the utility seeks approval for wildfire mitigation spend.
For you as a shareholder, the relevance is simple. Better data quality can support PG&E’s case that wildfire investments are prudent, that outages are being handled more effectively, and that future grid upgrades to serve large data center and electrification load should sit inside an expanding, defensible rate base. Execution on this rollout will be watched closely against those catalysts.
PG&E's analyst narrative points to revenues of US$28.6b and earnings of US$4.5b by 2029, built on assumed 3.4% yearly revenue growth and an earnings increase of about US$1.4b from US$3.1b today.
Uncover why PG&E's fair value indicates a 46% potential upside to its current price before rising expectations compress that discount.
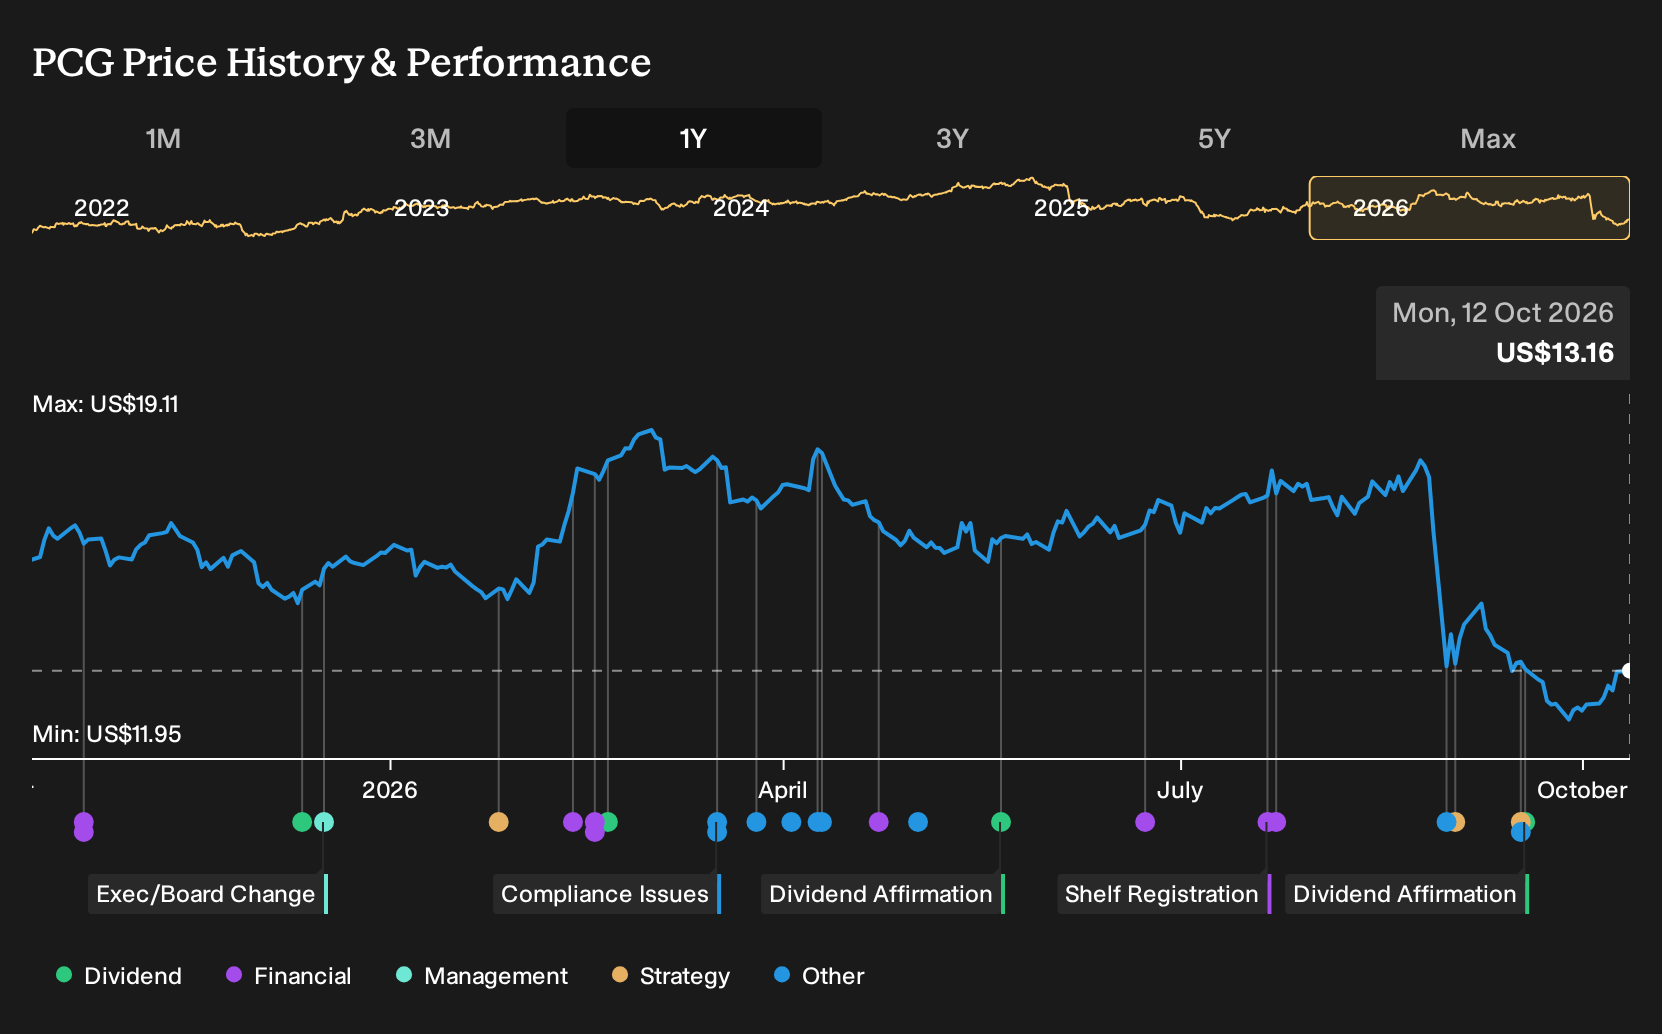
Exploring Other Perspectives
One alternate view puts wildfire legislation at the center of the PG&E story. The most optimistic analysts built their pre news models on SB 254 delivering a durable liability framework and funding PG&E’s US$73b capital plan, with revenue reaching about US$30.3b and earnings near US$4.9b by 2029. This grid edge rollout could prompt those expectations to shift in either direction, so treat it as a cue to compare several competing forecasts, not a final answer.
Explore 2 other PG&E fair value estimates, including one that suggests there may be as much as 46% upside from the current price.
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your PG&E research is our analysis highlighting 4 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for PG&E. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate PG&E's overall financial health at a glance.
Looking for more investment ideas beyond PG&E?
If the PG&E story has sharpened your focus on risk, resilience, and long term capital planning, it can be useful to compare that thesis with other opportunities using the Simply Wall St Screener.
- If you want a starting point for quality at a reasonable price, scan a curated set of 29 high quality undervalued stocks that combine fundamentals with a potential valuation gap.
- If capital preservation ranks high on your list, narrow your search to a 31 resilient stocks with low risk scores that may align better with a more defensive approach.
- If you are hunting for less crowded ideas, filter the market using a 20 high quality undiscovered gems that focuses on strong business profiles which may not yet be widely followed.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com