
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Everpure (P) Stock Could Be Undervalued On Current Sales Levels
Everpure has been on a remarkable run in recent years, and the jump in its share price now puts a spotlight on what investors are really paying for in terms of its sales. With the company in the news for new data management features aimed at production AI, the question is whether the current valuation still lines up with the revenue it generates today.
- Over the past 5 years, Everpure has delivered a very large share price gain, which puts a lot of weight on the assumption that its sales profile can justify such a move.
- The new enterprise data management capabilities for production AI can support expectations for more software usage tied to live data, which may influence how investors weigh future sales against the current price tag.
- The analysts covering Everpure have run their own numbers. See what analysts think Everpure's shares could be worth.
The stock's next move may depend on whether Everpure's current price is supported by its sales when judged against the Fair Ratio benchmark.
To test whether Everpure's AI-fueled story and current price line up with its sales, it helps to compare against a wider group of 92 AI infrastructure stocks
Is Everpure Still Cheap on Sales?
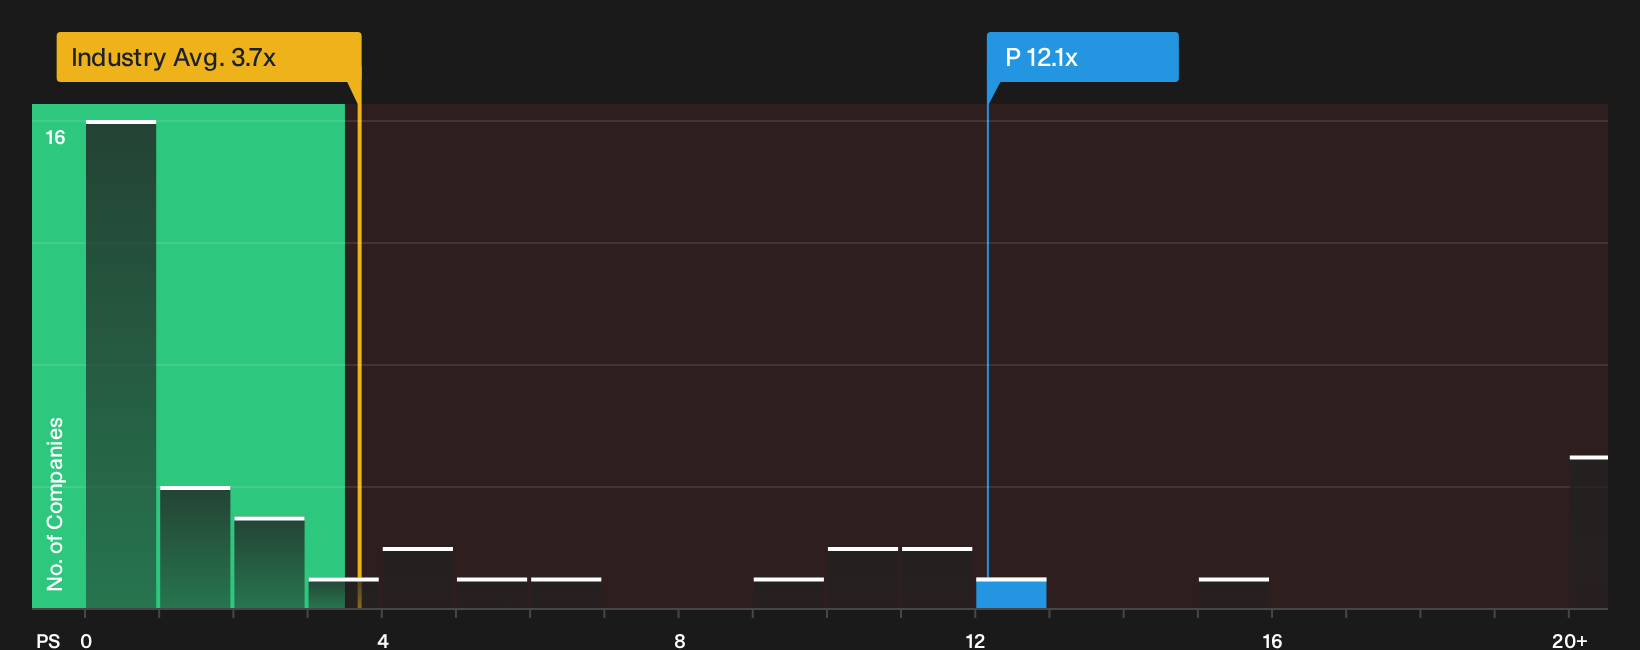
P/S tends to fit Everpure because investors are focused on what they are paying for each dollar of top line in a software style business. The current P/S multiple sits at 12.1x, which is well above the broader Tech industry average of 3.7x and also ahead of the peer group at 5.1x. That signals the market is already attaching a rich tag to Everpure’s existing revenue base compared with many other listed technology firms.
Fair Ratio, which estimates the kind of P/S you might expect once Everpure’s growth profile, profitability, size and risk are taken into account, sits above the current market figure, so the shares screen as undervalued on this lens. Because the new production AI data management launch gives Everpure a more visible product angle, the gap between the going P/S and this tailored benchmark suggests investors are not fully pricing in what the business model could support on sales. Explore the numbers behind Everpure's P/S valuation.
The Everpure Narrative: What Would Justify Today's Price?
Everpure’s valuation puzzle only really makes sense once you spell out the future it implies. Simply Wall St Narratives on the Community page do exactly that by linking each scenario to a clear view on where Everpure's growth, margins and risk profile might head. This gives you concrete assumptions you can revisit as new results, guidance and competitive data arrive.
The Everpure community is split between one group that sees more upside left and another that thinks expectations already bake in a lot of good news.
Bull case: 14% undervalued
"The market is pricing Everpure as an enterprise storage company, that is the wrong category. Once two or three analysts figure out what is actually happening…"
Discover why this Narrative puts Everpure at 14% undervalued.
Bear case: 7% overvalued
"Heavy focus on traditional products and uncertain cloud transition, combined with rising competition and unpredictable demand, threaten recurring revenue growth and margin stability…"
Explore why this Narrative puts Everpure at 7% overvalued.
One more Everpure check that sits beside the price tag
There is a final cross-check that belongs next to the current multiples. It is how professional coverage maps out where this business could be a few years from now and how that compares with today’s set up. Explore where analysts expect Everpure to be in a few years.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com