
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Is Hecla Mining (HL) Undervalued Following Record Lucky Friday Output And Lower 2026 Costs?
Record quarter reshapes Hecla Mining story
Hecla Mining (HL) just reported a record quarter at its Lucky Friday operation, alongside lower silver cost guidance for 2026 and full redemption of its senior notes, leaving the miner with a sizable cash cushion.
The recent Lucky Friday milestone lands against a mixed price backdrop for Hecla Mining. The 1 month share price return is down 14.86%, even though the 3 month share price return is up 8.65%, while 1 year total shareholder return sits at 25.03%. This suggests that long term holders have been rewarded even as shorter term momentum has cooled.
Scan beyond Hecla Mining and compare this quarter's momentum with 10 top silver producer stocks, which are also leaning on production strength and cost discipline in the precious metals space.
Hecla Mining now combines record production, lower future cost guidance and a clean balance sheet. The real question is whether that stronger setup is already fully reflected in the US$16.84 share price.
Most Popular Narrative: 27% Undervalued
Hecla Mining's most followed valuation narrative pegs fair value at $22.98, well above the recent $16.84 close, which puts the latest Lucky Friday record into a much bigger earnings and cash flow context.
The company's disciplined production ramp-up at Keno Hill targeting a sustainable throughput of 440 tonnes per day by 2028, alongside proven high-return economics even at conservative silver price levels, is presented as setting the stage for steady long-term free cash flow and earnings growth as the mine achieves scale.
See why 65 investors see Hecla Mining as 27% undervalued.
On this view, Hecla Mining screens as materially undervalued relative to that $22.98 fair value estimate, which is built using an 8.77% discount rate and analyst assumptions for softer top line and higher margins over the coming years. The narrative leans heavily on long mine lives, exploration success and efficiency gains at Greens Creek, Lucky Friday and Keno Hill to support those profitability targets even as revenue growth expectations have been reset lower.
Result: Fair Value of $22.98 (UNDERVALUED)
Still, the Hecla Mining story could change quickly if capital needs at projects like Keno Hill climb faster than expected, or if stricter North American regulations push costs higher.
Find out about the key risks to this Hecla Mining narrative.
Another View: Hecla Mining looks pricey on earnings multiples
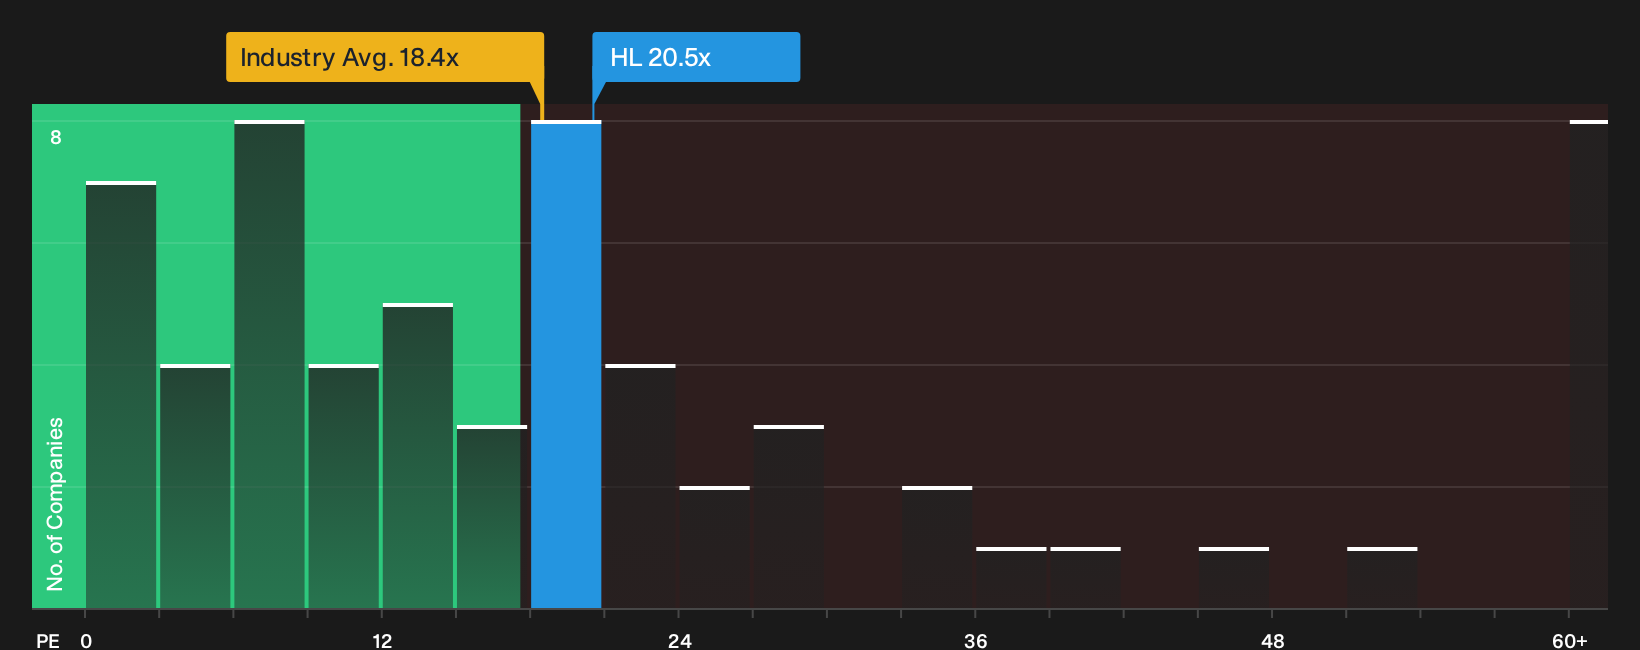
The fair value narrative presents Hecla Mining as undervalued at $16.84 versus a $22.98 target. The earnings multiple picture is tougher. The shares trade on a P/E of 20.5x, compared with a fair ratio of 18.2x, the US Metals and Mining industry at 18.4x, and peers at 17.3x.
That gap means investors are already paying a premium for HL relative to both its sector and similar companies, even though analyst forecasts point to shrinking revenue over the next few years. The question is whether the Lucky Friday record, the Keno Hill ramp up and index additions justify that richer earnings tag or leave less room for error.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If this Hecla Mining debate feels finely balanced, treat that as your cue to move fast. Check the numbers yourself and decide where you land. Then weigh those upside signals in the 1 key reward.
Looking for more Hecla Mining sized ideas?
If Hecla Mining has your attention, do not stop here. Broaden your watchlist with fresh opportunities that fit different goals, risk levels and income needs.
- Target resilient value by scanning companies that combine quality fundamentals with attractive pricing through the 29 high quality undervalued stocks.
- Build a steadier portfolio and cut down on surprises by focusing on the 31 resilient stocks with low risk scores.
- Hunt for future standouts early by filtering for strong fundamentals in the 20 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com