
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Does Shareholder Approval Change The Bull Case For MillerKnoll Stock (MLKN)?
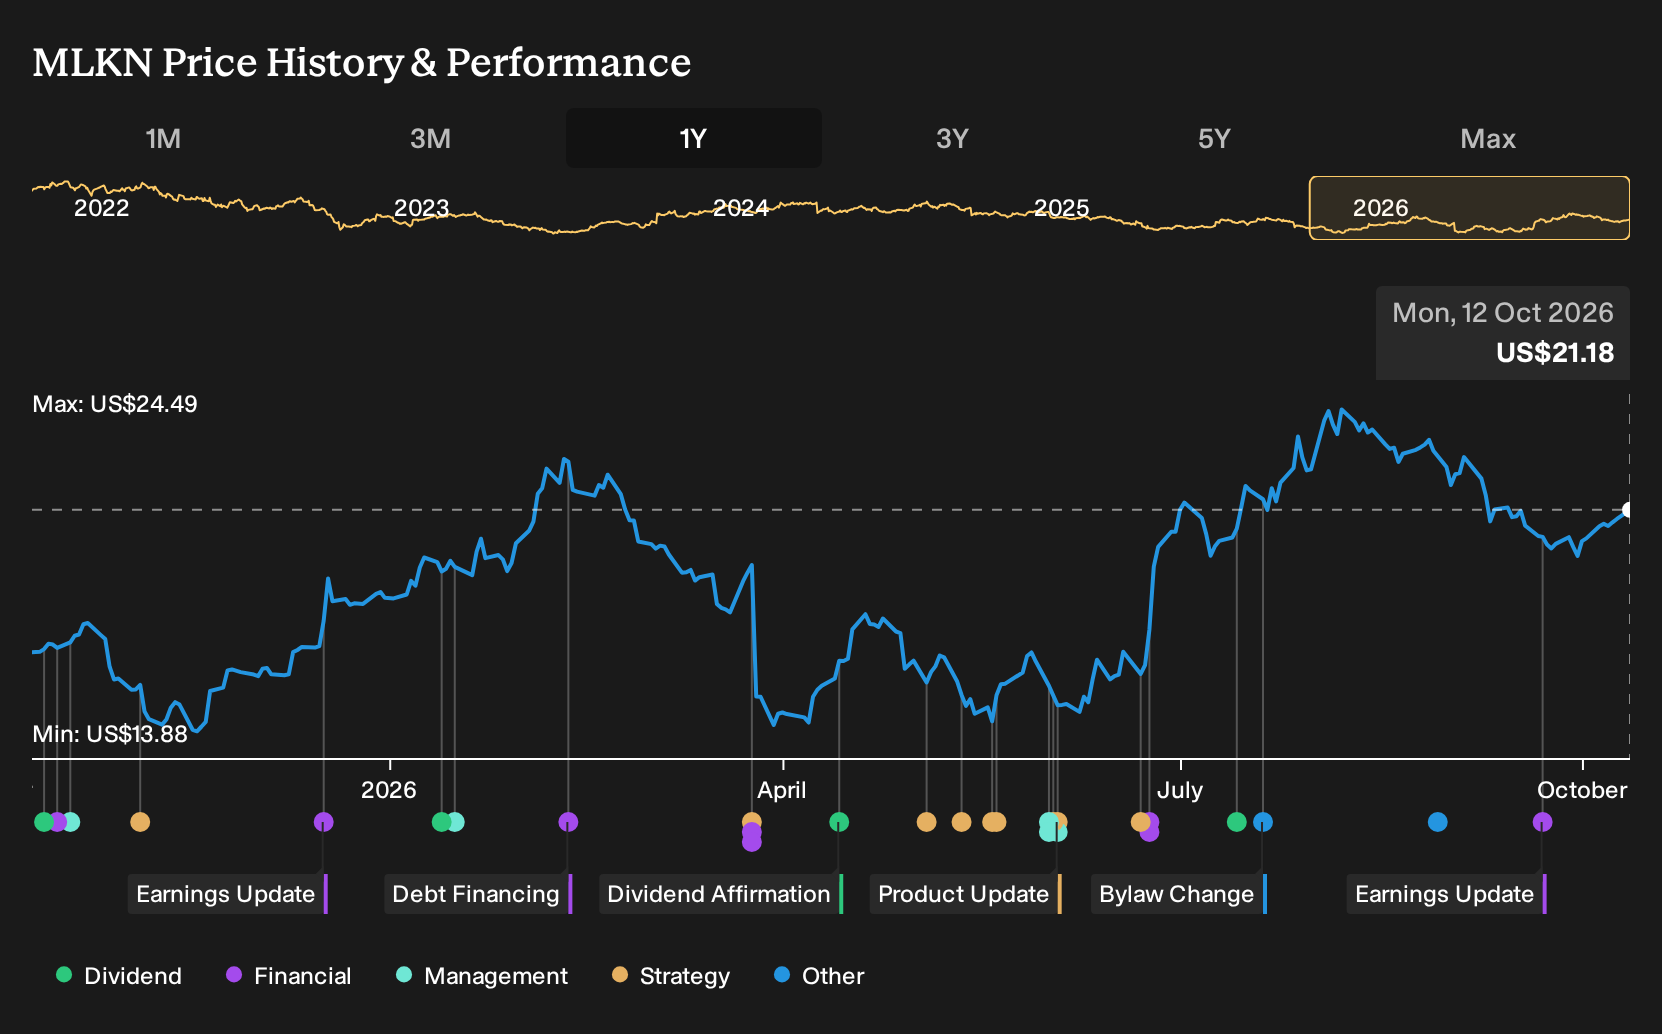
- MillerKnoll shareholders recently approved four management-backed proposals, covering director elections, executive pay, auditor selection, and a refreshed long term incentive plan, alongside reporting fiscal 2026 net sales of US$3.84b, which the company described as a 5% increase.
- The newly approved long term incentive plan signals a focus on aligning leadership rewards with MillerKnoll's goals around profitable growth, stricter cost control, and debt reduction, while it continues to expand products, showrooms, and retail locations.
- We will now assess how MillerKnoll's shareholder backing for its long term incentive plan could reshape the existing investment narrative.
MillerKnoll Investment Narrative Recap
To own MillerKnoll, you need to be comfortable with a furniture group that is leaning heavily on cost discipline and mix, not rapid top line expansion. The central view is that earnings can compound off a US$3.84b sales base as Global Retail and International Contract mature. The recent 5% net sales uplift and fiscal 2027 focus do not materially change that core premise.
The near term swing factor still appears tied to execution on operational savings and retail profitability, while preventing further softening in North America Contract. Key risks relate to tariffs, debt coverage and any prolonged pressure in healthcare or U.S. public sector demand that crimps revenue and limits margin progress.
The new long term incentive plan is the announcement that aligns most directly with this narrative. It is anchored to profitable growth, tighter costs and debt reduction, which reflects the existing view that MillerKnoll can translate operational discipline into stronger free cash flow over time rather than depending on aggressive revenue expansion.
For you as a shareholder, the relevance is practical. If management compensation now leans more on earnings quality, margin improvement and balance sheet repair, then the incentives are more closely tied to the same catalysts investors already monitor, particularly Global Retail profitability and cash generation in the context of tariffs and only modest forecast revenue growth.
MillerKnoll's narrative projects US$4.3b revenue and US$180.7m earnings by 2029. This assumes 4.1% yearly revenue growth and an earnings increase of about US$82.8m from US$97.9m today.
Discover why MillerKnoll's fair value indicates a 56% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
Two fair value estimates from the Simply Wall St Community cluster between US$27.53 and US$33, which still frame how retail investors previously viewed MillerKnoll. However, those views ignore fresh tariff risks and shifting order trends. Treat this as a reminder that opinions can be wide apart and worth comparing before you commit capital.
Explore another MillerKnoll fair value estimate, including one that suggests it could be worth just $27.53!
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your MillerKnoll research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for MillerKnoll. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate MillerKnoll's overall financial health at a glance.
Looking for more investment ideas beyond MillerKnoll?
Once you have formed a view on MillerKnoll, it can help to compare it with other opportunities that fit different goals, whether you care more about value, balance sheet strength, or long term compounding potential.
- If you want companies that combine quality fundamentals with prices that may leave some room for upside, start by scanning 29 high quality undervalued stocks.
- For investors who care most about financial resilience and cleaner balance sheets, focus your search with the list of solid balance sheet and fundamentals (25 results).
- To look for lesser known businesses that still show strong underlying metrics, broaden your watchlist using the 20 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com