
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
This Analyst Just Upgraded First Solar Stock. Here's Why.
First Solar (FSLR) shares ended higher on Oct. 12 after Truist Securities turned positive on the Tempe-headquartered manufacturer of solar panels. In his latest research note, analyst Christopher Souther upgraded FSLR to “Buy” and raised his price target to $270, indicating potential upside of about 50% from current levels.
At the time of this writing, First Solar stock is trading at nearly half its price in early June.
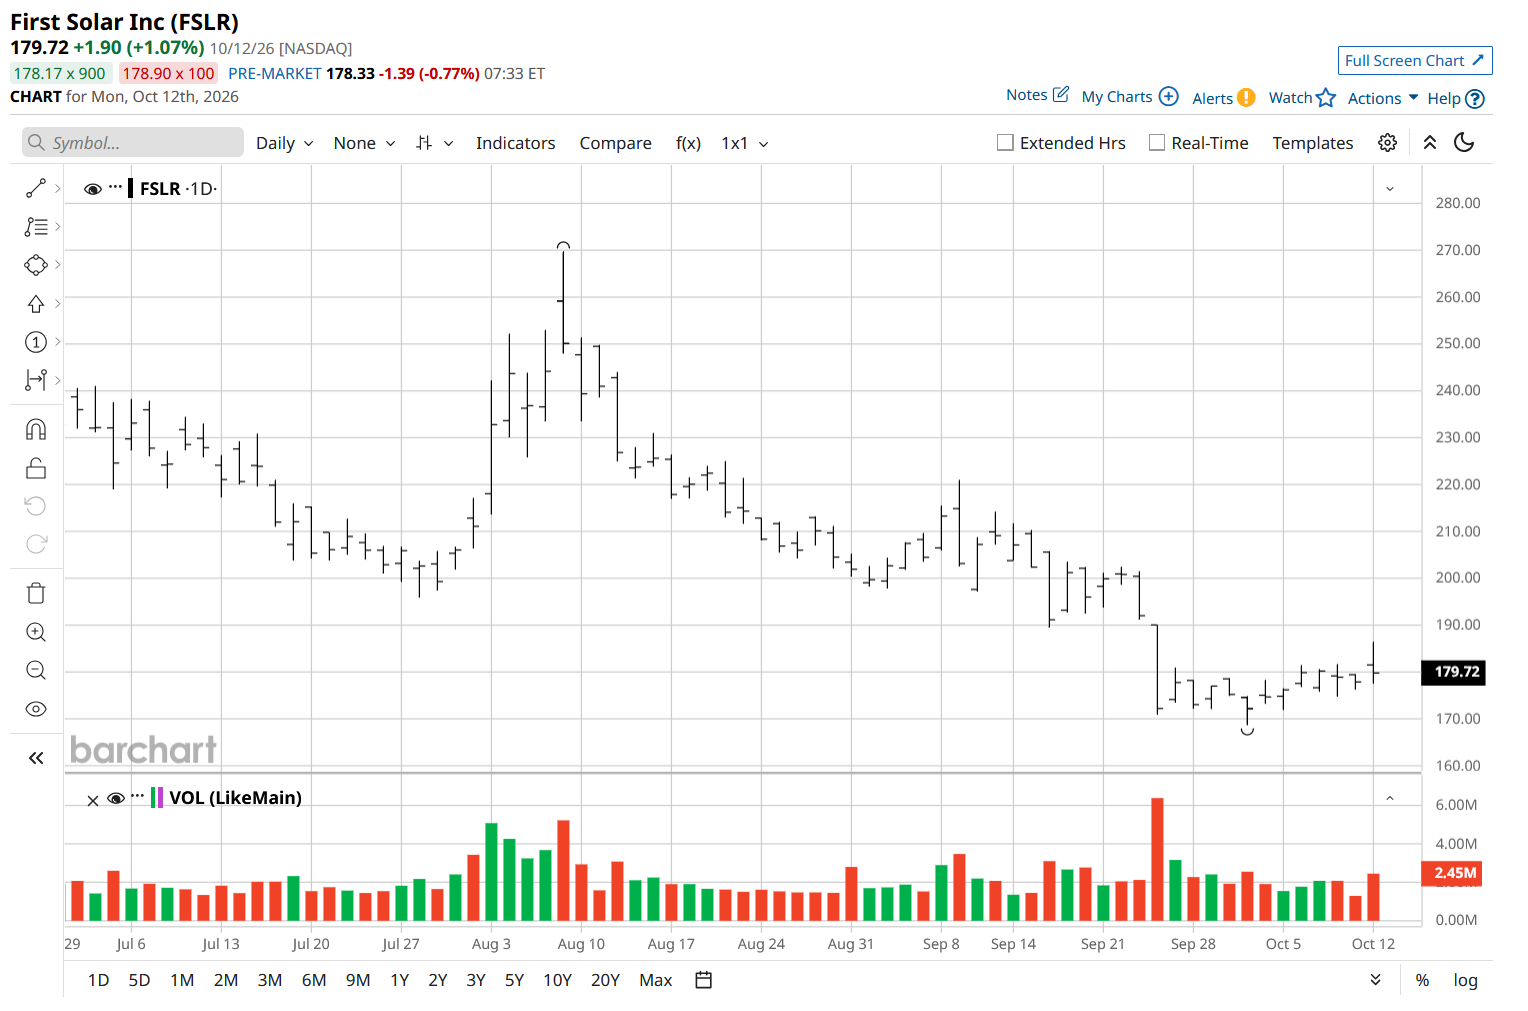
Why Truist Upgraded First Solar Stock
Souther’s report points to trade restrictions as a catalyst for stronger module pricing into the 2030s.
Section 232 decision taking effect Dec. 4 establishes an import pricing threshold, including tariffs, of 44 cents per watt for crystalline silicon modules. And an accompanying restriction on stockpiling limits foreign suppliers' ability to build inventories ahead of implementation, the analyst told clients.
Against that backdrop, Truist raised its 2029 estimate for the clean energy company’s U.S. module average selling prices by 17%.
With U.S. Series 7 capacity already sold out through 2028, the investment firm turned constructive on FSLR shares, citing the opportunity to secure better prices for bookings toward the end of this decade.
FSLR Shares Are Attractively Priced
Truist also sees a manufacturing advantage that could help First Solar capitalize on better pricing. Souther estimates its U.S. production cost at roughly $0.27 per watt before tax credits versus $0.37 for domestic crystalline silicon module production.
His revised model lifts 2029 sales expectations by 16% to about $7.7 billion and EBITDA by 29% to $4.7 billion. Separately, the analysts forecast average annual U.S. utility-scale solar installations of 44 gigawatts DC between 2027 and 2035.
That demand outlook, alongside First Solar shares’ massive year-to-date retreat, underpins Truist’s view that the current valuation offers an attractive entry point for investors looking beyond near-term contracted deliveries.
How Wall Street Recommends Playing First Solar
Crucially, other Wall Street analysts are just as bullish on FSLR stock for the remainder of 2026.
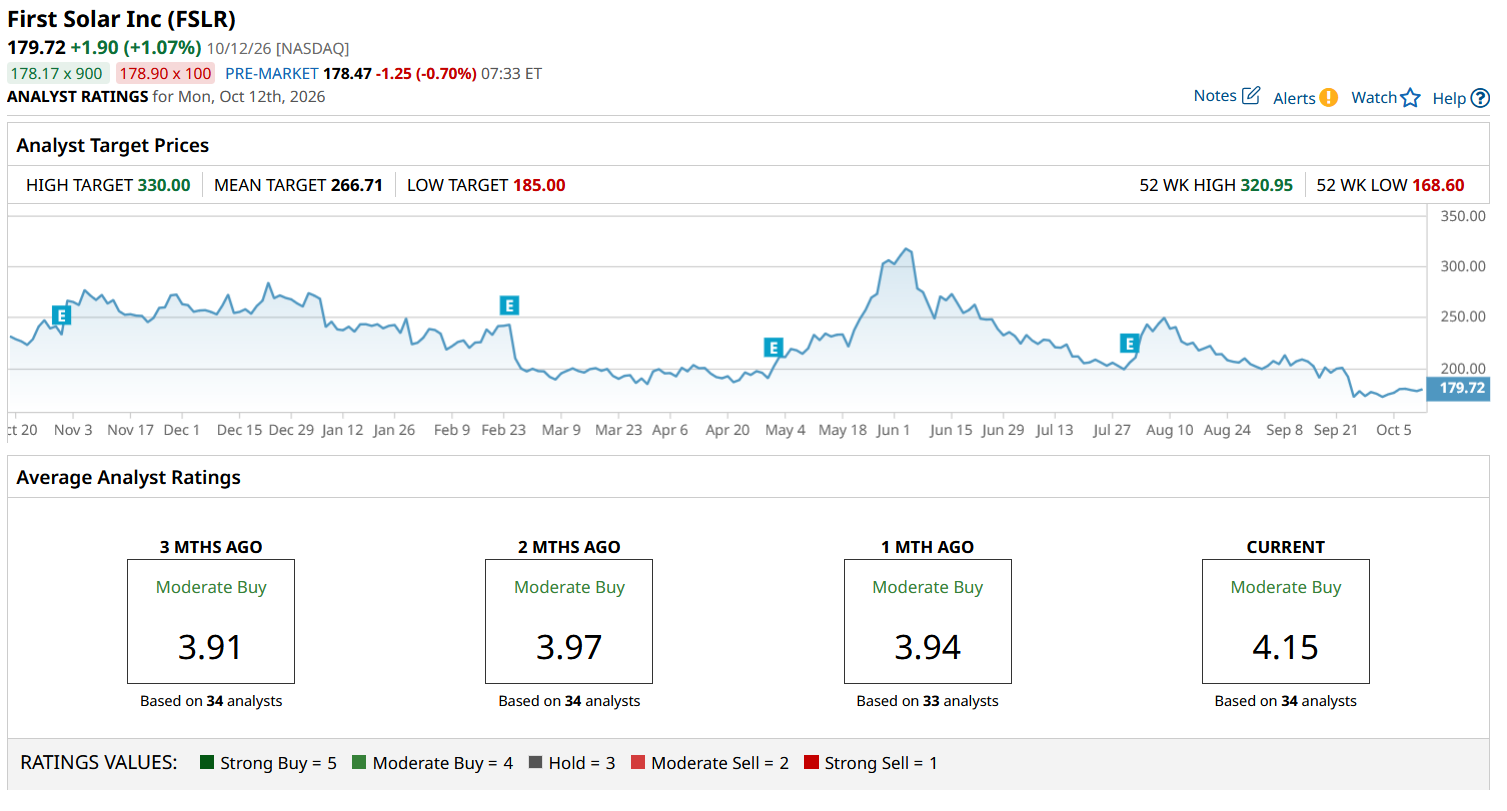
The consensus rating on First Solar sits at “Moderate Buy,” with the mean price target of about $267 indicating potential for significant further upside from current levels.
On the date of publication, Wajeeh Khan did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.