
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
What Guardian Pharmacy Services (GRDN)'s Raised 2026 Outlook Means For Shareholders
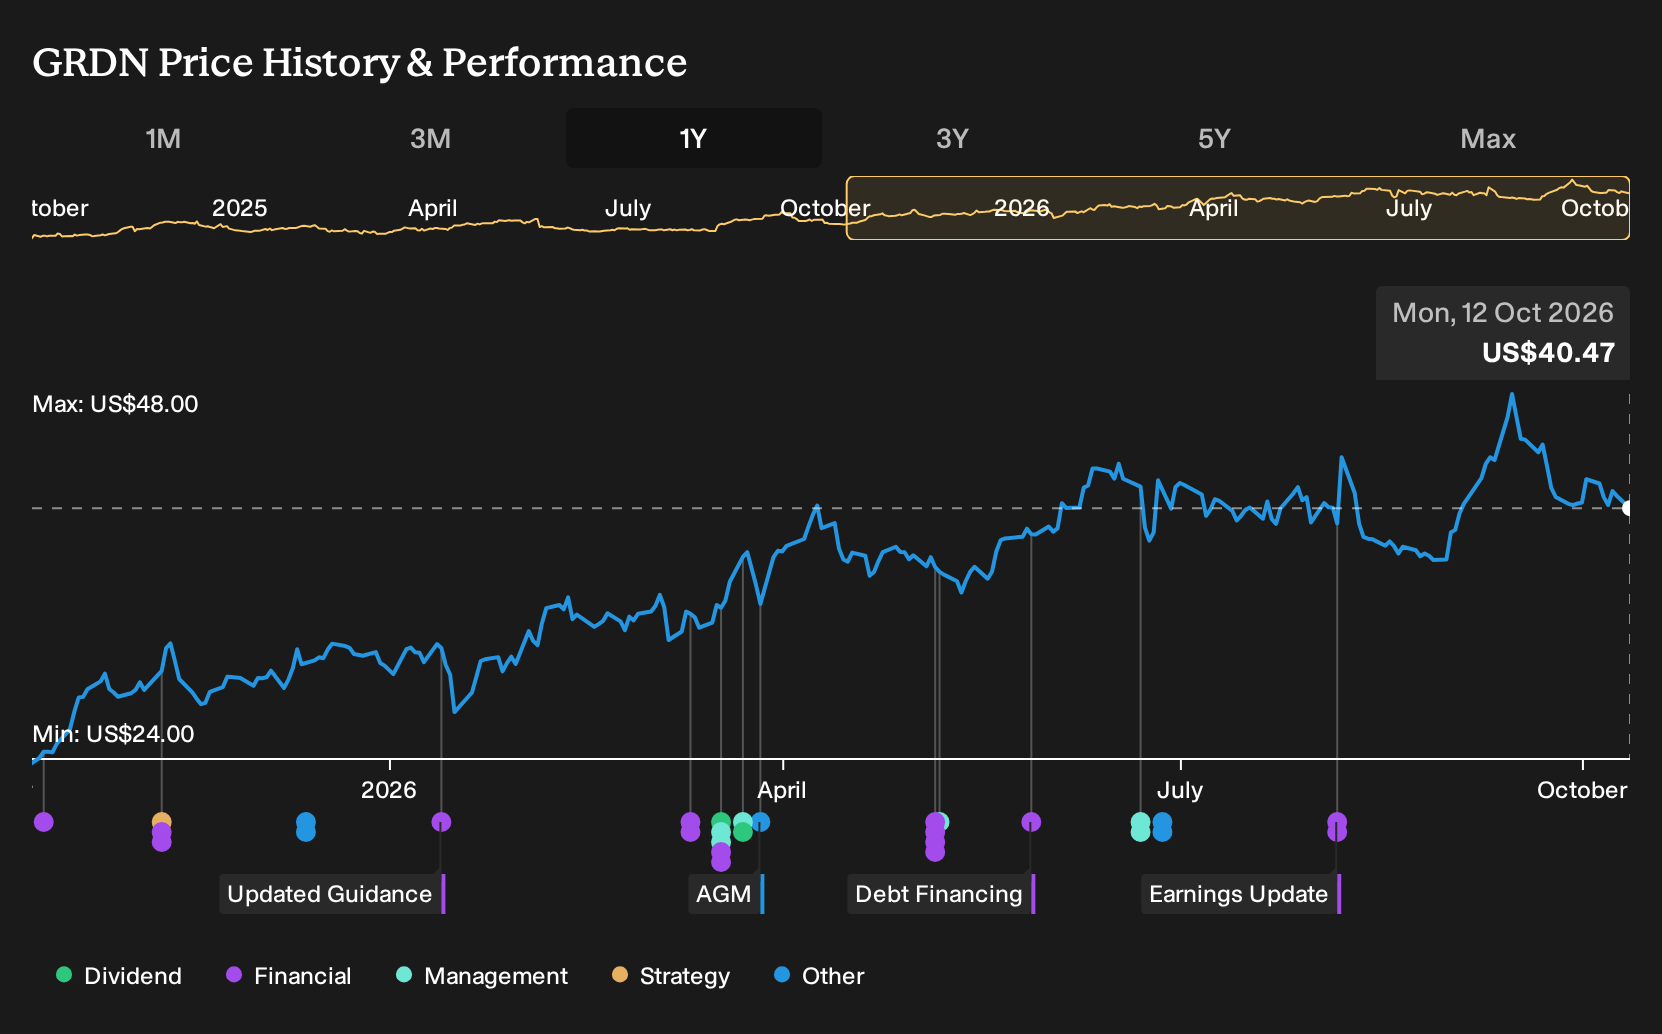
- Guardian Pharmacy Services reported Q2 2026 revenue that was 2% higher year over year and adjusted EBITDA that was 23% higher, then raised full year 2026 revenue and adjusted EBITDA guidance despite pricing pressure from the Inflation Reduction Act.
- Management linked the stronger outlook to execution on core initiatives, including a new regional leadership model, the purchase of Wellness Concepts, and a new long term care pharmacy in Lexington, Kentucky that together broaden Guardian Pharmacy Services' reach in senior care settings.
- We will now assess how Guardian Pharmacy Services' upgraded full year guidance could reshape the existing investment narrative built around long term care demand.
Compare Guardian Pharmacy Services' upgraded outlook with other potential healthcare opportunities by scanning our hand-picked 33 healthcare AI stocks that could also be building durable earnings power from recurring care demand.
Guardian Pharmacy Services Investment Narrative Recap
To own Guardian Pharmacy Services, you need to be comfortable with a long term care pharmacy model that leans heavily on recurring prescriptions from assisted living and similar facilities, and on steady integration of new locations. The key short term swing factor is whether recent pricing pressure from the Inflation Reduction Act is contained through payer negotiations and operating efficiency. The Q2 update, with higher revenue and adjusted EBITDA guidance, suggests the immediate impact of those headwinds on 2026 expectations looks limited rather than thesis changing today.
The more pressing risk right now sits with execution on acquisitions and greenfield builds, because immature sites currently weigh on adjusted EBITDA margins and could drag for longer if ramp timelines slip. Management’s tighter regional leadership structure and early contribution from the Lexington pharmacy and Wellness Concepts acquisition provide some evidence that integration is moving in the right direction. That said, any slowdown in assisted living resident move ins, or tougher contract terms from larger facility operators and payers, could quickly test this more confident guidance.
The most relevant element in the latest update is the combination of geographic expansion and portfolio build out, especially the new long term care pharmacy in Lexington, Kentucky and the purchase of Wellness Concepts. Those moves expand Guardian Pharmacy Services’ reach into additional assisted living and group home settings and increase route density, which management links to the improved full year 2026 revenue and adjusted EBITDA outlook despite reimbursement pressure. For you, the question is whether that footprint growth can continue to offset pricing and volume risks without stretching execution capacity.
Operationally, each new location and acquired asset adds integration and profitability risk, particularly because Guardian still carries an 80 basis point drag from recent investments according to prior commentary. If the Lexington site or the Wellness Concepts operations take longer than expected to reach mature economics, that drag could persist and limit further margin progress even with higher top line guidance. That execution balance, against policy exposure from Medicare Part D and growing bargaining power among consolidated assisted living operators, now sits at the center of the near term catalyst debate for this stock.
Guardian Pharmacy Services Long Term Targets In Context
Guardian Pharmacy Services' current analyst framework points to revenue of US$1.7b and earnings of US$105.3m by 2029, built on projected yearly top line growth of 5.2% and an earnings step up of about US$39.4m from the US$65.9m base today.
Uncover why Guardian Pharmacy Services' fair value indicates a 22% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
Two fair value estimates from the Simply Wall St Community cluster between US$49.5 and about US$62 per share, which already shows how far private investors can differ on Guardian Pharmacy Services. You are weighing those views against policy risk around Medicare Part D and the Inflation Reduction Act, which could reshape how this business converts long term care demand into earnings. Readers should treat these numbers as a starting point and explore several alternative viewpoints before deciding how Guardian fits into a broader healthcare allocation.
Explore another Guardian Pharmacy Services fair value estimate, including one that suggests as much as 53% upside from the current price!
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Guardian Pharmacy Services research is our analysis highlighting 4 key rewards that could impact your investment decision.
- See our latest analysis for Guardian Pharmacy Services. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Guardian Pharmacy Services' overall financial health at a glance.
Looking For More Ideas Beyond Guardian Pharmacy Services?
If Guardian Pharmacy Services is only one part of the healthcare story you want to build, it can help to line it up against other businesses with different risk and income profiles. The Simply Wall St Screener offers a straightforward way to scan for stocks that fit your own comfort level on quality, valuation, and balance sheet strength.
- For investors who want potential mispricing with quality fundamentals, consider starting with a curated set of 29 high quality undervalued stocks that might warrant a closer look.
- If capital protection matters most to you, focus on resilience first by reviewing a 31 resilient stocks with low risk scores that scores well on stability and financial strength.
- Income focused readers can round out their watchlist by checking a 8 dividend fortresses that combines higher yields with an emphasis on durability.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com