
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Top 3 Undervalued Stocks To Watch In October 2026
Investment capital is pouring into artificial intelligence projects so quickly that even central bankers are flagging AI driven spending as a source of overheating inflation. When money chases the same hot themes, solid cash generators that quietly trade below estimated fair value can get ignored. That neglect creates room for patient buyers. This article highlights three stocks the cash flow screener flags as potentially mispriced opportunities today.
The three examples below are just a small sample, since the full cash flow screen surfaced 94 more companies with equally compelling setups that are not covered here. If you want to move beyond the short list and start identifying candidates that better fit your own risk, sector, and valuation filters, head straight into the Undervalued Stocks Based On Cash Flows screener.
NVIDIA (NVDA)
Overview: NVIDIA builds data center AI computing platforms, graphics processors, and software that power cloud providers, enterprises, gamers, and automotive customers worldwide.
Operations: NVIDIA generates about $275.4b from Compute & Networking and $27.6b from Graphics, with most revenue coming from the United States and Taiwan.
Market Cap: $5,464.9b
NVIDIA matters for this cash flow focused screen because its data center AI infrastructure business turns expensive chips and software into recurring, contract-backed spending from some of the deepest pocketed customers on the planet.
"Uptake of an open-source, cheaper, or better platform than Nvidia's CUDA would heavily undermine Nvidia's moat and enable any sizeable firm to directly engage semiconductor manufacturers, such as TSMC, to produce their own chips, stealing away Nvidia's high margin products."
What happens to those rich cash flows if a single key assumption about long term pricing power quietly starts to crack?
If that question is on your mind, read the full narrative for NVIDIA to see how Nvidia's cash engine could evolve as competition and AI demand keep accelerating.
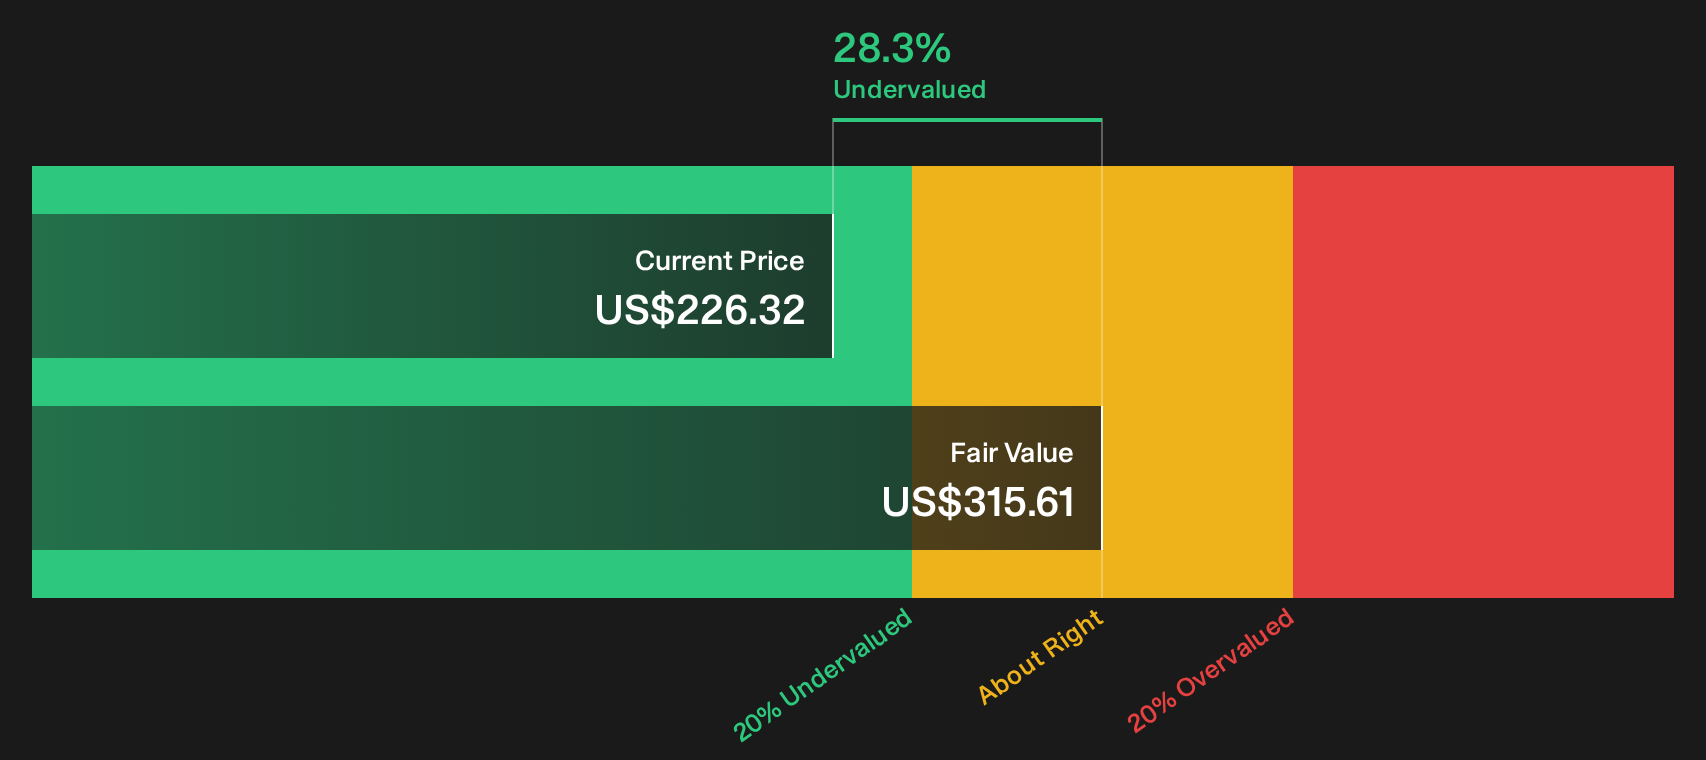
Crocs (CROX)
Overview: Crocs designs and sells casual footwear and accessories under the Crocs and HEYDUDE brands, using direct and wholesale channels that generate recurring, branded cash flows.
Operations: Crocs earns about $3.37b from the Crocs brand and $682 million from HEYDUDE, supported by roughly $1.85b in international revenue.
Market Cap: $5.6b
Unlike many fashion labels that depend on hit driven cycles, Crocs leans on repeat purchases of clogs, sandals, and HEYDUDE styles. This helps keep cash generation tied to everyday wear rather than seasonal hype.
"Expansion of Crocs beyond the Classic Clog into sandals approaching $0.5b in expected 2026 revenue, new lifestyle franchises such as Ballet Flat and Mellow, and HEYDUDE extensions in sandals, work and boots points to a broader portfolio that can support a wider customer base and more stable revenue."
What really tests that stability is how one still unresolved pressure on profitability shapes the next leg of those cash flows.
That pressure point is exactly where the story gets interesting, and the full narrative for Crocs explores whether Crocs’ expanding portfolio is quietly masking risk or accelerating a durable cash engine.
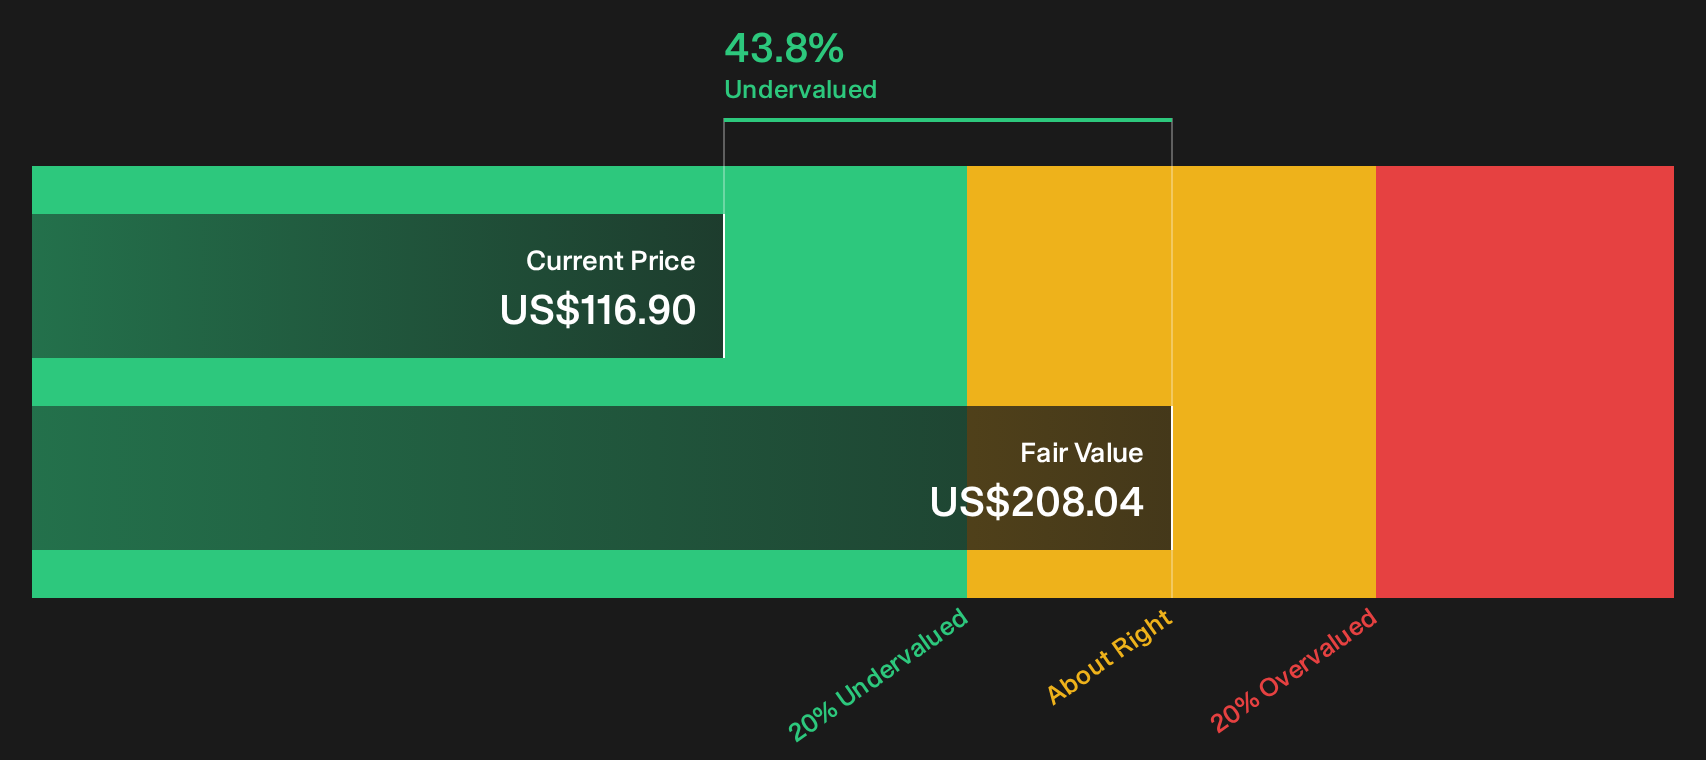
Alphabet (GOOGL)
Overview: Alphabet runs Google Search, YouTube, Android, and Google Cloud, where AI infrastructure and Vertex AI generate consumption-based enterprise revenue.
Operations: Alphabet earns about US$367.1b from Google Services and US$77.6b from Google Cloud, with US$219.0b coming from the United States.
Market Cap: US$4,293.0b
Alphabet matters for this cash flow screen because Google Cloud’s AI infrastructure and Vertex AI platform tie client spending directly to usage based contracts rather than experimental side projects.
"Google Cloud has gone from “meh” to money-maker. • Now #3 globally behind AWS and Azure, with over 11% market share."
What happens to that profit engine if one quietly building source of AI related demand shifts the trajectory of margins and contract length?
If that shift is on your radar, read the full narrative for Alphabet to see whether AI demand is accelerating a new cash engine or quietly straining Alphabet’s returns.
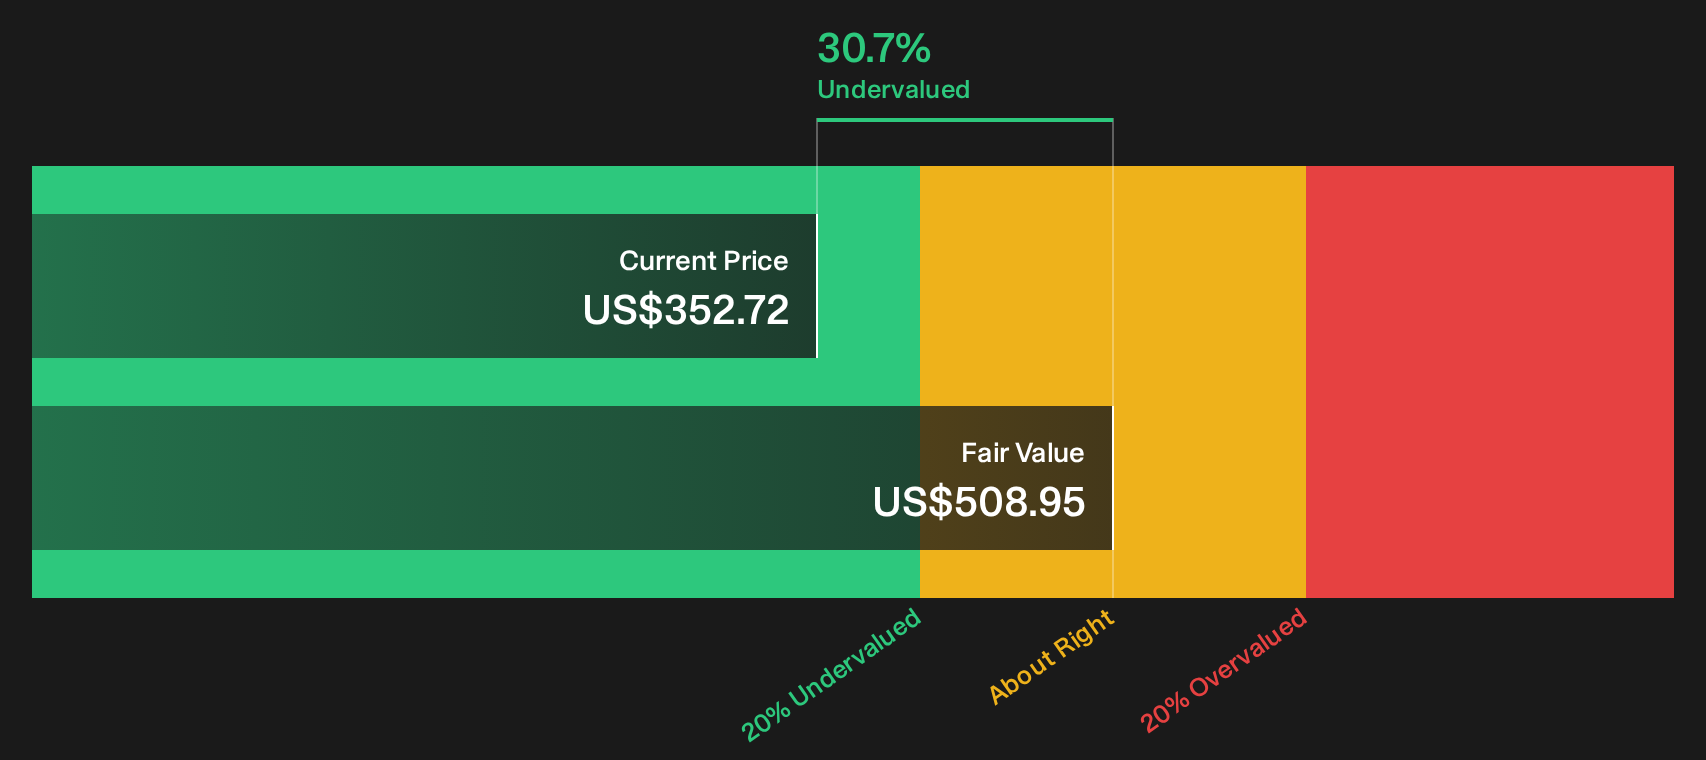
Seeking Fresh Alternatives Before Others Do
Markets move fast. Fresh ideas with real breakout potential rarely stay under the radar for long before momentum catches on and prices start flying. Scan these curated lists before the crowd and consider your options.
- Target resilient compounders that aim to hold up when sentiment drops by scanning the 31 resilient stocks with low risk scores while that edge is still under the radar for now.
- Explore early AI momentum where revenues already count by reviewing the curated 39 profitable AI stocks that aren't just burning cash before valuations reflect increased interest from later buyers.
- Evaluate opportunities for a potential materials breakout by tracking the hand picked 36 elite gold producer stocks while pricing dislocations may still matter for patient, fundamentals first investors.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com