
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Earnings Preview: What to Expect From First Solar's Report
First Solar, Inc. (FSLR), headquartered in Phoenix, Arizona, is a solar technology company that provides photovoltaic (PV) solar energy solutions. Valued at $19.3 billion by market cap, the company manufactures and sells PV solar modules with thin film semiconductor technology that provides conventional crystalline silicon PV solar modules. The renewable giant is expected to announce its fiscal third-quarter earnings for 2026 in the near term.
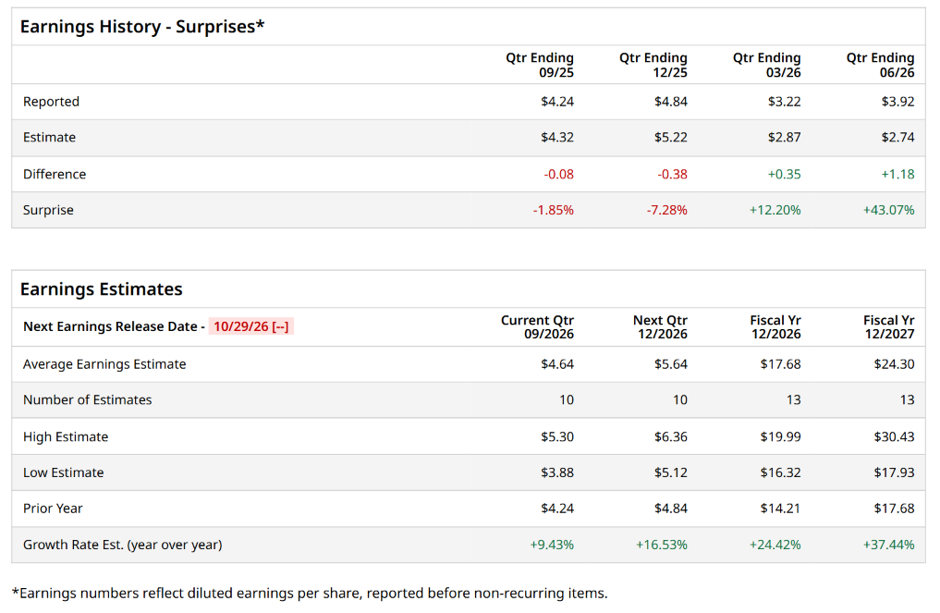
Ahead of the event, analysts expect First Solar to report a profit of $4.64 per share on a diluted basis, up 9.4% from $4.24 per share in the year-ago quarter. The company beat the consensus estimates in two of the last four quarters while missing the forecast on two other occasions.
For the full year, analysts expect First Solar to report EPS of $17.68, up 24.4% from $14.21 in fiscal 2025. Its EPS is expected to rise 37.4% year over year to $24.30 in fiscal 2027.
FSLR stock has underperformed the S&P 500 Index’s ($SPX) 19.2% gains over the past 52 weeks, with shares down 18.9% during this period. Similarly, it notably lagged behind the State Street Technology Select Sector SPDR ETF’s (XLK) 37.3% returns over the same time frame.
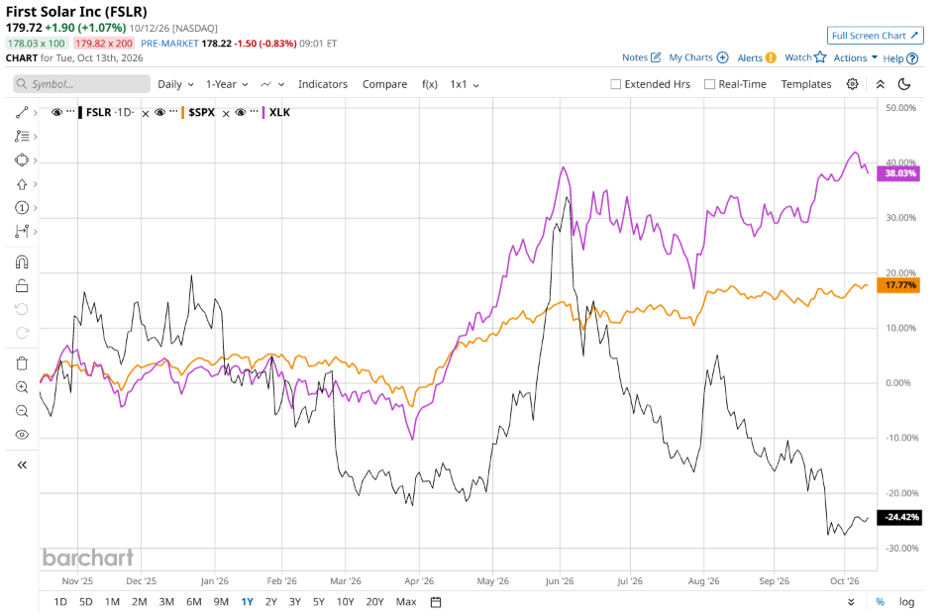
First Solar's underperformance stems from growing investor caution surrounding the macroeconomic and regulatory landscape for U.S. solar demand. Despite maintaining a robust contracted backlog, the company posted a 4% year over year decline in net sales during Q2 2026. Investor sentiment has been further strained by intense tariff uncertainties, shifting trade policies, and subsequent securities class action lawsuits alleging that leadership downplayed the financial toll of facility underutilization and production onshoring costs. Management's own warnings regarding how evolving legislative frameworks could pressure module demand, pricing structures, and operational costs, alongside sharp analyst downgrades have continued to weigh heavily on the stock.
On Jul. 30, FSLR shares closed up by 3.4% after reporting its Q2 results. Its EPS of $3.92 surpassed Wall Street expectations of $2.74. The company’s revenue was $1.1 billion, matching Wall Street forecasts. FSLR expects full-year revenue in the range of $4.9 billion to $5.2 billion.
Analysts’ consensus opinion on FSLR stock is reasonably bullish, with a “Moderate Buy” rating overall. Out of 34 analysts covering the stock, 20 advise a “Strong Buy” rating, three suggest a “Moderate Buy,” nine give a “Hold,” and two recommend a “Strong Sell.” FSLR’s average analyst price target is $266.71, indicating a potential upside of 48.4% from the current levels.
On the date of publication, Neha Panjwani did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.