
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
3 Canadian Growth Stocks To Own In October 2026
AI investment is keeping global growth hotter than many expected, according to the IMF, even as inflation and debt worries pick up. That mix is pushing investors toward Canadian businesses that are expanding quickly and where insiders have a lot of their own money at risk. This article walks through three fast growing, high insider ownership stocks from our Canada focused screener and explains why each one deserves a closer look now.
The three stocks highlighted here offer a compelling starting point if you want exposure to fast growing businesses where leadership is clearly aligned with shareholders. However, if you want the pick of this theme, these 11 high growth high conviction stocks are the best of the best.
Tenaz Energy (TSX:TNZ)
Overview: Tenaz Energy is an oil and gas producer focused on Dutch North Sea natural gas projects alongside complementary Leduc-Woodbend assets in Canada.
Operations: Tenaz Energy generates about CA$497 million from petroleum and natural gas sales, with roughly CA$460 million coming from the Netherlands and CA$38 million from Canada.
Market Cap: CA$2.26 billion
Tenaz Energy fits this fast growth, high insider ownership theme through its efforts to scale Dutch North Sea natural gas output using existing offshore infrastructure.
"The Triton 10 barge and the pipeline of about 50 identified offshore workover opportunities provide a multi year program that is expected to add productive capacity at relatively low incremental capital, which can support net margins by spreading fixed costs over higher output."
What happens to Tenaz Energy’s appeal if one unseen pressure on future European gas pricing shifts more sharply than investors currently assume?
If that pressure is your key concern, the full narrative for Tenaz Energy sets out how Tenaz Energy could still compound value if European gas pricing decouples further.

Ivanhoe Mines (TSX:IVN)
Overview: Ivanhoe Mines is a Vancouver based miner focused on large African copper, zinc and platinum group metal projects led by the Kamoa-Kakula Copper Complex.
Operations: Ivanhoe Mines generates about US$575 million from Kipushi Properties, with Hong Kong and Singapore customers accounting for roughly US$417 million.
Market Cap: CA$16.5 billion
Ivanhoe Mines fits this fast growth, high insider ownership theme through Kamoa-Kakula, where copper focused expansion plans are a central focus of analyst and management optimism.
"Catalysts stacked (Phase 3/4 Kamoa ramp to >550 ktpa medium-term, Platreef Phase 2, Kipushi de-bottlenecking, smelter online, Project 95 recoveries, exploration)."
The real test comes if one unseen pressure on long term copper demand and pricing shifts more sharply than current expectations imply.
If that long term copper pressure is what you keep circling back to, the full narrative for Ivanhoe Mines shows how Ivanhoe Mines’ expansion plans could still accelerate value creation.

Cascades (TSX:CAS)
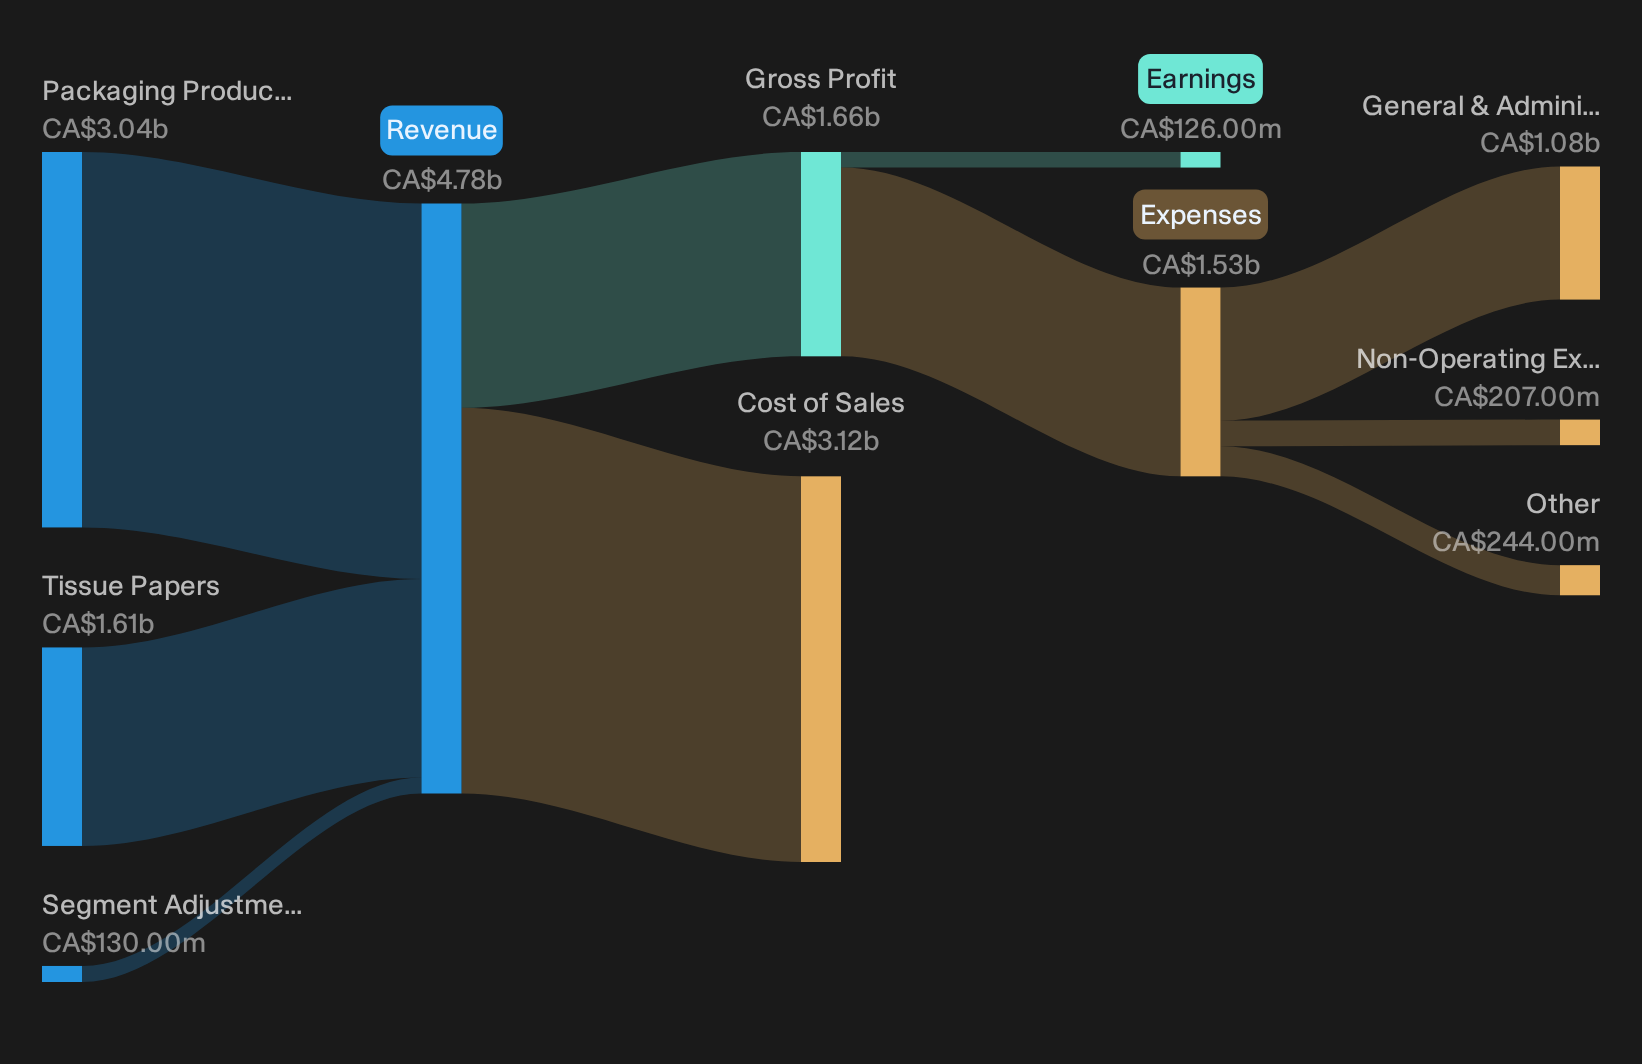
Overview: Cascades is a Canadian producer of packaging and tissue products, with high growth e-commerce and protective packaging solutions supporting the theme.
Operations: Cascades generates about CA$3.0b from Packaging Products and CA$1.6b from Tissue Papers, primarily across Canada and the United States.
Market Cap: CA$1.8b
Cascades plugs into this fast growth, high insider ownership theme through its focus on higher value e-commerce and protective packaging. This ties improving profitability to rising online shipping volumes.
"Continued ramp up at the Bear Island mill toward Greenpac level efficiencies, combined with targeted reductions in chemical and material usage, should lift Packaging segment productivity and support structurally higher EBITDA margins."
What happens to Cascades’ appeal if one unseen pressure on long term input costs and pricing power shifts more sharply than expected?
That pressure point is exactly where the full narrative for Cascades shows whether Cascades’ ramp up can accelerate earnings power or if costs keep masking the upside.
Seeking Fresh Alternatives Before They Fly
Fresh ideas often move first, and some of the strongest breakouts can advance before most investors even look up. Scan these under the radar lists while it matters and consider opportunities early.
- Look for stronger balance sheets and steadier cash flows using the curated list of solid balance sheet and fundamentals (7 results) before defensive quality is fully reflected in broader pricing.
- Explore future facing infrastructure opportunities by reviewing the hand picked 43 power grid technology and infrastructure stocks while grid upgrades and electrification themes are still being quietly incorporated into valuations.
- Track emerging automation activity through the focused 91 robotics and automation stocks before industrial robotics and AI linked manufacturers attract a new wave of attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com