
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Did JHSF Participações' 166% Run Pass You By? What The Bulls Got Right
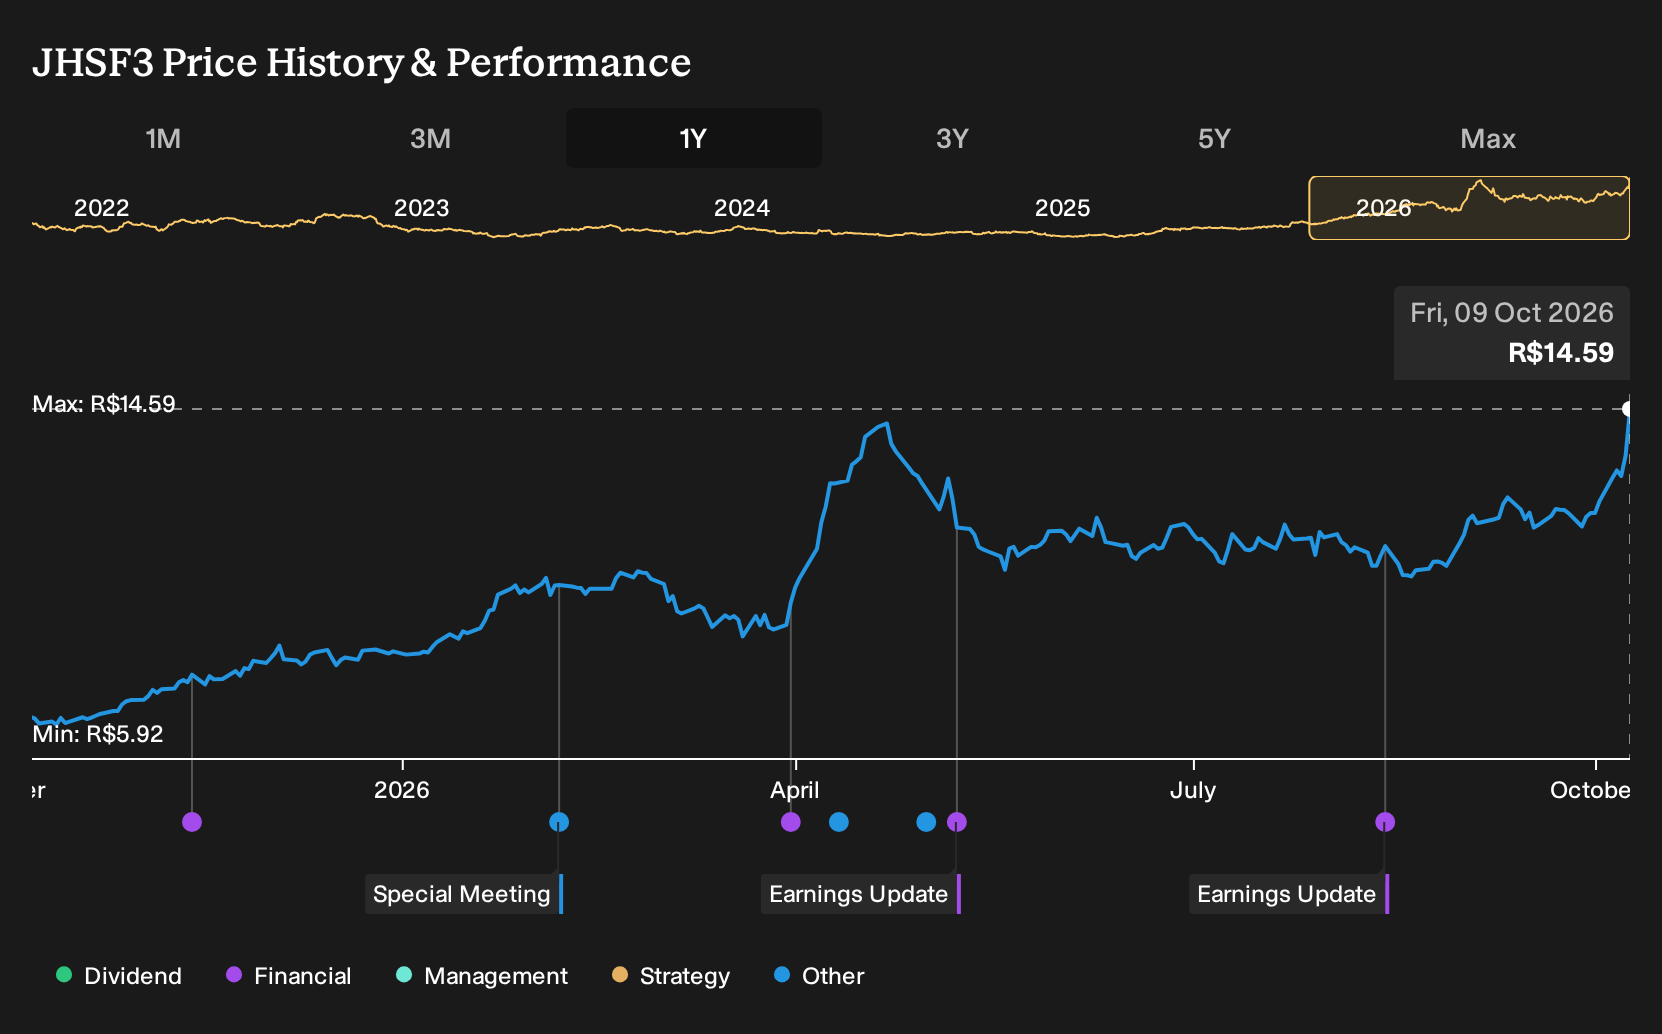
If you held JHSF Participações through a year of arguing analysts and luxury-mall debates, the scorecard is hard to ignore. Investors who held JHSF Participações over the past year are up 165.8%, including dividends. That outcome lands after a period when bulls pointed to scarce Cidade Jardim assets and planned project rollouts, while bears stressed high-end exposure and leverage. If you were deciding back on 9 October 2025, which of those trade offs would have mattered most?
A Narrative on Simply Wall St is one investor's written case for a company, with its growth, margin and multiple assumptions spelled out. Those assumptions imply an estimated Fair Value.
The easy part of this move is behind JHSF Participações. Zero in on 182 high quality undervalued stocks for companies trading below our estimates.
The Argument You Would Have Been Weighing Up On JHSF Participações
The shares cost R$6.09 at the start of the period, and anyone looking at JHSF Participações then had to choose between two very different stories.
The bullish narrative pinned fair value at R$10, built on the idea that near full occupancy at assets like Cidade Jardim and tight luxury supply could support rental rate escalation and higher long term cash flows.
The bearish case put fair value at R$4.2, focusing on the risk that heavy ultra luxury concentration and significant leverage could leave the group exposed if high end demand weakened or financing costs stayed elevated.
What The Results Changed For The JHSF Participações Debate
The clearest new fact came from Q2 2026. JHSF Participações reported total revenue of R$935.319 million and net income of R$452.13 million, with net margin edging up from 47.6% to 48.3%. That combination of higher sales, higher profit and a slightly thicker margin leaned toward the view that premium assets could sustain strong economics.
The main lesson is simple. When a thesis hinges on pricing power and asset quality, track revenue, profit and margin side by side in each report, and see whether all three move in the direction the original story implied.
What JHSF Participações Buyers Are Assuming Today
JHSF Participações now trades at R$14.59. The selected Narrative’s Fair Value estimate sits below that level, reflecting a view that the current quote already bakes in a lot of hope about its capital light model and recurring assets.
At today’s price you are effectively assuming that a larger, higher end portfolio can deliver durable occupancy, pricing and profitability. The question the selected Narrative pushes you to test is how concentration, expansion and fund structures might affect those cash flows over time.
"Although JHSF Participações presents record recurring results across malls, hospitality, airports, residences and clubs, the shift to a diversified recurring-income ecosystem raises the risk that incremental projects dilute overall returns if newer assets do not sustain the same occupancy and pricing. This could weigh on consolidated EBITDA quality and margin mix."
One Narrative has put a figure on that disagreement. → See the Narrative with its lower Fair Value, assumptions and all
Go Straight To The Source
The story behind this run has already been told. The next one could be taking shape somewhere else. Where could you start looking before it becomes the headline?
- Company 1 - 47% below our estimate - targets digital payment growth and uses repurchases to support platform scale.
- Company 2 - 25% below our estimate - treats one producing asset as funding source for broader exploration programs.
- Company 3 - 38% below our estimate - plugs artificial intelligence into recruitment and services platforms to refine matching.
That is three of the list. See every one of the 203 solid balance sheet companies →
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com