
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Humana (HUM) Stock Could Be Undervalued After Its 64% Rally
Humana has delivered a sharp year to date share price gain, and the move now puts a spotlight on whether that level is supported by the earnings power behind the stock.
- With the stock up 63.9% year to date, a lot of optimism is now embedded in the price. That raises the stakes for what you are willing to pay for each dollar of Humana's profit.
- The step up in Medicare Advantage star ratings may support expectations for higher future revenue and profitability. This feeds directly into how much value investors ascribe to the business's earnings stream.
- The analysts covering Humana have run their own numbers. See what analysts think Humana's shares could be worth.
The stock's next move may depend on whether Humana's current share price can be explained by its earnings when compared with the Fair Ratio benchmark.
If you are testing whether Humana’s sharp move makes sense relative to its earnings, it can help to compare it with other businesses screened for similar discipline using 31 resilient stocks with low risk scores.
Is Humana a Bargain on Earnings?
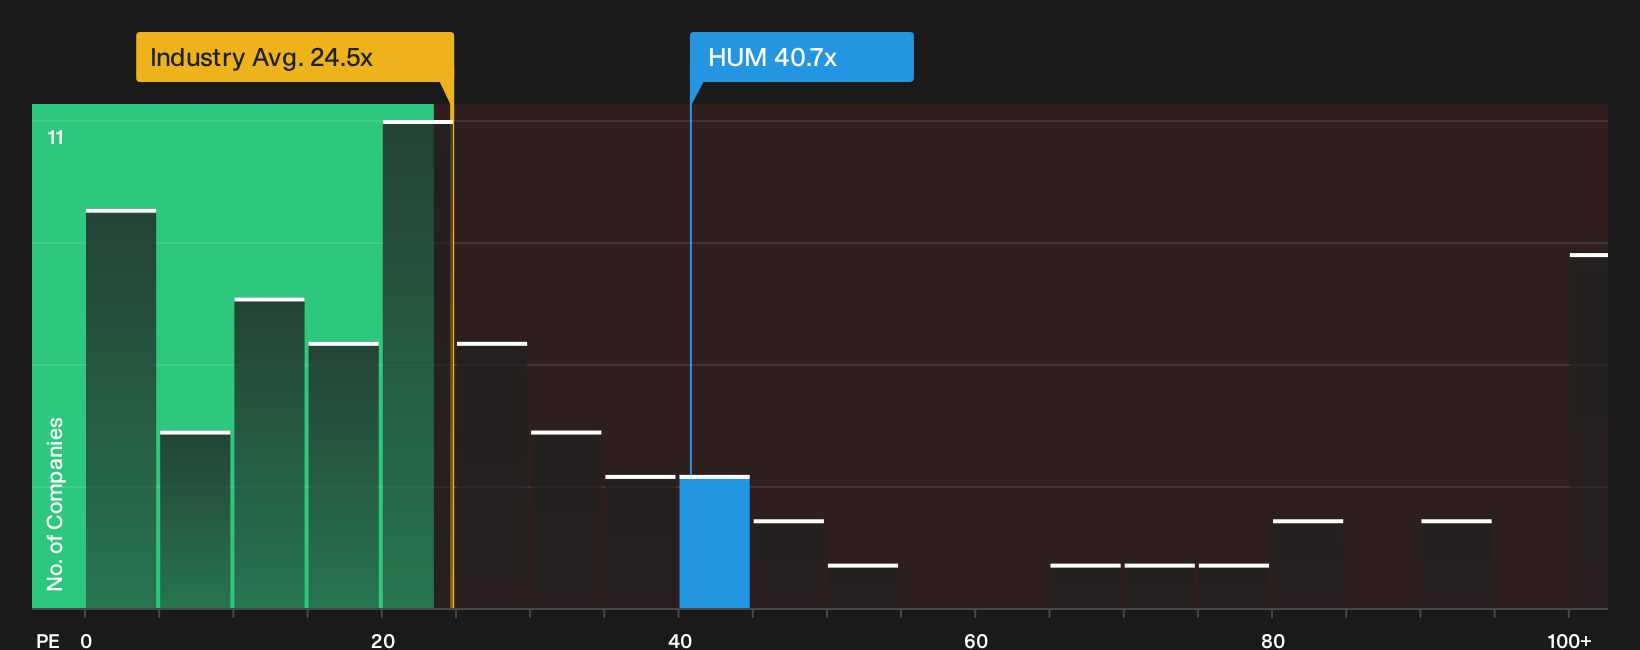
The P/E ratio suits Humana because earnings are a key lens for a mature insurer where profit per member matters as much as headline revenue. On that yardstick, the stock changes hands at about 40.7x earnings, which is clearly above the Healthcare sector average of roughly 24.5x and also richer than the 25.5x peer group level. Because of that gap, each dollar of Humana’s profit currently carries a higher price tag than many comparable health insurers.
The Fair Ratio, which reflects what investors might typically pay given Humana’s economics and risk profile, sits above the current P/E, so the shares screen as undervalued on this framework even after the strong run. Because Medicare Advantage star rating gains are already public and have lifted the stock, the remaining discount on the P/E line suggests the market is still not fully aligning the price with what this model implies. Explore the numbers behind Humana's P/E valuation.
The Humana Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the valuation puzzle for Humana leaves off and describe what would need to happen to growth, margins and earnings for the stock to appear meaningfully higher or lower than today’s price. Each narrative links a potential path for Humana's catalysts and risks to a specific estimated worth for the business, so you can track over time which storyline seems closest to reality on the Community page.
Humana attracts two very different readings right now, with one camp leaning into margin repair and another focused on tightening Medicare oversight.
Bull case: 16% undervalued
"The company’s multi year operating model transformation, which is already associated with a 120 basis point year over year decline in the consolidated operating cost ratio in Q2 2026 and an expected 150 basis point reduction for the full year, creates headroom for a more pronounced drop in ongoing administrative expenses…"
Discover why this Narrative puts Humana at 16% undervalued.
Bear case: 104% overvalued
"Across the industry, regulators are sharpening their focus on how health plans document risk adjustment data and apply prior authorization standards…"
Explore why this Narrative puts Humana at 104% overvalued.
One more angle on Humana that could change your view
Earnings multiples tell you what investors pay today. However, forward looking research desks sketch a different picture of where Humana might be a few years from now, and how that lines up with this price. Explore where analysts expect Humana to be in a few years.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com