
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Valvoline (VVV) On Same Store Sales Growth Narrative Looks Undervalued
Valvoline (VVV) has been drawing attention after recent trading left the stock down about 1% over the past month and roughly 22% over the past 3 months, inviting closer scrutiny from investors.
Those short term moves come after a tougher stretch, with Valvoline’s share price down about 22% over the past three months and the 1 year total shareholder return declining around 14%, which suggests recent momentum has been fading as investors reassess both growth prospects and risk.
Scan how investors are repricing auto services by comparing Valvoline with a hand picked 29 high quality undervalued stocks that pairs steady operations with what our models flag as discounted valuations.
For Valvoline, that recent slide could hint at deeper questions about the auto service model, or it could simply reflect cooler sentiment after a strong run earlier this year. The valuation work starts by separating those two stories.
Most Popular Narrative: 30% Undervalued
Against Valvoline’s last close of $30.16, the most followed narrative pins fair value around $43.25, putting the gap between price and expectations firmly on the table for anyone weighing the stock today.
The consistent growth in same-store sales driven by both increased transactions and higher ticket sizes from premium service offerings remains in place, and recent guidance for system-wide same-store sales of 7.5% to 8% supports the view that Valvoline can continue translating resilient maintenance demand into revenue and earnings growth over time.
See why 2 investors see Valvoline as 30% undervalued.
Result: Fair Value of $43.25 (UNDERVALUED)
Still, the narrative around Valvoline only holds if rising lubricant costs and softer traffic from higher gas prices do not squeeze margins or stall same store sales.
Find out about the key risks to this Valvoline narrative.
Another View: Valvoline Looks Expensive On Earnings
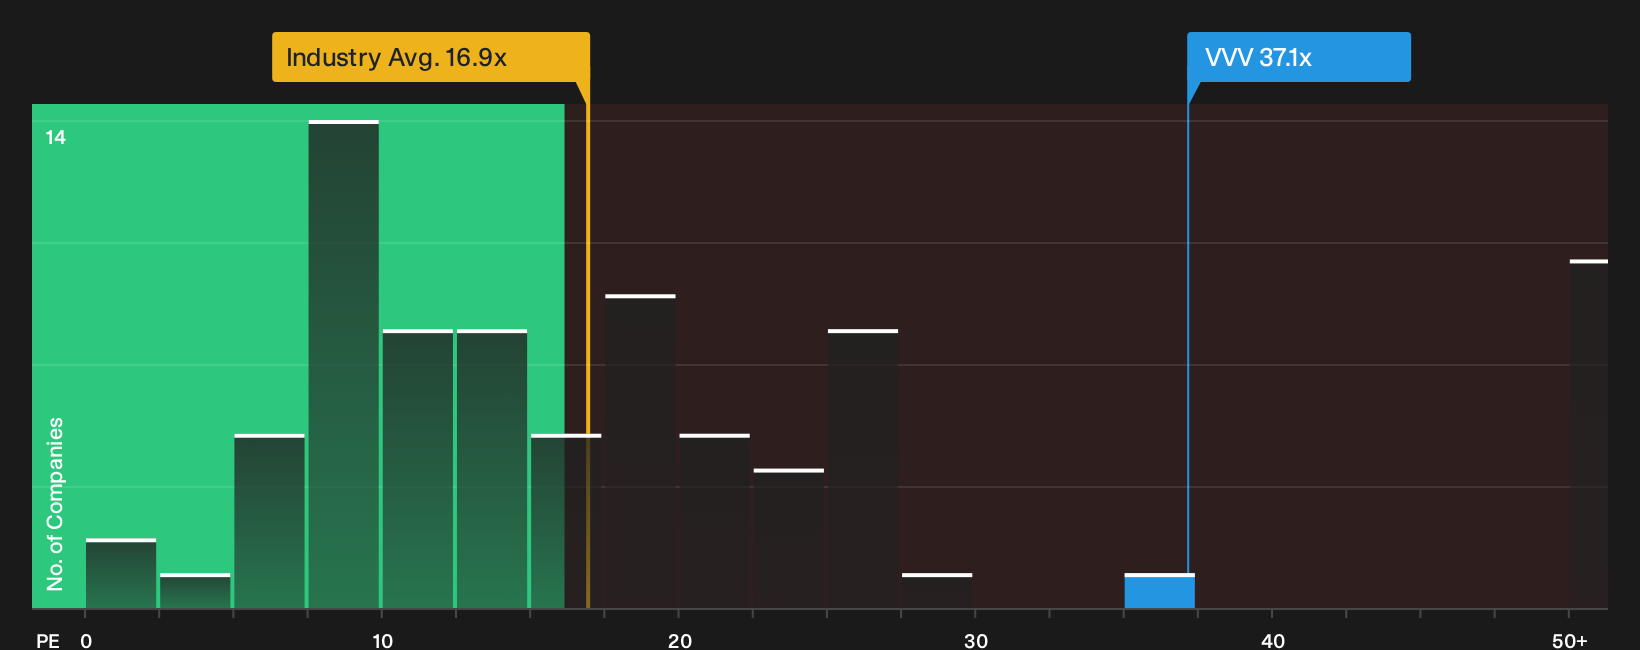
Set the $43.25 fair value to one side for a moment. On a simple earnings lens, Valvoline trades on a P/E of 37.1x, compared with 16.5x for the US Specialty Retail industry, 7.7x for peers, and a fair ratio of 36x that the market could eventually move toward. That premium hints at less room for error than the 30% undervalued story implies. Which version of Valvoline’s future do you trust more: the narrative or the multiple?
Investors who lean on earnings based checks may want to see how this gap looks in a structured valuation breakdown before making a call on risk versus reward. See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment on Valvoline appears to be divided. Consider acting while the data is fresh and weigh both sides by checking the 2 key rewards and 3 important warning signs.
Looking for more Valvoline sized investment ideas?
If you only stop at Valvoline, you risk missing out on other opportunities that fit your style just as well or even better.
- Start with resilient balance sheets and steady fundamentals by scanning our list of solid balance sheet and fundamentals (25 results) tailored to companies that prioritise financial strength.
- Hunt for quality at a discount by reviewing the 20 high quality undiscovered gems before other investors catch on to them.
- Reduce potential portfolio stress by focusing on the 31 resilient stocks with low risk scores that aims to keep drawdowns in check while you stay invested.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com