
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
What Is Drawing Fresh Attention To Ryder System (R)?
Ryder System (R) has expanded its used commercial vehicle footprint in northern New Jersey by relocating its Kearny site to Newark and adding a North Bergen sales center in a key freight corridor.
Despite the Newark and North Bergen expansion and a recent dividend affirmation, Ryder System’s share price has drifted, with a 90-day share price return down 11.4%, even as the year-to-date share price return is up 22.31% and the 1-year total shareholder return is 34.45%. This suggests that long-term momentum remains stronger than the recent pullback.
Scan how Ryder System compares with other logistics focused opportunities by reviewing our hand picked list of solid balance sheet and fundamentals (25 results) in similar capital intensive sectors.
Ryder System now trades roughly 21% below the average analyst price target after a recent pullback, even though its own intrinsic value estimate implies a premium. Is the market showing discipline, or is it leaving too much on the table?
Most Popular Narrative: 18% Undervalued
Ryder System last closed at $237.51, compared with a widely followed fair value narrative of $291.22. This frames the current pullback as a discount to that long term view.
Ryder System sustained investment and growth in its asset light Supply Chain and Dedicated solutions is now reflected in guidance that these segments will account for about 60% of 2026 revenue, with more than 90% of total revenue under long term contracts. This supports higher recurring revenue and earnings compared with the prior cycle.
See why 7 investors see Ryder System as 18% undervalued.
Result: Fair Value of $291.22 (UNDERVALUED)
Still, the Ryder System thesis can be knocked off course if automotive headwinds linger, or if those delayed Supply Chain contracts continue to ramp more slowly than expected.
Find out about the key risks to this Ryder System narrative.
Another View on Ryder System Valuation
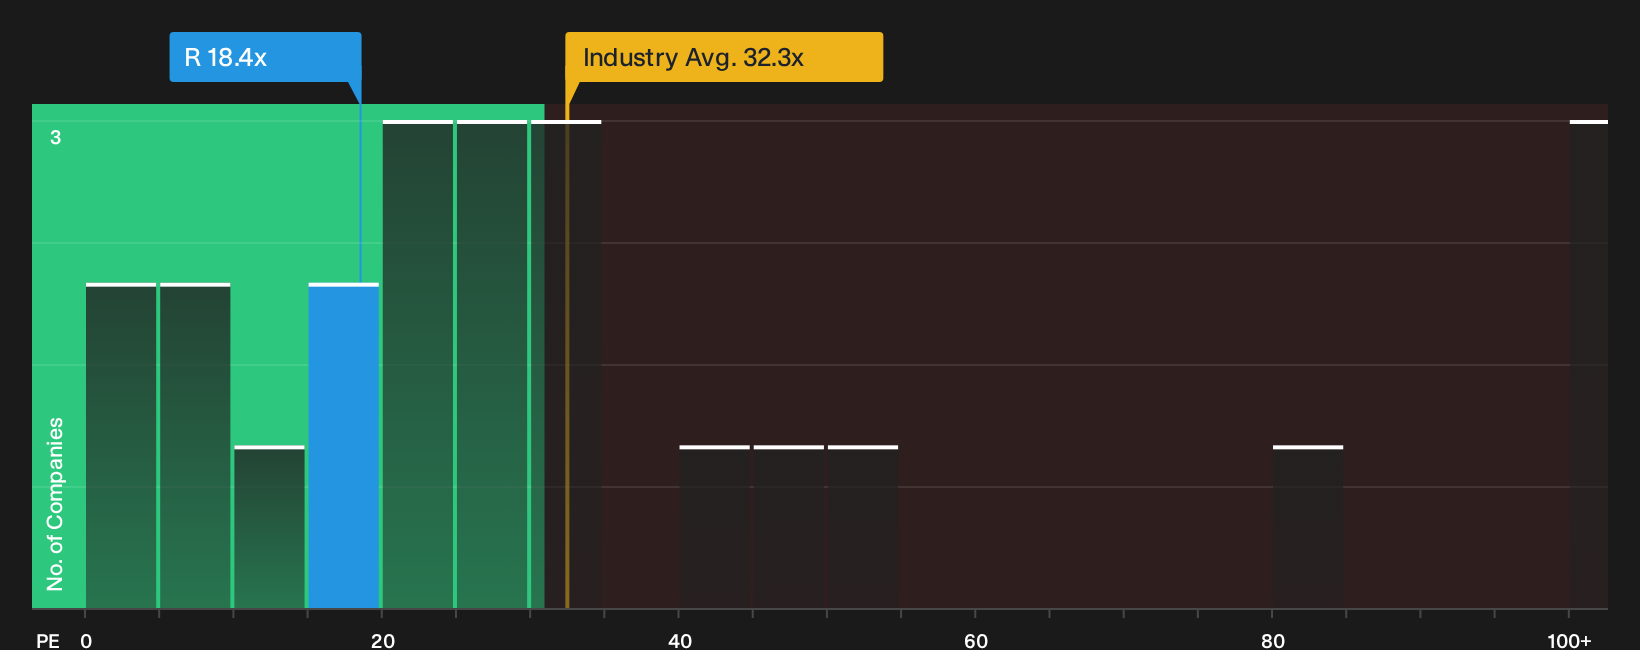
The fair value narrative pegs Ryder System at $291.22, which paints the stock as undervalued. The P/E story is less generous. The shares trade on 18.4x earnings compared with a fair ratio of 18.3x, so by that lens the stock screens a touch expensive. With the P/E also well below the US Transportation industry average of 32.2x and the peer average of 66.9x, are investors being cautiously realistic about future cash flows or leaving room on the table for sentiment to reset?
To see how this earnings multiple could shift if sentiment or forecasts change, take a closer look at the valuation breakdown, including how Ryder System stacks up against its sector peers, in the See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
That mix of optimism and concern around Ryder System is exactly where real insight lives, so do not wait for consensus to form before checking the underlying data. Then weigh both the potential upside and the reservations captured in the 4 key rewards and 1 important warning sign.
Looking for more Ryder System style ideas?
If you stop at Ryder System, you could miss other opportunities that fit your goals, so put the Simply Wall Street Screener to work for you today.
- Target potential bargains that pair quality with value by scanning our hand picked 29 high quality undervalued stocks for ideas that might deserve a closer look.
- Strengthen your income stream by reviewing companies in the 8 dividend fortresses that focus on higher yields with supporting fundamentals.
- Dial down portfolio stress by filtering for businesses in the 31 resilient stocks with low risk scores that score well on resilience and financial risk factors.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com