
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Is Manchester United (MANU) Fully Priced After Its Champions League Test?
Manchester United (NYSE:MANU) heads into a high pressure Champions League trip to Atletico Madrid after a run of domestic setbacks, while investors weigh what on pitch uncertainty might mean for this football driven media business.
Recent trading has been kinder to Manchester United, with a 1-day share price return of 1.56% and 7-day and 30-day share price returns of 3.89%, even though the 90-day share price move declined 5.53%. That short-term momentum sits against a year-to-date share price return of 32.00% and a 1-year total shareholder return of 21.60%, which suggests investors have already reacted to both on-pitch uncertainty and transfer speculation without abandoning the longer-term story around this media-driven football brand.
Scan beyond Manchester United and see how other media driven sports businesses are priced today by checking our curated list of 20 high quality undiscovered gems.
Manchester United looks like a powerful football brand with growing media and commercial reach. However, the recent share price rebound complicates the question. Are you now paying a premium for that strength, or still getting a fair deal?
Most Popular Narrative: 11.9% Undervalued
Manchester United's most followed valuation story puts fair value at $23.65, above the recent $20.83 close. This frames the current debate around how much of a successful squad rebuild is already factored into the price.
The planned midfield overhaul at Manchester United, including planned additions such as Carlos Baleba, Andrey Santos and Manu Kone, is intended to address structural weaknesses in the squad ahead of Champions League campaigns and could support future matchday and broadcasting revenue if performances stabilize.
See why 4 investors see Manchester United as 12% undervalued.
Result: Fair Value of $23.65 (UNDERVALUED)
Still, the Manchester United story can break if high wage contracts prove hard to shift, or if fresh injury setbacks derail on pitch momentum and related income.
Find out about the key risks to this Manchester United narrative.
Another View on Manchester United’s Valuation
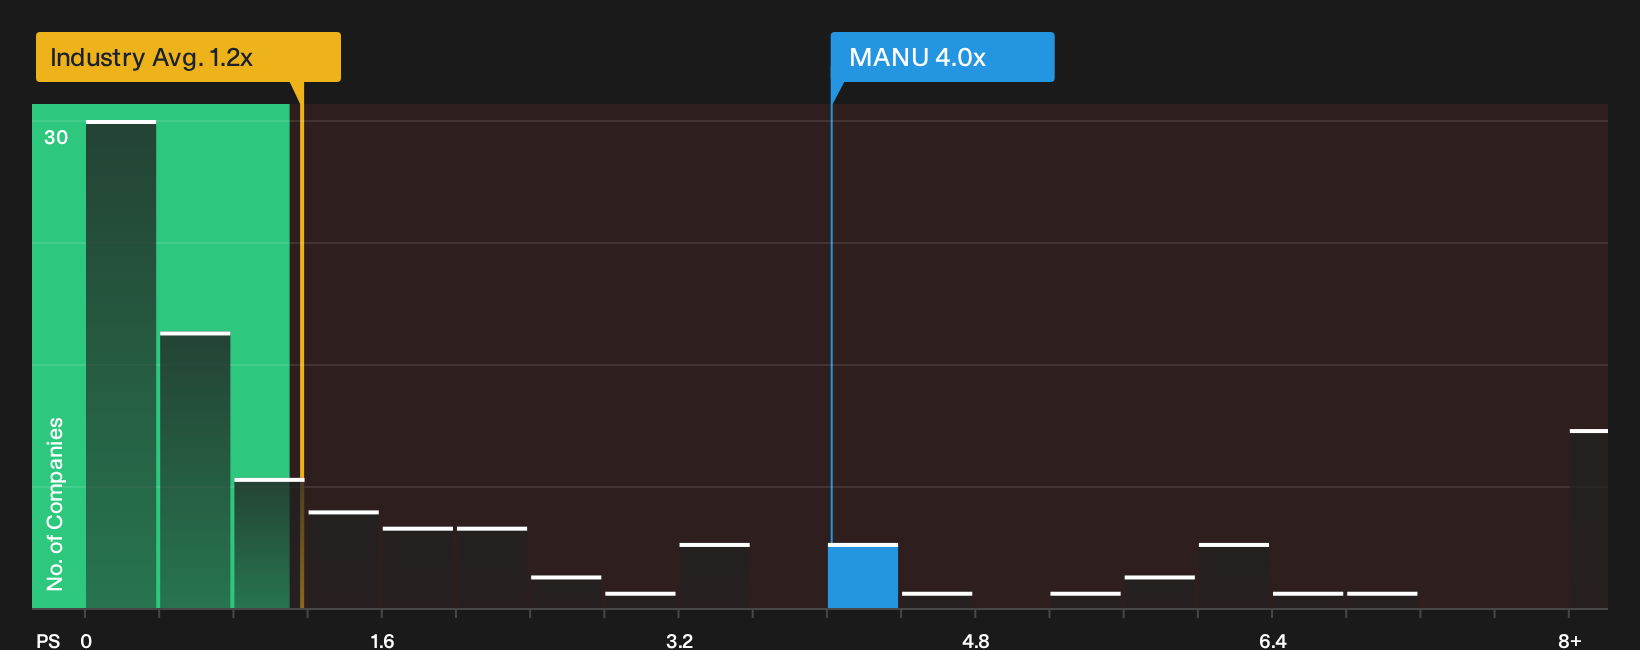
Analyst narratives lean on future earnings and cash flows to argue Manchester United is undervalued, yet the price investors currently pay for each dollar of revenue tells a tougher story. The P/S ratio sits near 4x, compared with an estimated fair ratio of 1.9x.
That same sales multiple is also far richer than both the US Entertainment group at 1.2x and closer peers at 2.6x, which signals investors are already paying a clear premium for this football driven media asset. If sentiment cools, the share price could drift back toward that fair ratio level.
For a closer look at how this premium lines up with underlying fundamentals, take a look at the See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If the mixed tone of Manchester United's recent story leaves you undecided, then treating these numbers as a starting point makes sense. Act quickly and test the thesis against your own view by digging into the 1 important warning sign
Looking for more investment ideas beyond Manchester United?
Do not stop with one football driven stock when the wider market holds plenty of other businesses with different risk profiles, income potential and growth angles.
- Target resilient balance sheets and stronger fundamentals by scanning the list of solid balance sheet and fundamentals (25 results), which surfaces companies built on sturdier financial footing.
- Hunt for quality at a reasonable price by checking the 29 high quality undervalued stocks, which highlights businesses trading below their assessed worth.
- Build a watchlist of under the radar opportunities by reviewing the 20 high quality undiscovered gems, which spotlights lesser known stocks with solid metrics.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com