
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
IPG Photonics (IPGP) Heads To Land Forces 2026, Is The Stock A Bargain?
IPG Photonics (IPGP) is stepping into the global defense spotlight as its IPG Defense unit heads to Land Forces 2026 in Perth to showcase CROSSBOW high energy laser systems, including the new CROSSBOW SE1 8 kW.
Recent trading tells a more cautious story. IPG Photonics shares are down 28.6% over the past 90 days and 9% over the past week, contributing to a 5 year total shareholder return decline of 53.4%, even as defense focused announcements like Land Forces 2026 draw fresh attention.
Scan beyond IPG Photonics and assess how other defense exposed laser and advanced manufacturing plays stack up using our hand picked 91 robotics and automation stocks.
IPG Photonics now trades well below its recent levels after that sharp 90 day slide, so are you looking at upside still ahead, or a story where most of the rerating already happened earlier?
Most Popular Narrative: 39% Undervalued
Based on the most followed narrative, IPG Photonics is priced meaningfully below an implied fair value of $124.14, compared with the recent close around $76. This gap is tied to a story that leans heavily on new end markets like medical, semiconductors, and defense to reshape the earnings profile.
New growth initiatives in medical (e.g., thulium lasers for urology), semiconductor, and micromachining end-markets are gaining early traction, diversifying revenue streams and supporting higher margins over time as these higher-value verticals scale.
See why 4 investors see IPG Photonics as 39% undervalued.
Result: Fair Value of $124.14 (UNDERVALUED)
Still, the narrative around IPG Photonics can crack if tariff friction keeps pressuring core materials processing demand, or if heavy R&D and CapEx fail to earn adequate returns.
Find out about the key risks to this IPG Photonics narrative.
Another View: What IPG Photonics’ P/E Is Telling You
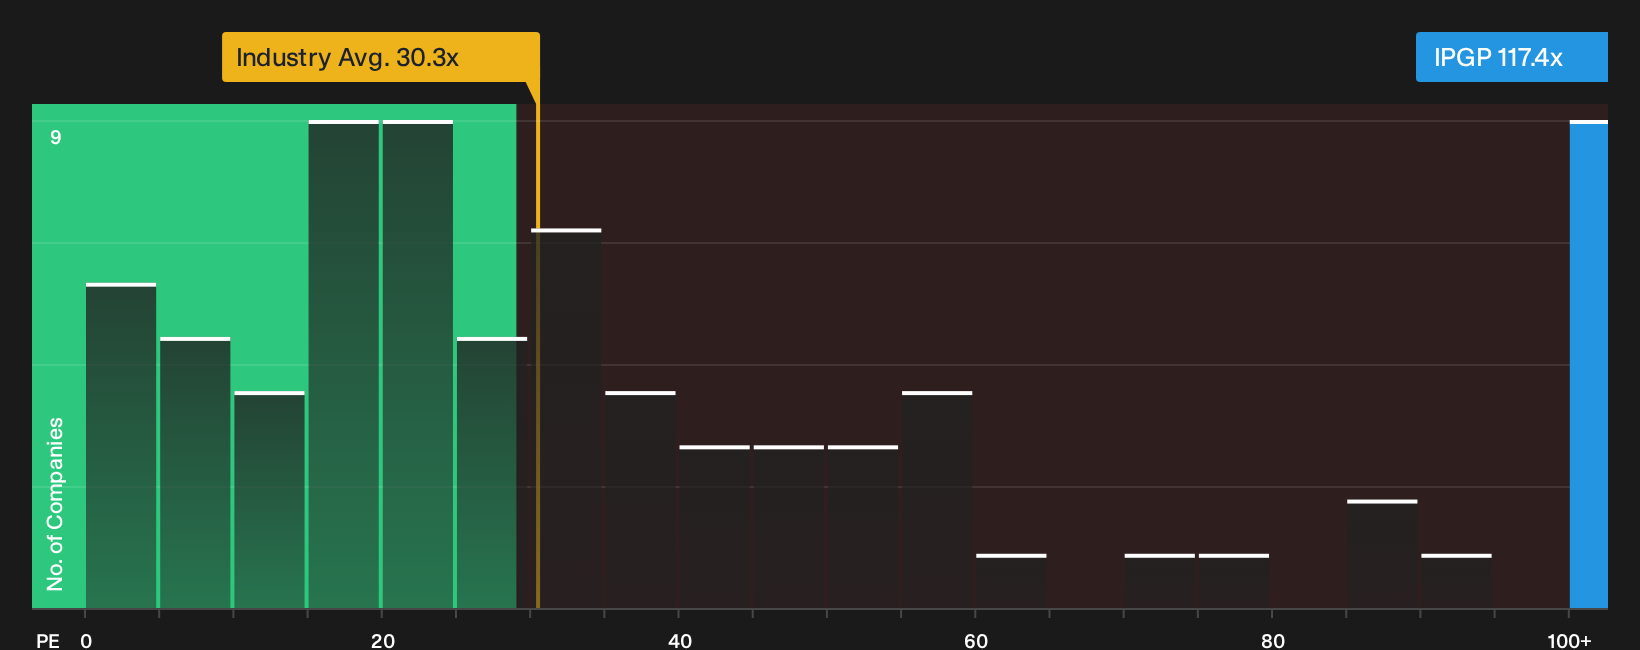
IPG Photonics might look cheap against a $124.14 fair value story, yet its P/E of 117.4x towers over the US Electronic industry on 30.3x, peers on 34.4x, and even a fair ratio of 65.4x. That gap points to valuation risk rather than a simple discount. Which signal do you trust more?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If this mix of optimism and concern around IPG Photonics feels familiar, do not sit on the fence. Consider the conflicting signals yourself, then check the 2 key rewards and 1 important warning sign.
Looking for more IPG Photonics sized opportunities?
If IPG Photonics has you thinking harder about valuation, do not stop there. Broader idea hunting can reveal better fits for your risk and return preferences.
Use the Simply Wall Street Screener to scan fresh ideas before the crowd gets there.
- Target stability with companies that pair healthy finances and resilient balance sheets through our list of solid balance sheet and fundamentals (25 results).
- Hunt for potential mispricings by filtering for quality businesses on attractive metrics using the 29 high quality undervalued stocks.
- Spot future favorites early by screening for financially sound under the radar opportunities inside the 20 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com