
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Is Applied Materials (AMAT) Undervalued As Its EPIC Center Launch Raises Big Growth Questions?
Applied Materials (AMAT) just pulled the cover off its US$5b EPIC Center in Sunnyvale, a vast semiconductor R&D hub built around joint work on chipmaking tools for the AI era.
Applied Materials shares trade at US$497.53 after a 1-day share price decline of 1.87% and a 7-day slide of 8.25%. However, the year-to-date share price return of 85.04% and 1-year total shareholder return of 127.94% suggest strong momentum that recent EPIC Center headlines have not fully cooled.
Capitalize on the EPIC Center spotlight around Applied Materials by scanning a curated set of AI hardware beneficiaries through the 92 AI infrastructure stocks.Applied Materials now trades almost 28% below the average analyst target after a sharp pullback. Is that discount caution well earned, or is it a mispricing of a still expensive leader?
Most Popular Narrative: 22% Undervalued
Applied Materials is trading at $497.53 against a widely followed fair value estimate of about $638.94. This frames the recent pullback as a discount that hinges on how well the EPIC build out and high value segments convert into future cash flows under an 11.33% discount rate.
The mix shift toward leading edge foundry logic, DRAM including high bandwidth memory, and advanced packaging is expected to account for most wafer fab equipment growth in 2026 and 2027, and Applied Materials is forecasting more than 70% growth in advanced packaging revenue and more than 50% growth in process diagnostics and control in 2026. This points to a richer product mix that can support margins and net income.
See why 317 investors see Applied Materials as 22% undervalued.
Result: Fair Value of $638.94 (UNDERVALUED)
Still, heavier EPIC and capacity spending, along with softer free cash flow or a lower P/E multiple, could quickly cool the current undervaluation story around Applied Materials.
Find out about the key risks to this Applied Materials narrative.
Another View: Our DCF Model Points The Other Way
The analyst fair value narrative paints Applied Materials as 22% undervalued. Our DCF model lands in a very different place, with an estimate of $279.56 per share, which is well below the current $497.53 price. That gap raises a simple question: Which set of assumptions do you trust more?
For readers who want to unpack how this cash flow view is built line by line, Look into how the SWS DCF model arrives at its fair value.
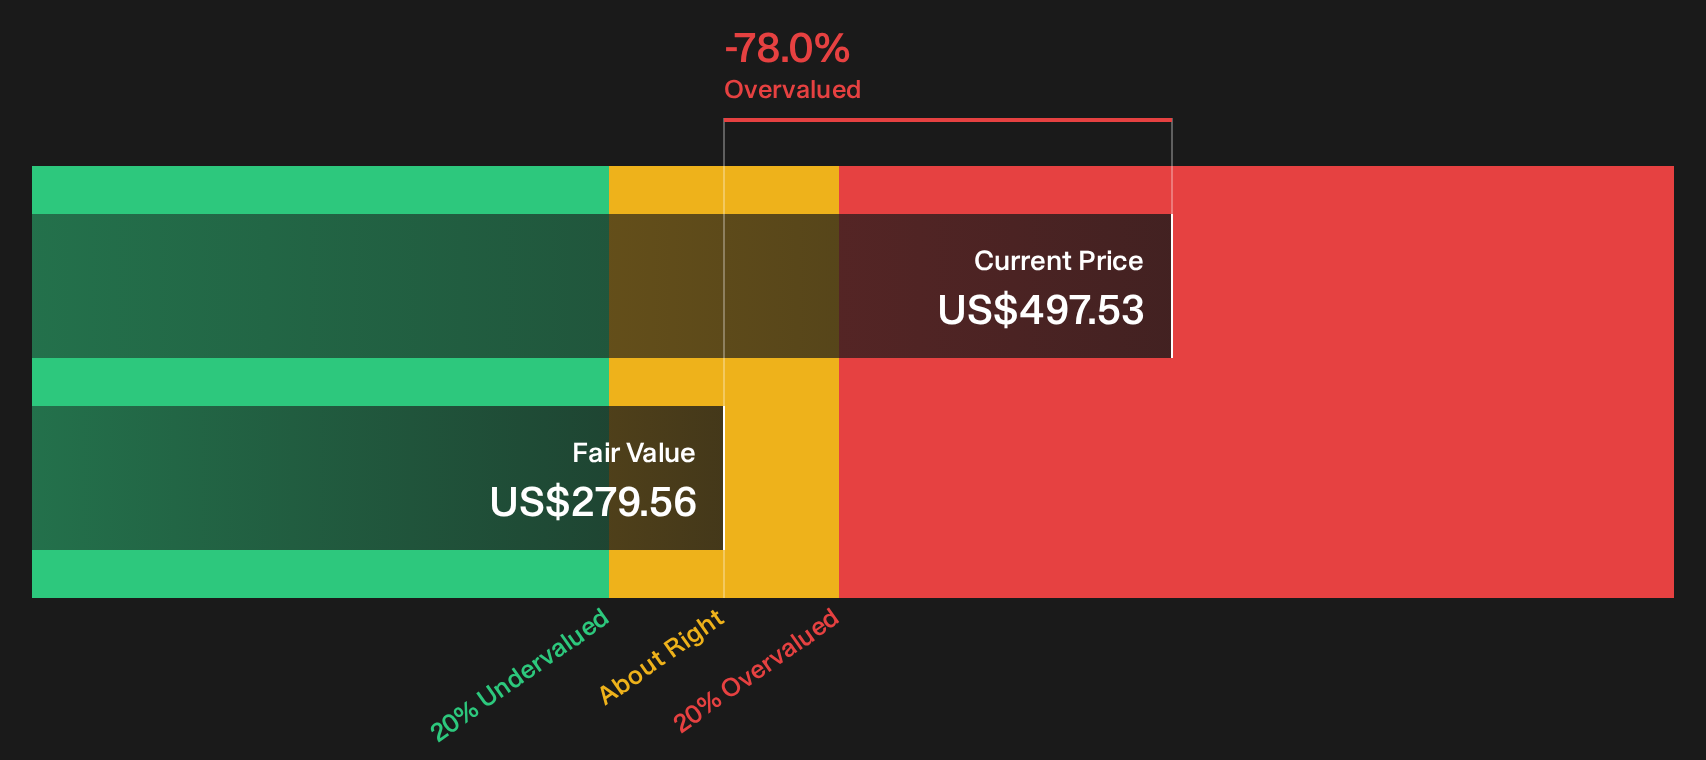
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Applied Materials for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 29 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals around Applied Materials valuation and risk can spark debate, so move quickly, review the underlying numbers, and weigh the 4 key rewards and 1 important warning sign
Want more ideas beyond Applied Materials?
If Applied Materials has sharpened your focus, now is the moment to widen the lens and hunt for other opportunities before the next move happens without you.
- Target dependable income streams by scanning companies that show up as 8 dividend fortresses and see which payouts line up with your return goals.
- Hunt for value by reviewing the 29 high quality undervalued stocks and weigh which businesses offer quality fundamentals at prices that still look reasonable.
- Prioritise resilience by checking out a 31 resilient stocks with low risk scores so you can balance higher conviction ideas with steadier holdings that support your overall plan.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com