
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Delta Air Lines (DAL) Earnings Stir Valuation Debate, Is The Stock Cheap Or Expensive?
Delta Air Lines (DAL) just released third quarter 2026 results that combined higher revenue with lower profit, placing the focus squarely on how the airline is balancing pricing, fuel costs, and guidance.
The earnings release has taken some heat out of the recent rally, with Delta Air Lines’ share price slipping 2.51% on the day and 3.57% over the past week. However, the stock still shows a 16% year to date share price return and a 37.92% total shareholder return over one year, suggesting that long term holders are still being rewarded even as near term momentum cools.
Scan how Delta Air Lines compares with other carriers and capital intensive companies by reviewing our hand picked list of solid balance sheet and fundamentals (25 results).
Delta Air Lines now trades at a sizeable discount to both intrinsic value estimates and analyst targets after the pullback. Is that gap compensation for fuel and earnings risks, or a mispricing that valuation work can clarify?
Most Popular Narrative: 26.7% Overvalued
Against a last close of $80.11, the leading narrative on Delta Air Lines pegs fair value at $63.21, placing the current price well above that estimate while still recognising the airline's strengths against peers.
Atlanta's home airline still shines bright, and indeed brighter than most in a notorious low-margin, low-profit industry. In its Q2 trading update, Delta once again trounced analysts' expectations both top and bottom line, yet there's a snag: The legacy carrier comes from all-time high profitability.
See why 23 investors see Delta Air Lines as 27% overvalued.
Result: Fair Value of $63.21 (OVERVALUED)
Still, that overvaluation story could unravel quickly if fuel costs spike again or if Delta Air Lines faces a sharper drop in international travel demand.
Find out about the key risks to this Delta Air Lines narrative.
Another View: DCF Points to Deep Undervaluation
The user narrative frames Delta Air Lines as 26.7% overvalued at $80.11, yet our DCF model reaches a very different conclusion. It values the stock at $244.40, which implies trading at 67.2% below that estimate. Is this a harsh narrative or an overly generous cash flow model?
Look into how the SWS DCF model arrives at its fair value.
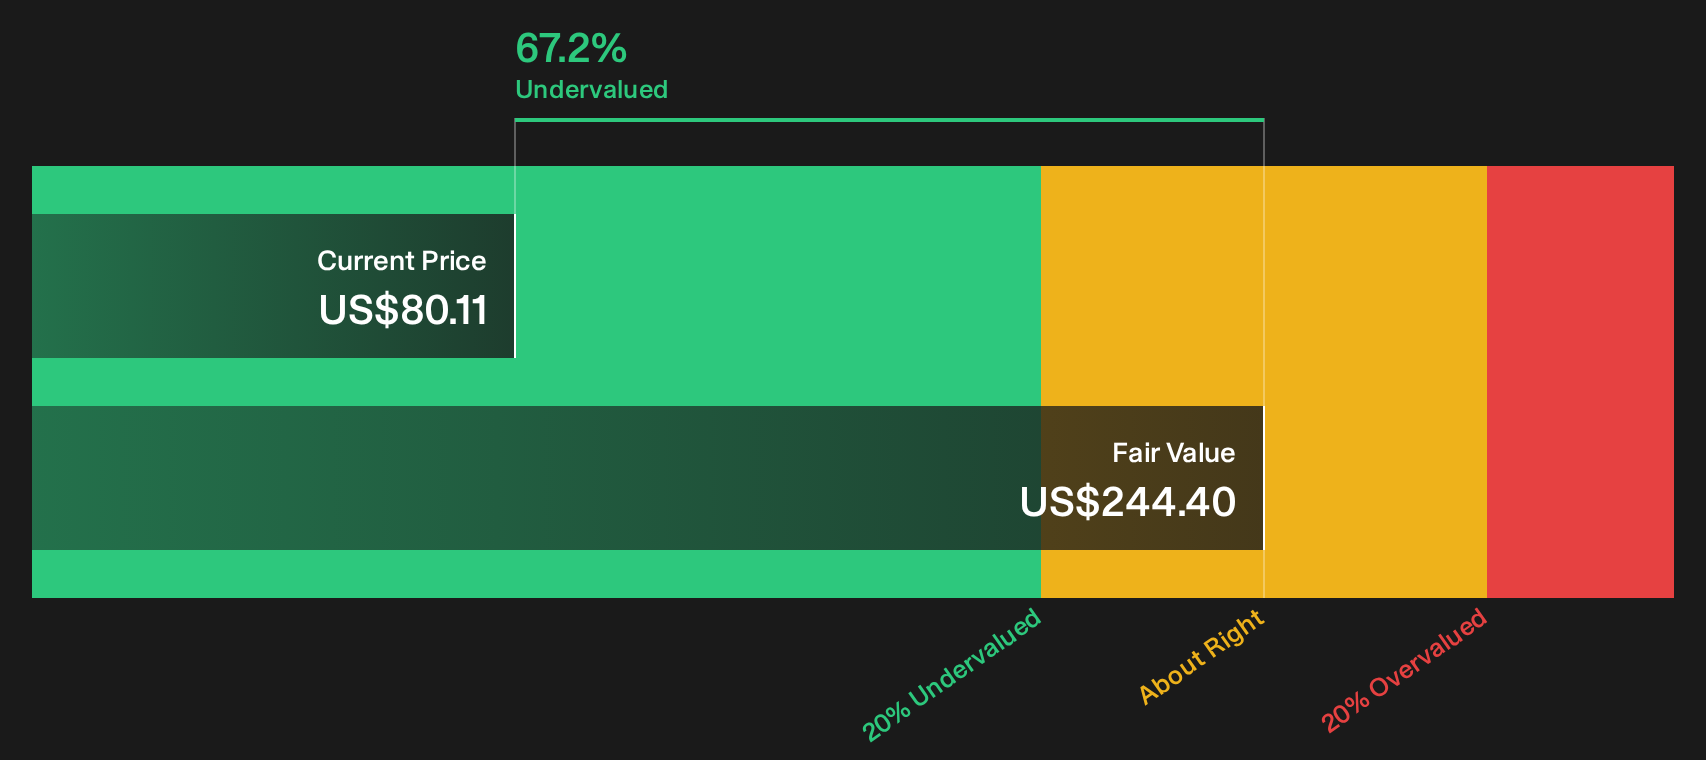
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Delta Air Lines for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 29 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
If the split between overvaluation worries and deep-value models leaves you torn, move quickly and test the numbers yourself against your own expectations. A useful place to start is by weighing the 3 key rewards and 3 important warning signs.
Looking for more investment ideas beyond Delta Air Lines?
Do not stop with one airline verdict. Use this window to widen your watchlist, pressure test your assumptions, and spot opportunities that others might miss.
- Target quality at a discount by reviewing companies in the 29 high quality undervalued stocks that pair strong fundamentals with prices that lag their implied worth.
- Prioritise resilience by scanning the 31 resilient stocks with low risk scores to find businesses with steadier risk profiles when you want fewer surprises in your portfolio.
- Get ahead of the crowd by hunting through the 20 high quality undiscovered gems where under-followed stocks with solid numbers may be waiting for attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com