
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Princes Group (LSE:PRN) Rebound Puts Valuation Back In Focus
Princes Group stock moves draw fresh attention
Princes Group (LSE:PRN) has drawn fresh attention after recent trading left the shares at £3.28, with short term returns mixed between the past week, month, and year to date.
Investors now have a food and beverage business with £1,871.531m in revenue and £35.706m in net income, with operations spread across Foods, Fish, Italian, Oils, and Drinks segments to assess at this price point.
Recent trading in Princes Group points to a modest recovery in the share price, with a 30-day share price return of 8.43% against a year to date share price decline of 27.11%. This suggests that short term momentum is picking up, while longer term sentiment remains cautious.
Compare Princes Group to a hand-picked list of solid balance sheet and fundamentals (9 results) that also combine earnings power with scale in essential consumer staples.
The recent 8.43% 30 day rebound against a 27.11% decline year to date leaves Princes Group looking like a potential reset rather than a clear verdict. Does that swing in sentiment still reward buyers at £3.28?
Price-to-Earnings of 22.5x: Is it justified for Princes Group?
Princes Group trades on a P/E of 22.5x at a share price of £3.28, which puts the stock on a richer valuation than many European food peers and raises questions about how much future progress is already reflected in the price.
The P/E ratio compares the current share price with earnings per share. For a mature food and beverage group, this metric often reflects how investors weigh stability, growth prospects, and the quality of profits, rather than rapid expansion alone.
Princes Group is viewed as expensive on this measure against both the wider European Food industry P/E of 15.6x and the closer peer group average of 18.5x. The ratio is also above an estimated fair P/E of 17.5x, which points to a valuation that could have further room to compress if the market moves closer to that level.
Explore the SWS fair ratio for Princes Group.
Result: Price-to-Earnings of 22.5x (OVERVALUED)
Still, a rich 22.5x P/E, alongside a 27.11% share price decline year to date, leaves Princes Group exposed if earnings momentum or investor confidence weakens further.
Find out about the key risks to this Princes Group narrative.
Another view on Princes Group valuation
The P/E test paints Princes Group as expensive, yet the SWS DCF model tells a very different story. On that framework, £3.28 is described as trading well below an estimated future cash flow value of £11.24. This frames the current price as a possible gap rather than just a premium. Which lens do you trust more when the signals clash?
Look into how the SWS DCF model arrives at its fair value.
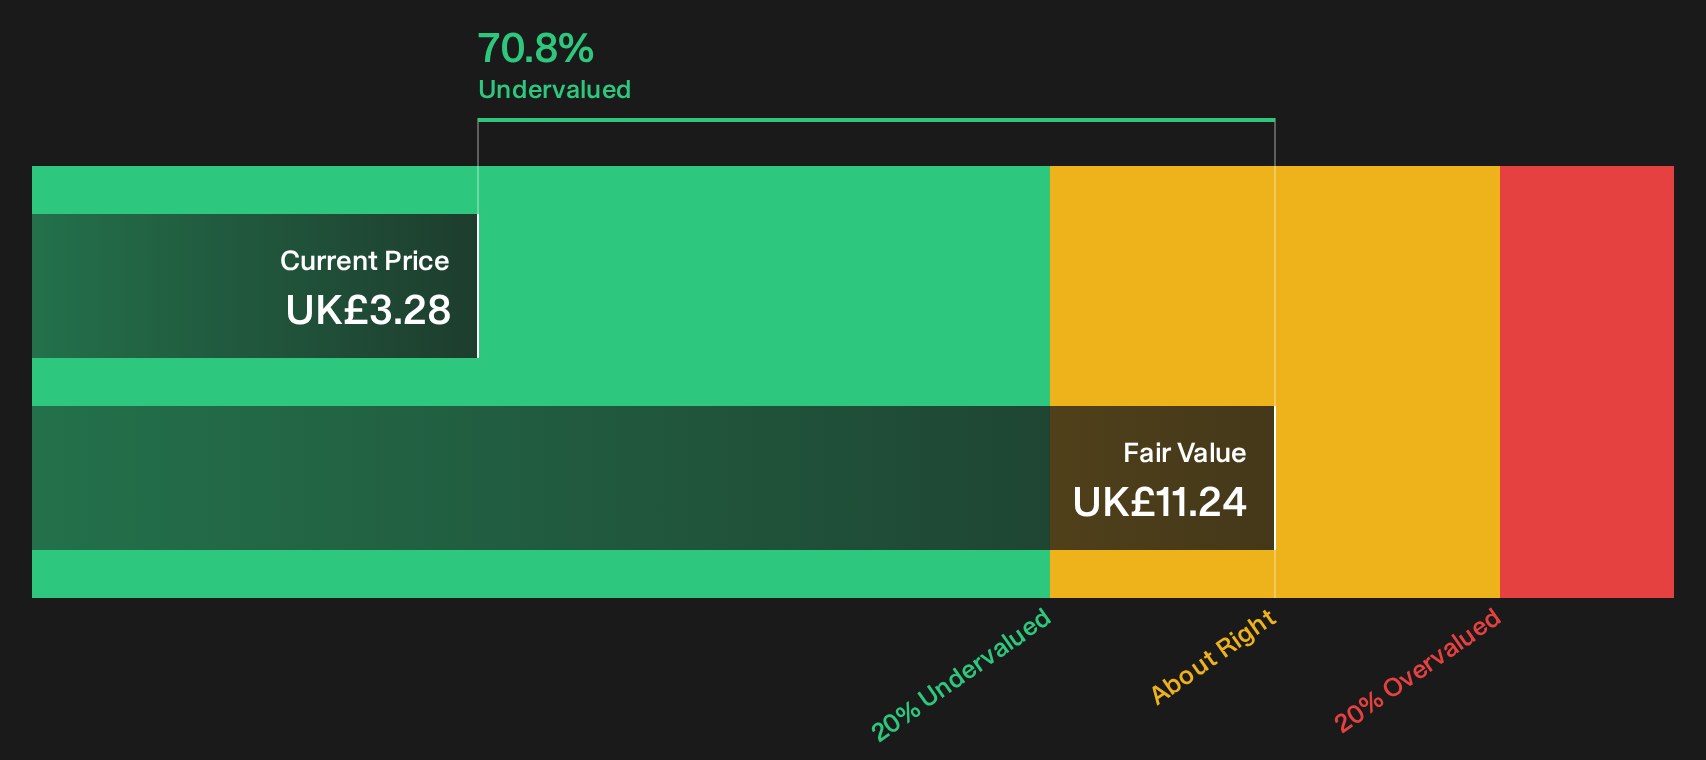
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Princes Group for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 7 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals on Princes Group so far, or a simple mismatch between price and expectations. If you want to move quickly and test that narrative against your own reading of the numbers, start by weighing the 4 key rewards
Looking for more Princes Group sized ideas?
If Princes Group has sharpened your focus on valuation and quality, do not stop here. The next opportunity could be sitting just outside your current watchlist.
- Target reliable compounding by scanning companies built around resilient cash flows and strong fundamentals with the 7 high quality undervalued stocks.
- Lock in income potential by lining up businesses that aim to combine higher yields with sturdier balance sheets through the 1 dividend fortresses.
- Spot future leaders early by tracking financially robust smaller companies that the market has not fully crowded into via the 5 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com